


Is GRAIL (GRAL) Still Below Fair Value As Fresh Galleri Data Nears?
GRAIL (GRAL) just put fresh clinical data for its Galleri multi cancer early detection test on the calendar, with new results scheduled for high profile presentations at EDCC and ESMO 2026.
The upcoming clinical readouts follow a powerful run in GRAIL’s shares, with a 30 day share price return of 84.96% and a 1 year total shareholder return of 84.98%. This performance points to strong recent momentum and shifting expectations around future risk and opportunity.
Scan beyond GRAIL and see which other early detection and healthcare breakthroughs are drawing strong interest with our curated list of 34 healthcare AI stocks
After a near doubling in a month and with fresh Galleri data on the way, GRAIL now forces a timing call. Is it wiser to lean in at US$139.70 or wait for calmer prices before committing new capital?
Most Popular Narrative: 6% Undervalued
Against GRAIL’s last close at $139.70, the most followed narrative pegs fair value at $148.32. This frames today’s strength as still short of that benchmark and puts the upcoming data readouts into sharper context for anyone weighing fresh exposure.
The NHS Galleri trial and PATHFINDER 2 together create a large body of randomized and registrational data on stage shift and safety, which can support broader physician adoption and, over time, help Galleri testing volumes and screening revenue.
See why 1 investors see GRAIL as 6% undervalued.
Result: Fair Value of $148.32 (UNDERVALUED)
Still, the GRAIL story could look very different if regulatory outcomes tighten coverage criteria or if continued annual losses constrain how long that cash runway really feels.
Find out about the key risks to this GRAIL narrative.
Another View: What GRAIL’s Sales Multiple Is Telling You
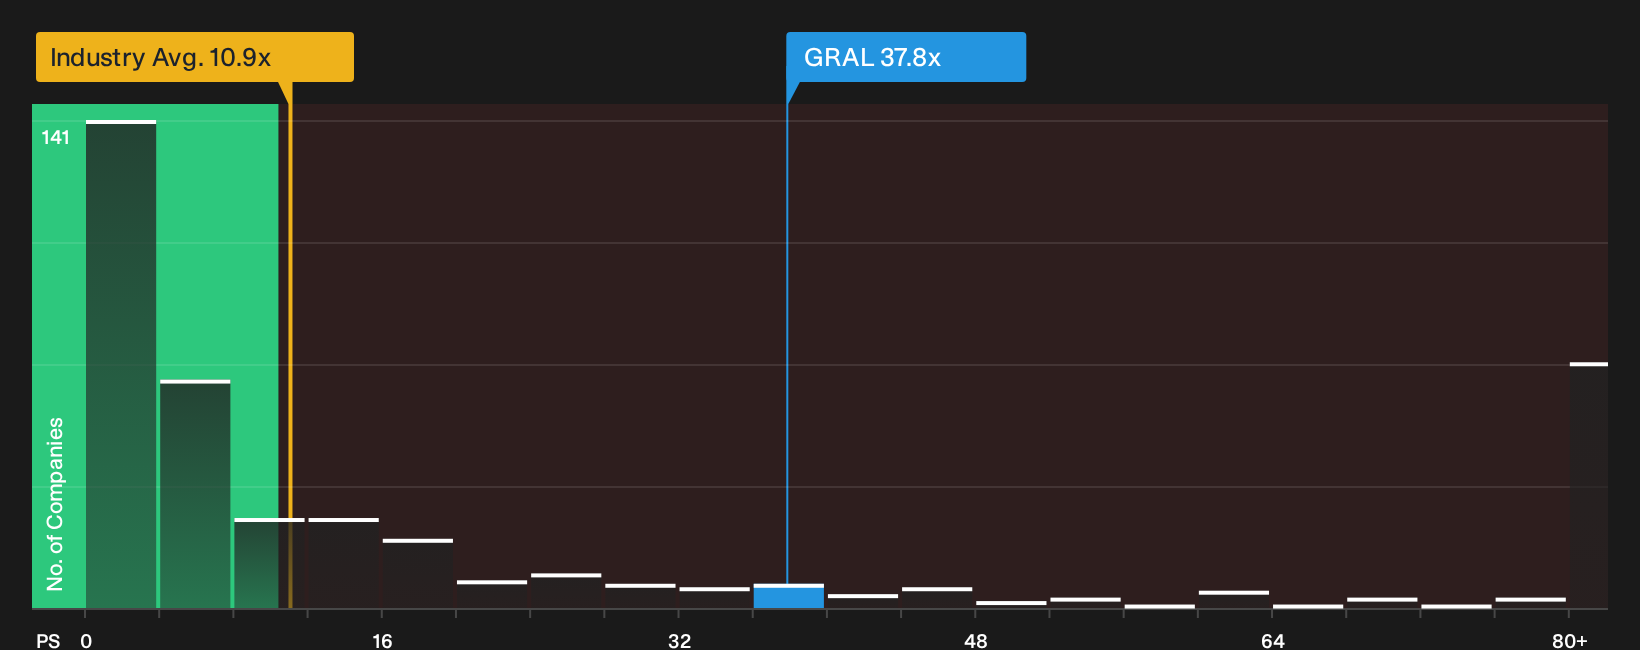
The fair value story at $148.32 leans heavily on future earnings. The P/S ratio paints a rougher picture. GRAIL trades at 37.8x sales, compared with 11.3x for the US Biotechs group and a fair ratio estimate of 8x. That is a wide gap, which raises a simple question for investors: Is this pricing a cushion of opportunity or a lot of expectation already paid upfront?
Before leaning too much on headline targets, it is worth asking what the current P/S premium implies for downside risk if sentiment cools, and how you would feel if the multiple simply drifted toward the fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around GRAIL is split, with sharp price gains on one side and clear risk flags on the other. Move quickly, review the full picture, and weigh the 2 key rewards and 5 important warning signs.
Looking for more ideas beyond GRAIL?
If GRAIL has your attention, do not stop here. Broaden your watchlist with fresh ideas filtered by quality, value, and resilience using the Simply Wall St Screener.
- Target potential mispricings by scanning a curated set of 32 high quality undervalued stocks that combine quality fundamentals with attractive entry points.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle tough funding conditions or slower revenue progress.
- Get ahead of the crowd by tracking 20 high quality undiscovered gems that pair robust metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com