


How Branded Apparel Launch Will Impact WD 40 Stock Investors
- Duluth Trading Co. recently launched a 10 piece Duluth Trading x WD-40 Brand collaboration, applying WD-40's blue and yellow branding to apparel, accessories and a WD-40 Precision Pen now sold through Duluth Trading retail stores.
- The tie up extends WD-40's reach from toolboxes into everyday workwear and fan gear, which could influence brand engagement and product awareness among Duluth's core trades and DIY audience.
- We will look at how WD-40's investment narrative is affected by this Duluth collaboration that pushes the brand into lifestyle apparel.
WD-40 Investment Narrative Recap
To own WD-40, you need to believe the maintenance franchise can keep finding new pockets of demand while protecting its 55% gross margin target against higher petroleum based input costs. The Duluth Trading collaboration is more about deepening brand visibility than moving the revenue needle, so it does not materially change the near term volume story or geographic expansion catalysts.
The more immediate swing factor remains how pricing, mix shift into premium formats and cost savings offset specialty chemical inflation that has already pressured net profit margin to 13.2%. That input cost risk looks more important for the business than whether lifestyle collaborations like Duluth gain traction with consumers.
Among recent developments, the most directly relevant is the Duluth Trading x WD-40 collection and the WD-40 Precision Pen being sold in Duluth stores. This puts WD-40 in front of a concentrated audience of tradespeople and DIY users, which lines up with the long running push into premium application formats and Specialist products.
The benefit shows up only if that extra visibility converts into higher volume for higher priced formats and wider uptake of the Precision Pen and related solutions. The risk is that the effort stays mostly in the realm of brand fandom while WD-40 still has to work through margin pressure from petroleum based inputs and keep its e-commerce and international rollout on track.
WD-40's narrative projects US$809.2 million revenue and US$93.0 million earnings by 2029. That rests on 6.2% yearly revenue growth and about US$4.0 million earnings increase from US$89.0 million today.
Uncover how WD-40's fair value indicates a 33% potential upside to its current price before the market begins to close that gap.
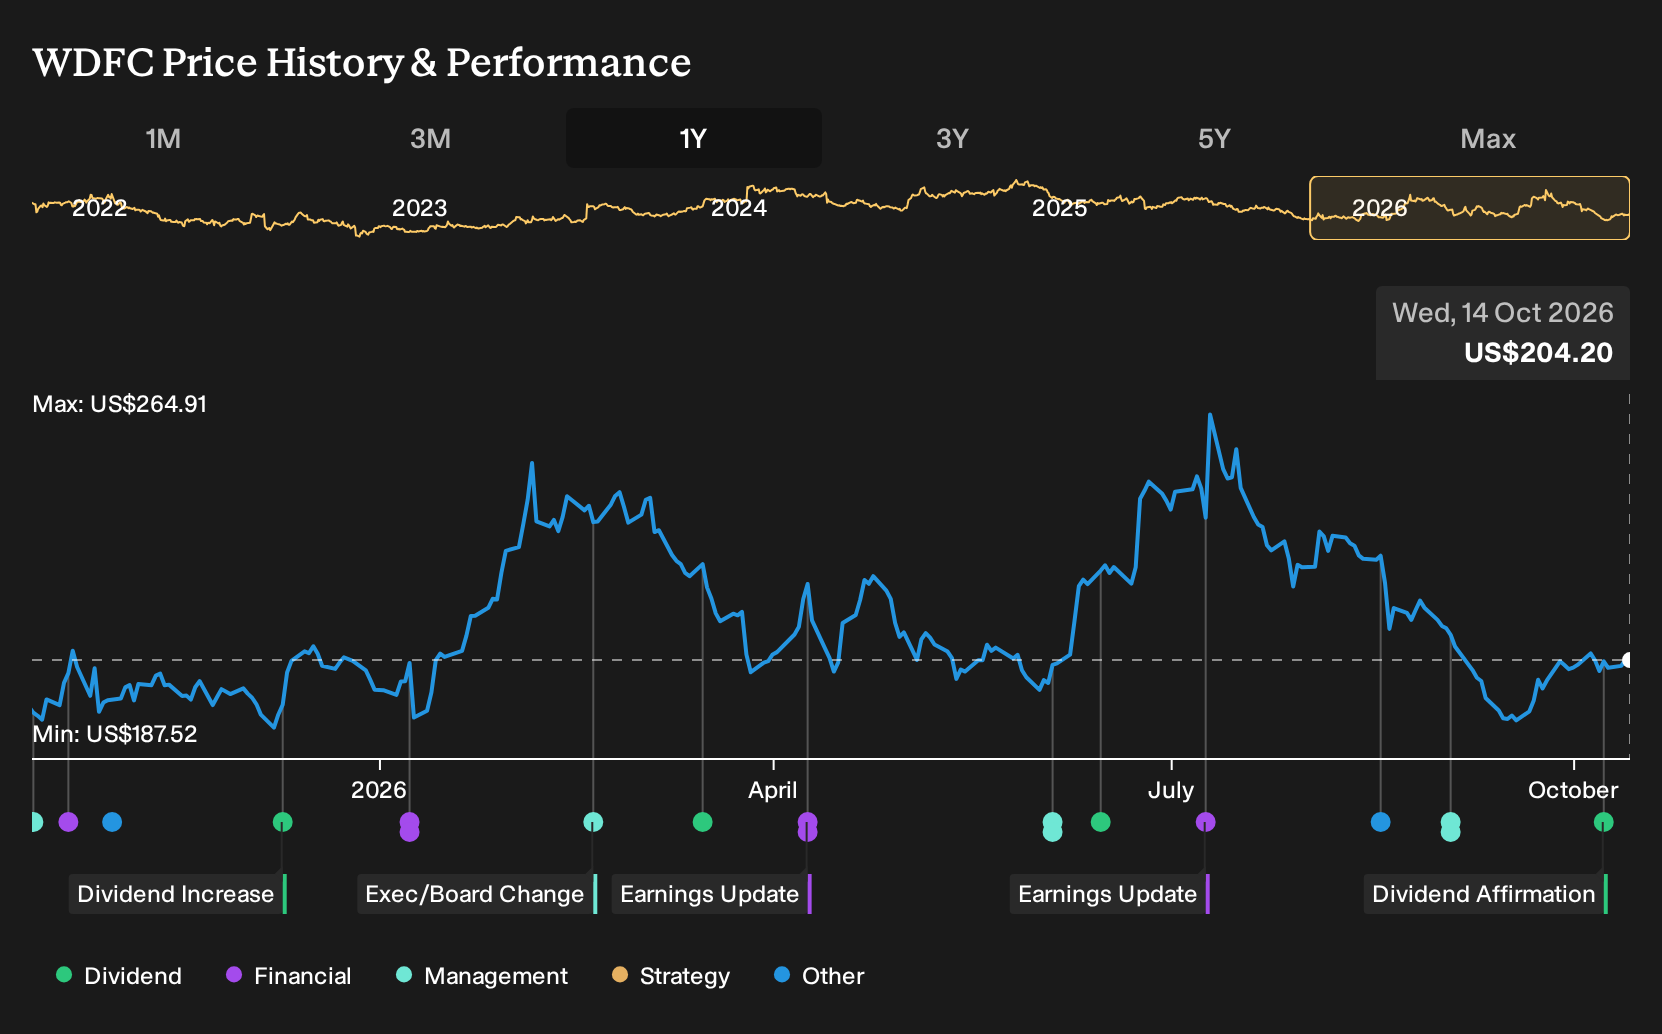
Exploring Other Perspectives
Some of the lowest WD-40 forecasts lean into slower regional momentum as the key risk, not brand reach. Those analysts were penciling in US$800.1 million revenue and US$95.3 million earnings by 2029, with a US$245.0 price target, so you see a more cautious story that the Duluth collaboration could yet reshape.
Explore 2 other WD-40 fair value estimates, including one that suggests as much as 86% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your WD-40 research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for WD-40. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WD-40's overall financial health at a glance.
Looking For More Investment Ideas Beyond WD-40?
Once you have a view on WD-40, it can help to line that thesis up against other opportunities that match your risk tolerance, income needs, and quality filters. The Simply Wall St Screener offers several ways to surface candidates that fit different styles, so you can build a watchlist that matches how you like to invest.
- If you want potential upside with a margin of safety, scan through a curated set of 32 high quality undervalued stocks that pair solid fundamentals with prices that may be out of sync with underlying quality.
- For investors who care most about resilience and balance sheet strength, focus on companies from the list of solid balance sheet and fundamentals (25 results) to see which businesses carry less financial strain.
- When steady income is a priority, filter the market using the 7 dividend fortresses and zero in on higher yielding payers that still pass key quality checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com