


Bank of America And 2 Undervalued Stocks Worth Watching
Hotter US inflation data has rattled markets and hit growth stocks, yet cash generative businesses trading below estimated fair value have quietly become more interesting. When rate expectations move, pricing gaps can open between share prices and underlying cash flows. That is where this cash flow focused value screen comes in. This article highlights three stocks from that list that currently look mispriced on their cash generation.
The three stocks featured below are only a sample from this cash flow list, and the full screen surfaced 100 more companies with equally interesting cash profiles and valuation gaps that are not covered here. To identify and analyze the highest conviction ideas from that wider universe, head straight to the Undervalued Stocks Based On Cash Flows screener.
Bank of America (BAC)
Overview: Bank of America is a large US banking group that earns most of its money from consumer and commercial lending, deposits and related financial services.
Market Cap: US$377.3b
Bank of America matters for this cash flow screen because its vast lending and deposit engines throw off recurring interest and fee income that can look mispriced when sentiment turns against big banks.
"Bank of America's continued investment in digital engagement and AI-driven efficiencies remains a live driver, with plans to double the AI budget within a US$14b technology spend and more than 140 AI applications such as Erica and CashPro already reducing support needs. This could support revenue growth and net margins as the next wave of use cases rolls out."
The real swing factor is how one underappreciated cost line shifts as these tools scale, and what that does to long term margins.
That margin shift is exactly what the full narrative for Bank of America unpacks in detail, revealing how cost compression and deposit mix could be quietly reshaping Bank of America’s cash engine.
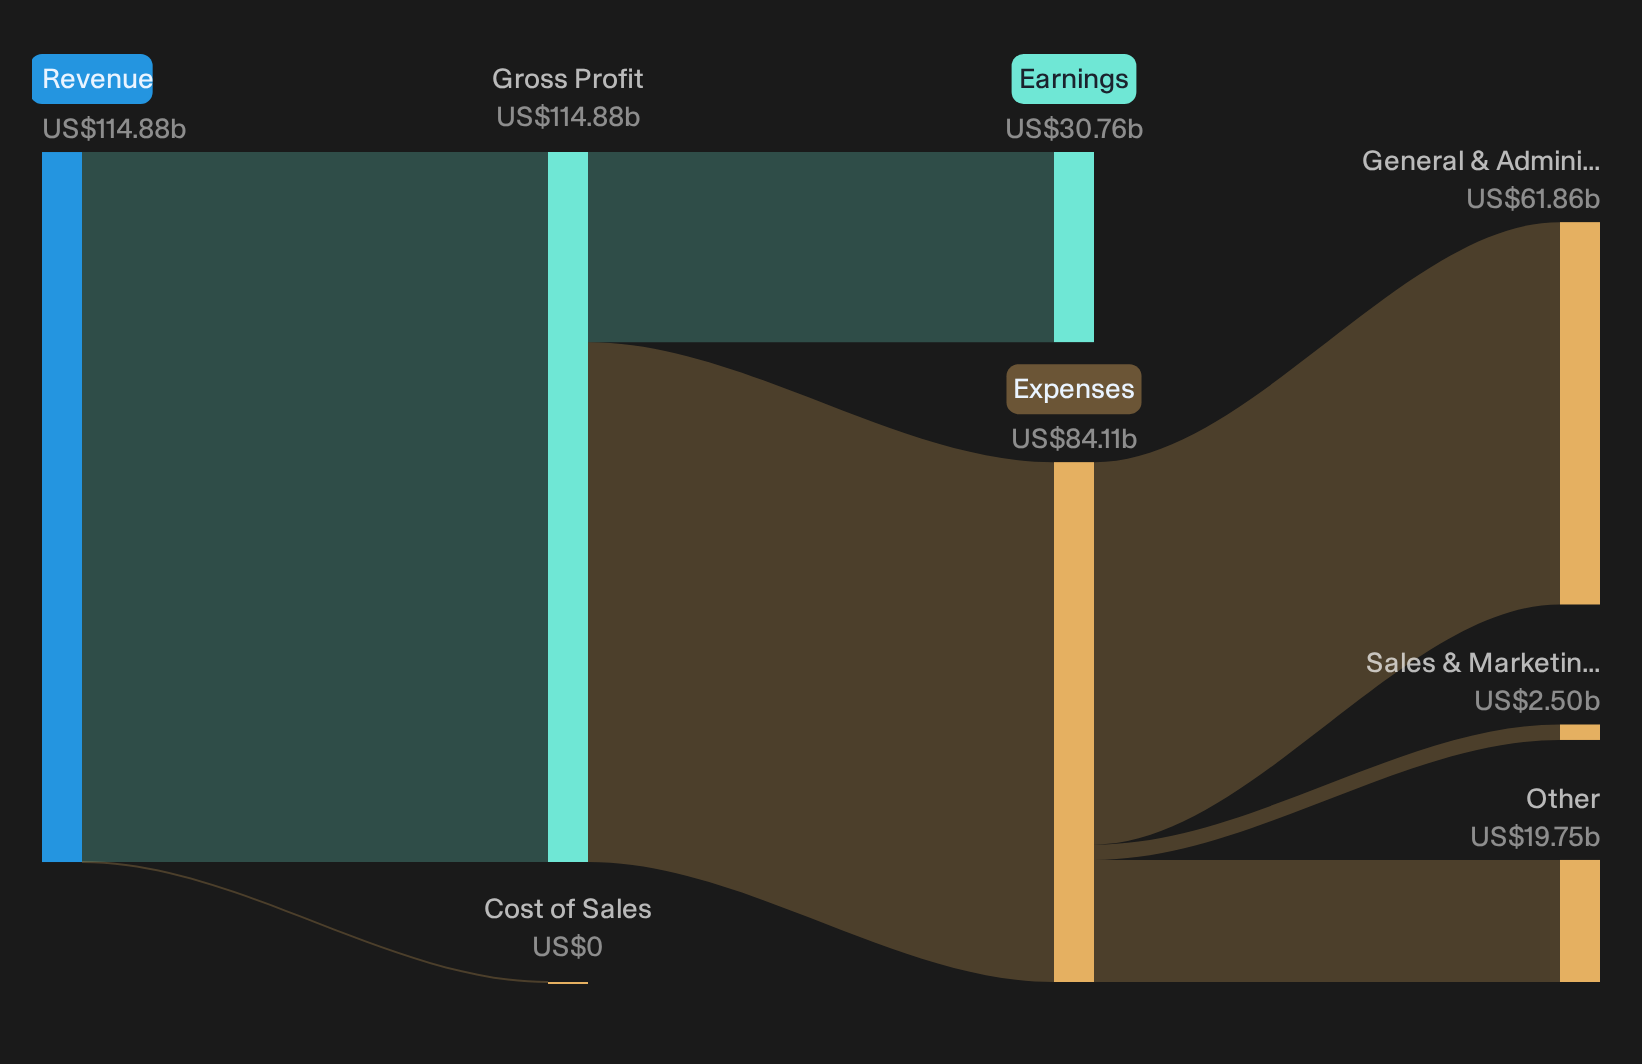
Signet Jewelers (SIG)
Overview: Signet Jewelers is a large specialty retailer selling diamond and precious metal jewelry through well known store banners and online platforms.
Operations: The retailer generates most of its revenue from the North America segment at about US$6.4b, with roughly US$423 million from International and around US$18 million from its Other segment.
Market Cap: US$4.1b
What makes Signet Jewelers interesting for a cash flow focused investor is how its big brick and mortar and online brands convert steady jewelry purchases into recurring cash that underpins the valuation work behind this screener.
"Signet continues to benefit from increasing demand among younger consumers for fashionable, personalized, and milestone jewelry, supported by new product assortments, targeted marketing, and modernized store experiences, expected to drive topline growth and enhance average unit retail (AUR) in both fashion and bridal segments."
The real swing factor is whether one quiet shift in how those higher ticket baskets translate into lasting profit margins actually sticks.
If that profit shift is what you are watching, the full narrative for Signet Jewelers shows how Signet Jewelers’ cash engine could be quietly accelerating beyond headline sales.

Alphabet (GOOGL)
Overview: Alphabet is a global technology group whose Google Cloud AI infrastructure and Google Services platforms power advertising, subscriptions, and digital tools.
Operations: Alphabet generates most revenue from Google Services at about US$367.1b, with US$77.6b from Google Cloud and around US$1.5b from Other Bets.
Market Cap: US$4,231.3b
Alphabet matters for this cash flow screen because Google Cloud’s AI infrastructure and Vertex AI platform convert usage based enterprise demand into longer running cash streams that can be valued differently from its advertising heavy past.
"Google Cloud has gone from “meh” to money-maker. As of 2023, Cloud turned operating profitable, and that momentum continues."
The real hinge for cash focused investors is how one massive pipeline of contracted AI workloads ultimately filters into lasting margins and free cash generation.
That is where the full narrative for Alphabet really kicks in and maps how Alphabet’s AI cash engine could decouple earnings power from past advertising cycles.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. The strongest candidates can gain momentum quickly while weaker stories get caught dropping. Scan these under the radar lists before the crowd and review them now.
- Target dependable income streams by reviewing 7 dividend fortresses that focus on payout strength and balance sheet resilience, so you are not chasing yield after prices move.
- Spot early AI momentum by scanning 39 profitable AI stocks that aren't just burning cash where cash generating operators, not story stocks, are filtered for you while they are still under the radar.
- Position for long term infrastructure demand by checking 43 power grid technology and infrastructure stocks packed with curated operators tied to grid upgrades so slower investors are not left catching up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com