


Learn Why The Bull Case For Meta Could Change Following AI Model Launch
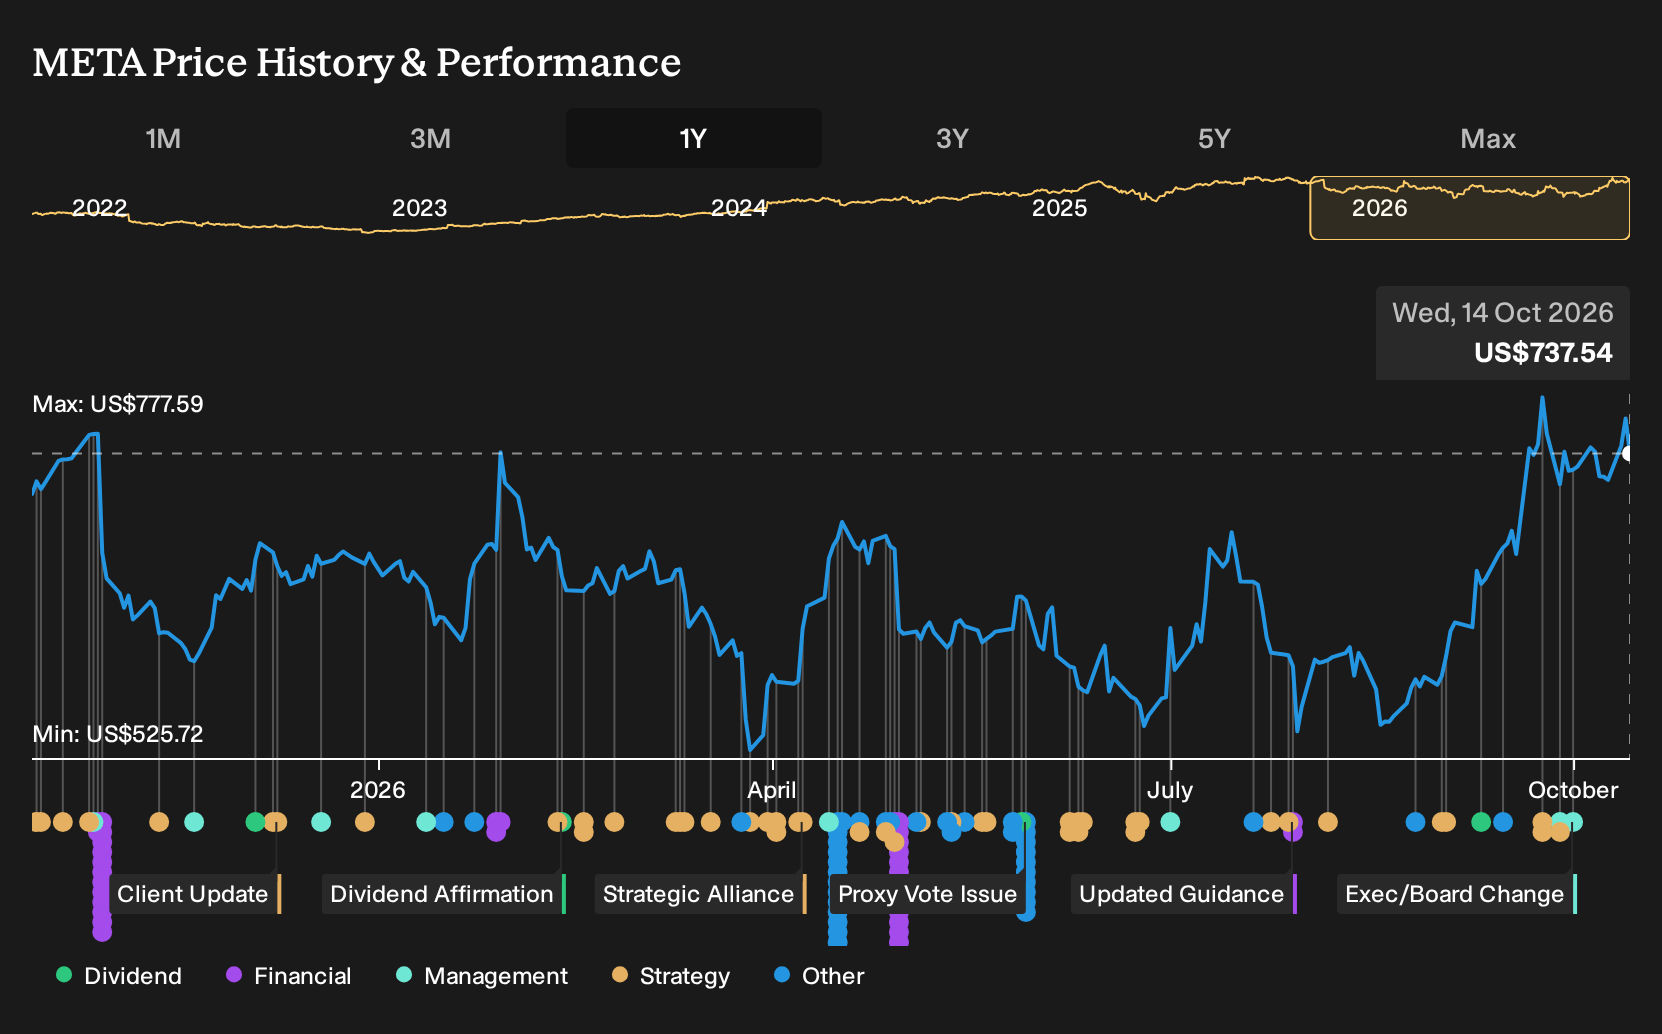
- Meta Platforms released its Muse Wonder AI model in October 2026, reporting 83.2% accuracy on the DualEntry Accounting AI Benchmark, ahead of all tested OpenAI and Google models and sharply above prior Muse Spark 1.1 performance at 61.4%.
- Muse Wonder’s strength in financial reporting tasks, paired with Meta’s push to embed Muse agents into small business and enterprise workflows, points to a broader shift from pure advertising reliance toward subscription, API and workflow revenue tied to heavy AI infrastructure spending.
- We will now look at how Meta Platforms' investment narrative could shift as Muse Wonder raises the bar for AI capability.
Scan how Meta Platforms’ AI push compares with other potential breakouts by tracking the 92 AI infrastructure stocks that powers the next wave of high-intensity compute and agentic workloads.
Meta Platforms Investment Narrative Recap
To own Meta Platforms today, you need to believe its heavy AI and infrastructure spending eventually supports a broader business than advertising alone. Muse Wonder’s strong accounting benchmark score reinforces that AI is now a core operating focus rather than a side project. The key short term catalyst is execution on paid Muse subscriptions and business use, which could help offset rising capital intensity.
The biggest near term risk is that operating expenses and capex tied to AI clusters and data centers run ahead of revenue, squeezing margins and free cash flow. Reality Labs losses and uncertain monetization from metaverse and long horizon AI bets remain a drag, and Muse Wonder’s launch does not change that risk in a material way yet.
The Muse Wonder release is most directly tied to Meta Platforms’ push to commercialize AI agents. Management is talking about hundreds of billions of dollars of planned AI investment, and Bank of America and others see Muse Wonder and Muse Wonder Full as important proof points that the firm can compete at the top tier of AI capability. That matters because paid access, enterprise contracts and API consumption depend on models being credible alternatives to OpenAI and Anthropic.
For you as an investor, the operational question is whether Muse and Muse Wonder gain enough real world usage across consumers, small businesses and larger enterprises to justify ongoing capex. Early usage metrics for Muse, integration into tools like Shopify and Box, and commentary around upcoming Q3 results on “Family of Apps other revenue” and capex guidance look central. They help indicate whether AI subscriptions, workflow tools and potential cloud style AI compute sales can gradually balance the cost of Meta’s very large AI build out.
Meta Platforms’ current analyst narrative points to US$387.4b in revenue and US$115.5b in earnings by 2029, based on a projected 19.3% yearly revenue growth rate and an earnings increase of about US$47.4b from US$68.1b today.
Uncover how Meta Platforms' fair value indicates an 8% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Some of the lowest Meta Platforms forecasts lean hard into the risk that free cash flow stays tight. Those analysts were pencilling in revenue of about US$365.4b and earnings near US$90.1b by 2029, well below consensus. You can treat Muse Wonder’s accounting strength as a fresh datapoint that could shift either storyline. As a result, it is worth exploring both possibilities.
Explore 61 other Meta Platforms fair value estimates, including one that suggests as much as 41% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Meta Platforms research is our analysis highlighting 1 key reward, which could impact your investment decision.
- See our latest analysis for Meta Platforms. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meta Platforms' overall financial health at a glance.
Looking for more investment ideas beyond Meta Platforms?
Once you have a view on Meta Platforms, it can help to scan a wider field of opportunities so you are not relying on a single story playing out as expected.
- If capital preservation comes first for you, consider checking a screener focused on 32 resilient stocks with low risk scores, which may better match a cautious style.
- For investors who want financial strength at the foundation, walk through a list of solid balance sheet and fundamentals (25 results) to see which businesses pair cleaner balance sheets with solid fundamentals.
- If you are hunting for potential future leaders before they hit the headlines, spend time with a curated 20 high quality undiscovered gems that might align with a more opportunistic approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com