


Raised Guidance Could Change The Case For Nextpower Stock
- Nextpower recently raised the lower end of several fiscal 2027 guidance ranges after beating first quarter earnings estimates and is directing more capital toward power conversion, energy storage and software to broaden its revenue mix beyond core solar trackers.
- The shift into higher value offerings such as storage, inverters and yield management software increases potential revenue per project but brings higher spending and execution complexity as the backlog above $5.5b is converted.
- We will now examine how Nextpower's raised long term guidance, anchored by its expanding storage and inverter platform, could reshape the investment narrative.
Scan for other grid and renewables plays preparing for similar project backlogs by reviewing the hand picked 43 power grid technology and infrastructure stocks alongside your work on Nextpower.
Nextpower Investment Narrative Recap
To own Nextpower, you need to believe the platform can turn a more than US$5.5b backlog and expanded storage and inverter suite into steady execution, despite past quarters where delivery and guidance have fallen short. The raised fiscal 2027 guidance floor signals management confidence in current operations rather than a fundamental reset of the story.
The key short term swing factor is whether newer storage, inverter and software lines scale cleanly without repeating prior revenue and EBITDA misses. Interconnection delays and higher manufacturing and R&D spend remain the biggest operational risks, so the guidance lift matters mainly as a real time check on how that ramp is tracking.
The updated outlook that lifts the lower end of 2027 ranges is the announcement most directly tied to this news. It connects to earlier commentary around storage acquisitions such as Prevalon, the US$300m of acquired storage backlog and plans to add more than 10 GW of U.S. inverter capacity starting in 2027.
For investors, that raised guidance bracket sits alongside concrete execution markers. These include how quickly Prevalon contracts for 1.3 GW of AI and hyperscaler data centers convert, how the eBOS run rate above US$100m progresses and whether the Idaho 800 MWh project and PowerMerge backlog over 2 GW are delivered without fresh cost or timing surprises.
Nextpower Long Term Consensus Setup
Nextpower now has a clearer long term sketch from analysts that sits behind the raised guidance and the push into storage and inverters. The story on paper is of a business that leans on its US$5.5b plus backlog while layering in higher value software and power conversion, with analysts trying to translate that into future revenue, margins and a valuation that lines up with the new product mix.
Consensus assumptions start with the top line. Analysts are working off revenue growth of 18.9% a year over the next three years, paired with profit margins that move from 16.4% today to 15.4% by 2029. That combination implies faster sales but slightly thinner profitability per dollar, which fits a company spending more on manufacturing expansion, storage integration and software development as it scales a broader grid offering.
Earnings expectations are specific. Forecast consensus points to US$937.7m of earnings, or US$5.99 per share, by 2029 compared with US$594.1m today, with the most optimistic forecasts stretching as high as US$1.1b. The step up from roughly US$600m to just under US$1b reflects the view that the larger backlog plus storage and inverter ramp can support higher absolute profit even with modest margin compression.
On valuation, analysts are effectively tying that 2029 earnings line to a richer multiple. Their price targets assume Nextpower trades on a P/E of 31.4x in 2029, versus 21.5x today, which they note still sits below the current 36.6x P/E for the broader US Electrical industry. That gap suggests the market is being asked to accept a higher earnings multiple than it does today, but not one that outstrips the sector’s current benchmark.
Those earnings forecasts also feed into the share count and discount math. Expectations for shares outstanding to grow 2.25% a year over the next three years build in equity-based compensation and potential capital raises, while discount rates around 9.4% are being applied to pull those 2029 cash flows back into today’s dollars. The choice of discount rate matters because it calibrates how sensitive any fair value estimate is to macro risk and execution uncertainty.
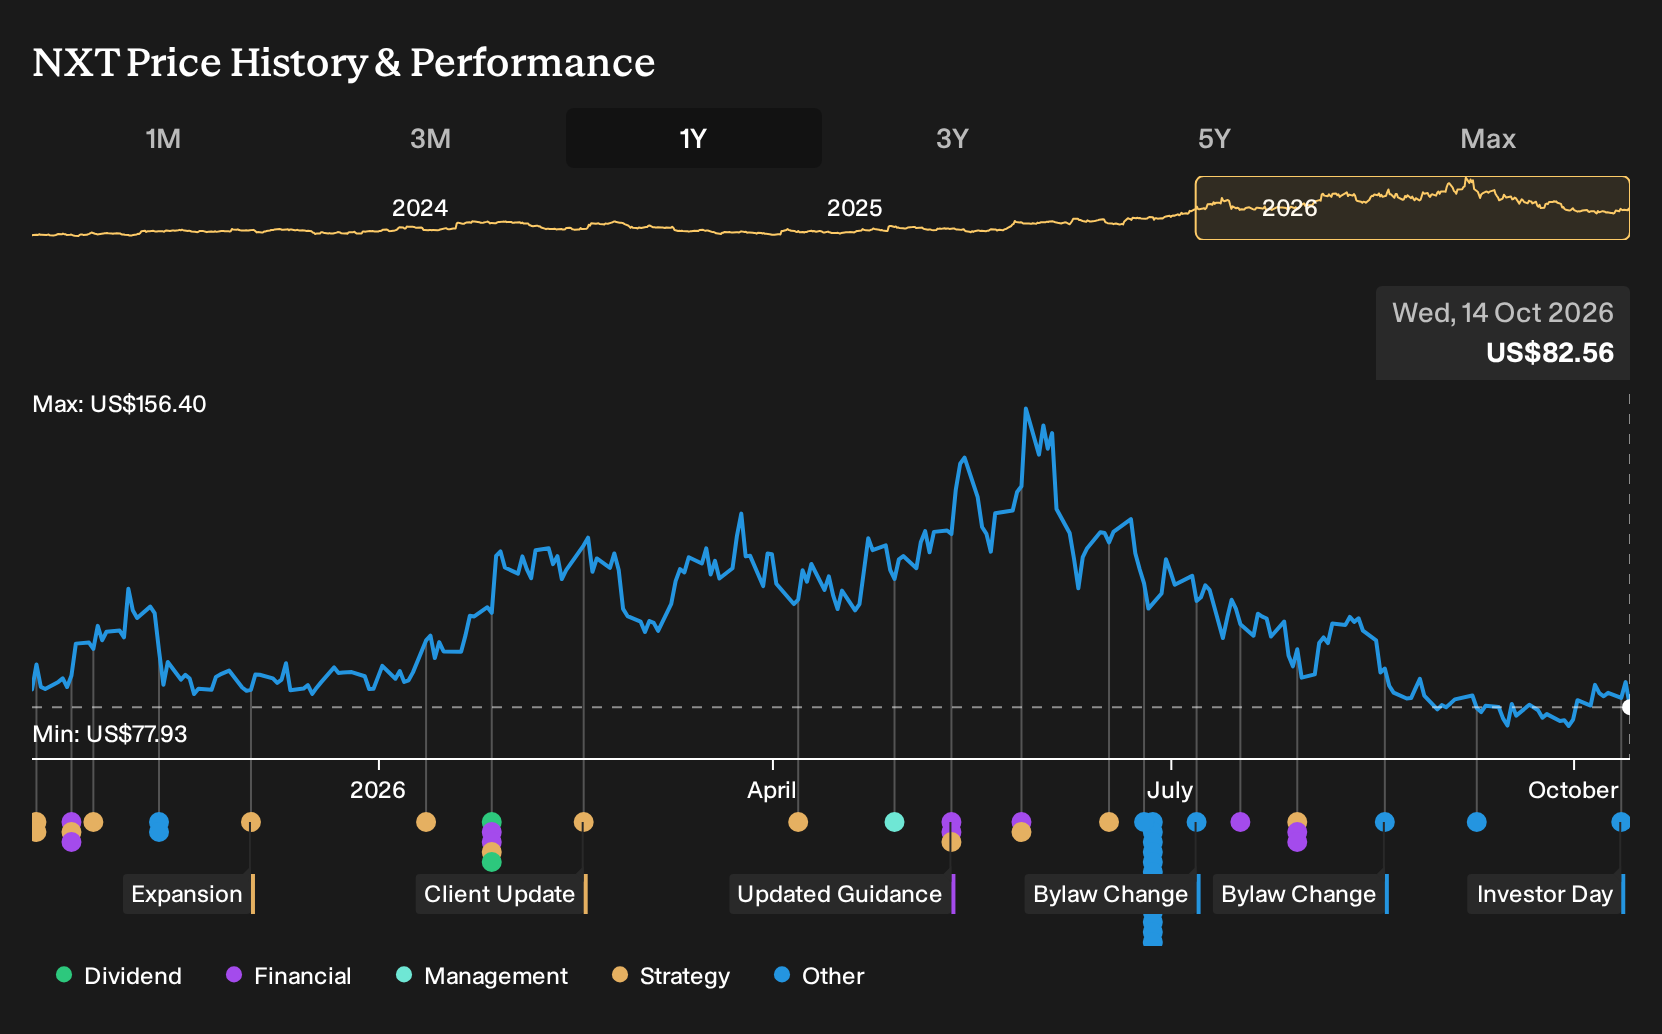
Price targets then sit on top of these building blocks. The current consensus target is US$138.96 per share, with the bullish end at US$175 and the bearish end at US$70, against a spot price of US$84.30 as of mid October 2026. That spread reflects real disagreement about how much of the revenue backlog and earnings potential from storage, inverters and software should be credited today given the execution track record and recent guidance misses.
For anyone assessing Nextpower, these numbers are less a script and more a reference point. They show what has to go right on revenue growth, margin trend, earnings power and valuation multiples for the stock to line up with current analyst expectations. The practical question is whether the raised 2027 guidance, the storage and inverter expansion and the company’s ability to work through grid bottlenecks make those assumptions feel conservative, aggressive or roughly balanced.
Nextpower's narrative projects US$6.1b revenue and US$937.7m earnings by 2029. That setup is built on 18.9% yearly revenue growth and an earnings increase of around US$343.6m from US$594.1m today.
Uncover why Nextpower's fair value indicates a potential 68% upside to its current price, a valuation gap that could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on data center storage as the real swing factor for Nextpower. The most bullish analysts were penciling in US$7.1b of 2029 revenue and US$1.1b of earnings before this guidance news, far above consensus. That is a much more optimistic story. Use it as a contrast and explore how such expectations might shift now.
Explore 4 other Nextpower fair value estimates, including one that suggests as much as 112% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nextpower research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nextpower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nextpower's overall financial health at a glance.
Looking for more investment ideas beyond Nextpower?
Once you have a view on Nextpower, it can be useful to widen the lens and compare it with other listed businesses that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential value with a margin of safety, start with a curated set of 32 high quality undervalued stocks that combine quality fundamentals with discounted pricing.
- For investors who put balance sheet strength first, consider a list of solid balance sheet and fundamentals (25 results) that can help cushion portfolio volatility when conditions get tougher.
- To uncover less crowded ideas, scan through a 20 high quality undiscovered gems that have solid financial underpinnings yet attract relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com