


TPG Telecom (ASX:TPG) Wins A Stable S And P Outlook, Is The Stock Still Cheap?
Why S&P’s outlook shift on TPG Telecom matters
S&P Global Ratings has moved TPG Telecom (ASX:TPG) from a negative to a stable outlook, while keeping its BBB credit rating, after reassessing its mobile earnings and network agreement with Singtel Optus.
At A$3.69, TPG Telecom’s share price has drifted over the past month, with the 30 day share price return down 3.91% and the year to date share price return down 4.65%. However, the 1 year total shareholder return of 3.59% and 3 year total shareholder return of 5.98% suggest slower but still positive momentum building over a longer stretch.
Spot opportunities beyond TPG Telecom by scanning a curated 6 resilient stocks with low risk scores that maintains a similar focus on balance sheet resilience and steadier return potential.The credit outlook looks steadier and TPG Telecom’s mobile reach is wider, yet the share price has drifted. Is a solid telecom business quietly on sale or already fairly valued?
Most Popular Narrative: 10% Undervalued
On Simply Wall St’s most-followed view, TPG Telecom screens as undervalued, with a fair value estimate of A$4.12 against the recent A$3.69 share price and a 7.0% discount rate anchoring that work.
Material network and IT investment cycles, including 5G rollout, Huawei equipment replacement, and brand system overhauls, are now largely complete. This is set to create a multi-year period of structurally lower capex. The company expects this to directly support free cash flow conversion and capital returns, and also enable cost reductions (A$100m targeted by 2029) to flow through to net profit.
See why 20 investors see TPG Telecom as 10% undervalued.
Result: Fair Value of A$4.12 (UNDERVALUED)
Still, the bullish TPG Telecom story frays quickly if intense mobile and broadband competition caps pricing power, or if complex IT consolidation disrupts customers and lifts churn.
Find out about the key risks to this TPG Telecom narrative.
Another view on TPG Telecom’s valuation
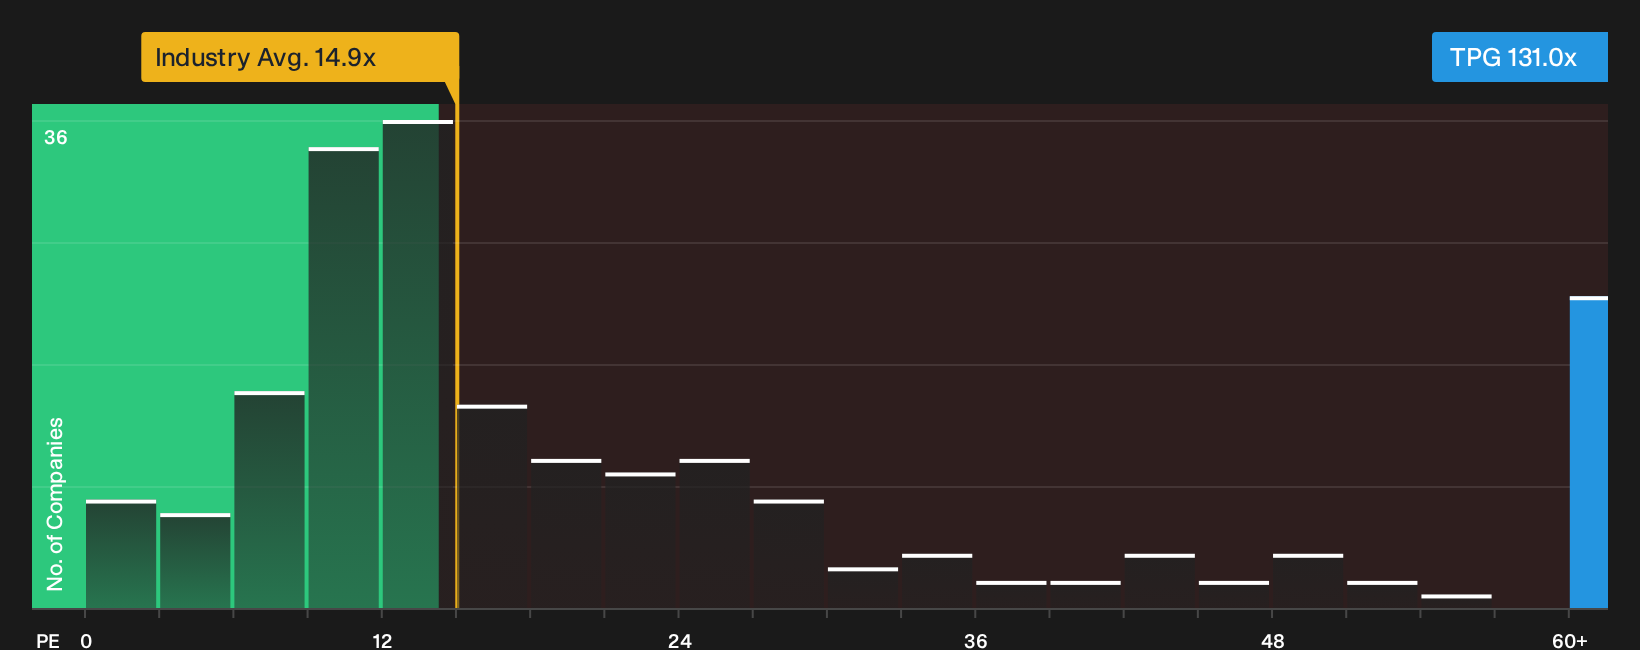
The discounted cash flow work paints TPG Telecom as undervalued, yet the market is asking a very full price on simpler yardsticks. The P/E sits at 131x, compared with a fair ratio of 45.9x, the Australian telecom peer average of 33.6x and the global industry at 14.9x. Is the DCF right, or are multiples flashing a warning?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mixed picture around TPG Telecom feels unresolved, move quickly from reading to checking the numbers yourself and weigh both sides of the story. Then pressure test your own view against the balance of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond TPG Telecom?
You have seen how one telecom stock lines up on value, risk and returns. Now widen the lens and pressure test your next move with diversified ideas.
- Target steady cash generators and resilient balance sheets by scanning a focused list of solid balance sheet and fundamentals (12 results). This can help anchor the risk side of your portfolio.
- Hunt for quality priced below intrinsic value by running through a curated 4 high quality undervalued stocks so the spotlight stays on fundamentals instead of headlines.
- Spot potential outliers before the crowd by reviewing a tailored 15 high quality undiscovered gems that highlights strong businesses still flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com