


Archer Aviation (ACHR) Stock Looks Below Fair Value Following Its 69% Slide
Archer Aviation has seen its share price fall sharply over the past year, and the slide raises a straightforward question for investors who care about fundamentals. Is the current market value of the stock still in line with what its balance sheet and book value can reasonably support?
- The share price declined 68.8% over the past 12 months, which puts the recent move front and center when you weigh the stock against what its underlying net assets are worth on paper.
- Management plans to acquire three Boeing owned businesses, including drone maker Insitu, in an all stock deal that could reshape Archer's asset base, revenue mix and future funding needs once the transaction closes.
- There is a second opinion on Archer Aviation worth weighing. See what analysts think Archer Aviation's shares could be worth.
The issue now is whether Archer Aviation's current share price is justified when set against the book value that investors are effectively buying into today.
If you want more ideas beyond Archer Aviation while you think through book value and balance-sheet risk, a focused screen of 32 resilient stocks with low risk scores can be a useful next step.
Is Archer Aviation Still Cheap on Book Value?
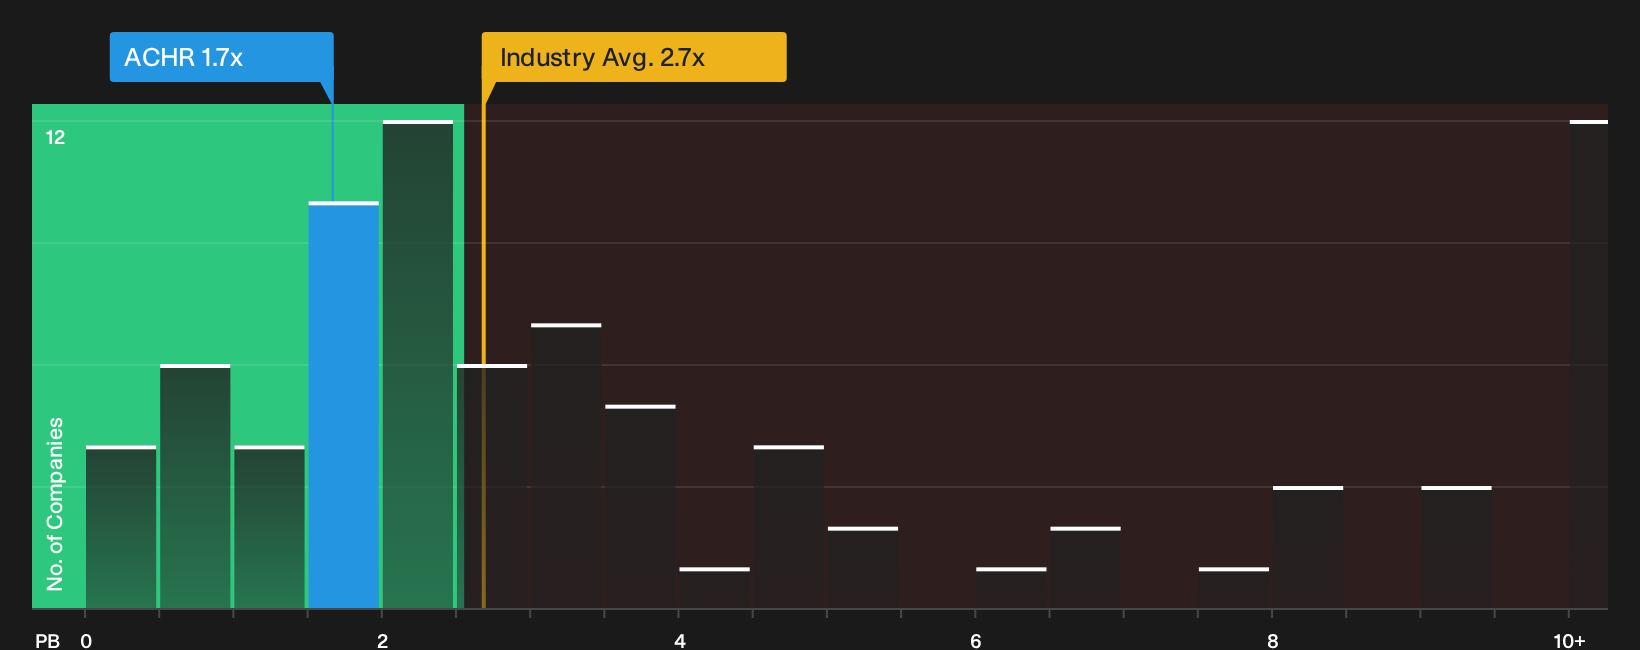
P/B suits Archer Aviation because the business is still loss making and its balance sheet gives you a clearer anchor than earnings. On this measure, the stock trades around 1.7x book value, which is slightly below the Aerospace & Defense industry average of about 2.7x and almost in line with the peer group near 1.7x. That points to Archer changing hands at a discount to the broader sector on asset value, while being priced similarly to closer listed comparables that investors might also be tracking.
Because the recent Boeing linked deal involves issuing shares for established aviation assets, the P/B gap to the wider industry matters more than usual. The current multiple suggests the market is not pricing Archer Aviation as richly as many Aerospace & Defense stocks relative to their equity base, even after concerns around dilution and cash burn that were flagged over the past year. For anyone weighing whether that pricing is justified, the next step is to compare this P/B level with the quality, liquidity and potential earnings power of the assets backing each share. Explore the numbers behind Archer Aviation's P/B valuation.
The Archer Aviation Narrative: What Would Justify Today's Price?
Narratives pick up where Archer Aviation's valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the shares to look meaningfully higher or lower than they do today. They sit on Simply Wall St's Community page so you can see those conditions set out in plain language. Each narrative lays out the drivers behind its view of fair worth rather than just a single multiple or model output, so you can compare those inputs with Archer Aviation's reported numbers as they arrive.
One of the top community narratives on Archer Aviation: 80% undervalued
"Archer's recent Q1 2026 results and strategic moves fundamentally upgrade the investment thesis from a pure 'air taxi operator' to a diversified aerospace platform..."
Discover why this Narrative puts Archer Aviation at 80% undervalued.
One more thing about Archer Aviation that deserves your attention
Valuation only tells part of the Archer Aviation story, because separate checks on the business have flagged specific areas of concern that thoughtful shareholders usually want to inspect closely before committing fresh capital. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com