


Colgate-Palmolive (CL) Rebounds Following Pullback As Fair Value Debate Tightens
Colgate-Palmolive stock triggered by recent performance shift
Colgate-Palmolive (CL) is back on investor screens after a recent pullback over the past 3 months that follows gains over the past year and year to date.
The recent pullback looks more like a pause than a breakdown, with Colgate-Palmolive’s 7 day share price return of 6.39% and 30 day gain of 5.56% partly offsetting a softer 90 day move that is down 1.37%.
That near term rebound comes on top of a 19.42% year to date share price return and a 1 year total shareholder return of 22.50%. Taken together, these figures point to momentum that has been strong overall, even as expectations and perceived risk are being reset at the current US$92.78 level.
Compare Colgate-Palmolive’s recent run with a curated set of resilient consumer names by scanning the 32 resilient stocks with low risk scores that highlights companies with relatively lower risk profiles.
After that rebound and a share price of US$92.78, the debate tightens around Colgate-Palmolive. Is most of the easy upside already captured, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 7% Overvalued
Colgate-Palmolive’s most followed valuation story puts fair value at $86.48, which sits below the recent $92.78 share price and frames the current debate as a modest premium, according to rcb9.
The distortion runs through every derived metric. The dividend payout looks stretched at roughly 82% of GAAP EPS and is about 57% of Base Business EPS. The stock looks expensive at 35 times GAAP earnings and trades near 24 times normalised. The trailing twelve month margin carries the same contamination, because the fourth quarter of 2025 still sits inside the window.
See why 9 investors see Colgate-Palmolive as 7% overvalued.
Result: Fair Value of $86.48 (OVERVALUED)
Still, this Colgate-Palmolive narrative can crack if North American organic sales stay weak or if another skin health impairment emerges and reshapes earnings quality.
Find out about the key risks to this Colgate-Palmolive narrative.
Another view on Colgate-Palmolive’s value
While the rcb9 narrative lands on a fair value of $86.48 and calls Colgate-Palmolive 7% overvalued, the SWS DCF model points in the other direction. On that framework, the shares at $92.78 trade about 27.6% below an estimated future cash flow value of $128.18, which frames the same cash generation as a potential discount rather than a premium. Which lens feels more convincing to you: a multiple-driven story, or a cash flow model that leans heavily on long term assumptions?
Look into how the SWS DCF model arrives at its fair value.
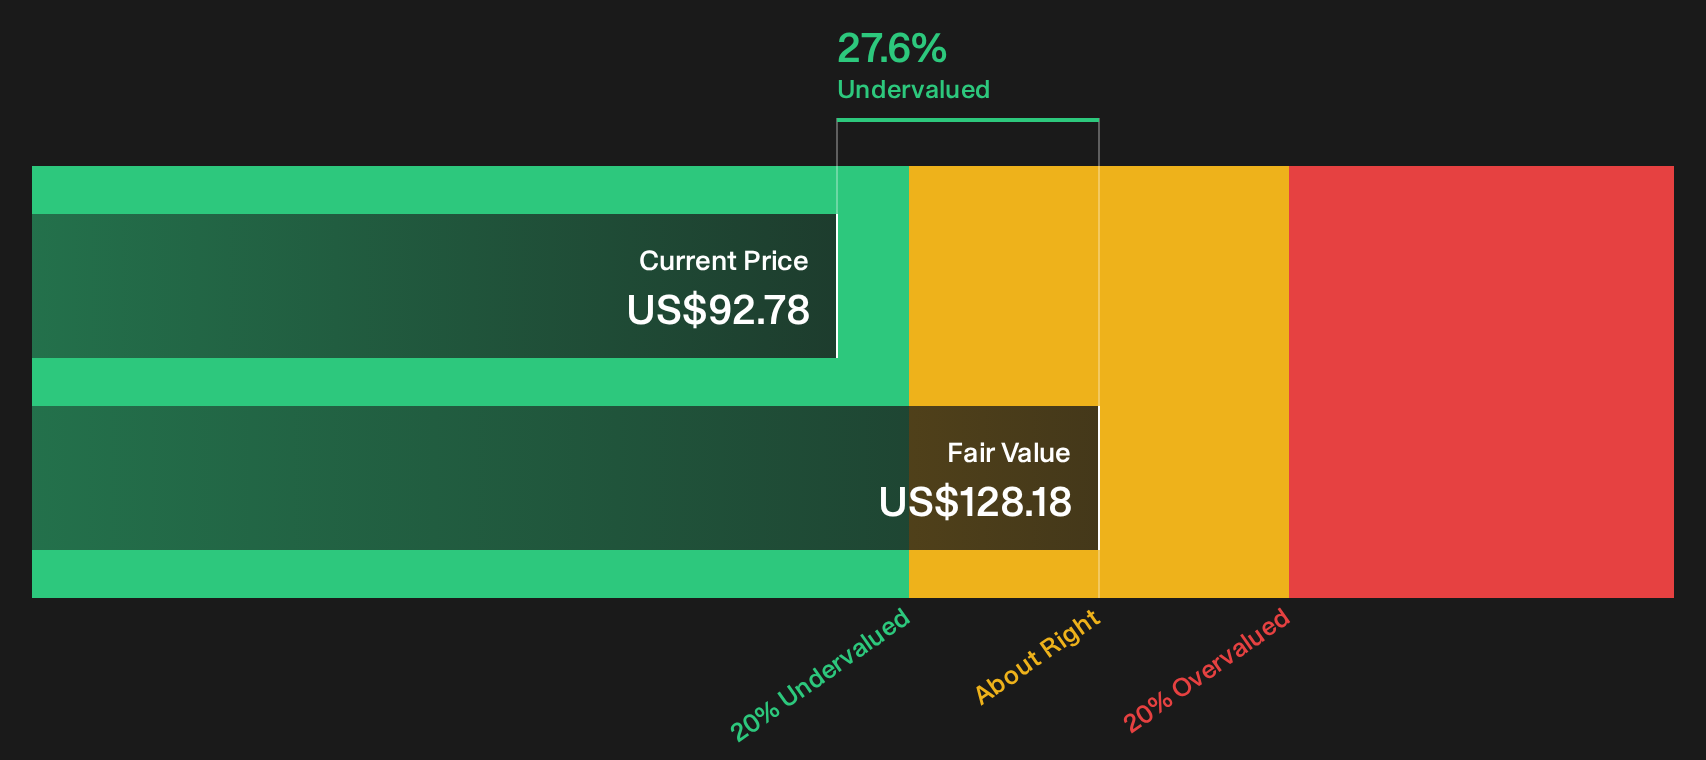
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Colgate-Palmolive story so far. If you want to move quickly and make up your own mind, start by weighing the 3 key rewards and 3 important warning signs.
Looking for more Colgate-Palmolive sized ideas?
Do not stop with Colgate-Palmolive. Use this momentum to widen your watchlist and pressure test your thesis against fresh, high quality ideas sourced directly from the Simply Wall Street Screener.
- Target quality at a discount by scanning a focused set of companies that currently look attractively priced using the 32 high quality undervalued stocks.
- Build a sturdier core to your portfolio by filtering for businesses with strong finances and durable fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed opportunities by checking the 20 high quality undiscovered gems before everyone else starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com