


Realty Income (O) Could Be 11% Undervalued Following Raised 2026 AFFO Guidance
Realty Income (O) affirmed another monthly dividend, declaring a US$0.2715 per share payout, or US$3.258 annualized, payable on November 13, 2026, to investors on record as of October 30.
Realty Income’s latest dividend decision comes after a choppy stretch for the stock. The 30 day share price return is down 6.92%, while the past week shows a 7 day share price gain of 3.41% as some momentum returns.
Scan beyond Realty Income and line up other income-focused REITs by yield, balance sheet strength, and dividend track record with our curated 7 dividend fortresses today.
Realty Income’s shares have slipped over the past month even as management reaffirmed monthly payouts and lifted 2026 AFFO guidance. Is this pullback already offering a reasonable entry point, or does waiting still appear more attractive?
Most Popular Narrative: 11% Undervalued
Realty Income last closed at $55.17, while the most followed valuation narrative, according to andre_santos, centers on a fair value estimate of $62.11 that sits meaningfully higher than the current share price.
Realty Income is considered a standard in REITs. Having paid a monthly dividend over 32 years uninterrupted (starting in 1994), many investors who seek a source of dividend income have held a position or some kind of investment in this company over time.
The key metrics above for this type of business may not fully reflect its characteristics. The growth for a REIT company can be slow and overall gradual. However, the security and reliability its dividend payments offer can be difficult to find in other industries, partly because this type of business is required to return most, if not all, of its free cash flow in dividend payments to its shareholders.
See why 109 investors see Realty Income as 11% undervalued.
Result: Fair Value of $62.11 (UNDERVALUED)
Still, the Realty Income story can be knocked off course if funding costs stay elevated relative to its 7.11% estimated capital cost, or if share issuance keeps diluting holders.
Find out about the key risks to this Realty Income narrative.
Another View: Realty Income Through The P/E Lens
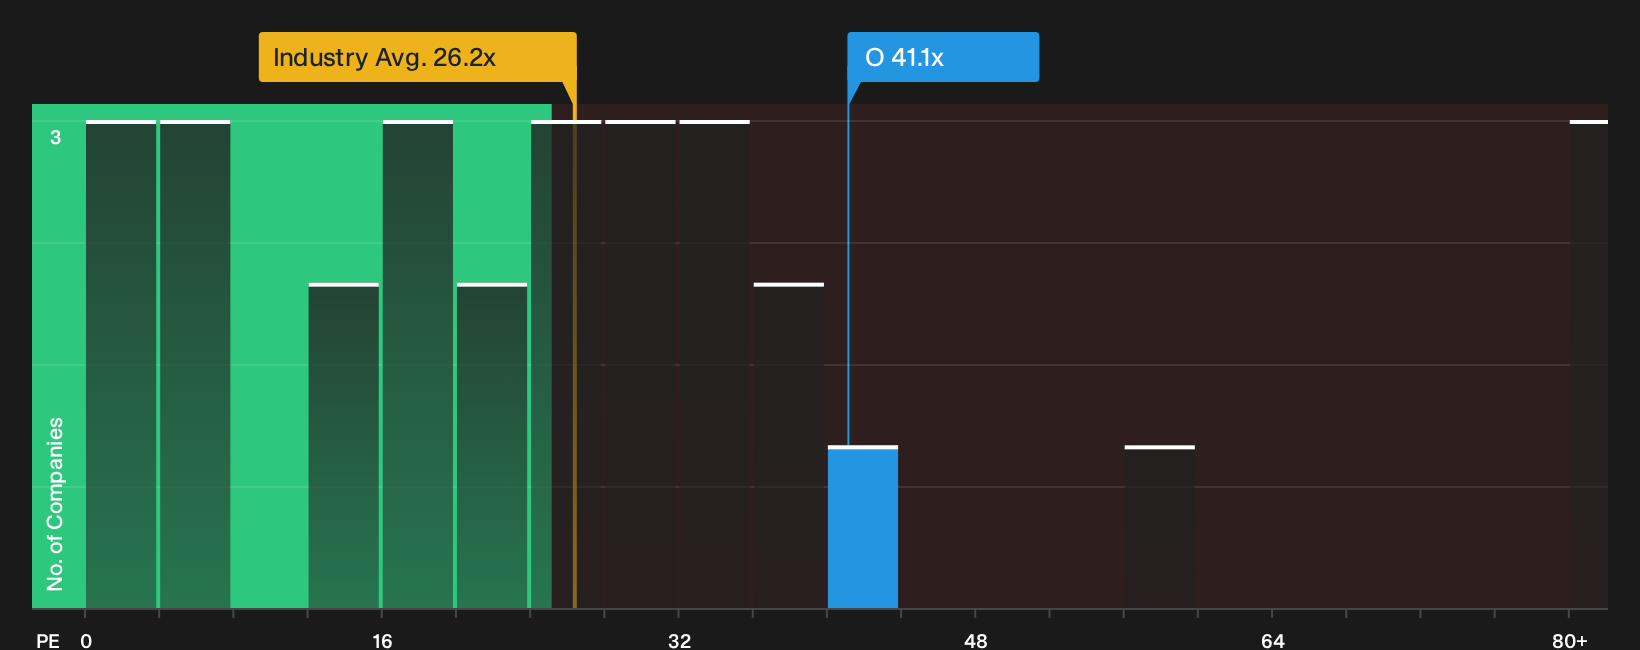
That 11% gap between Realty Income’s US$62.11 fair value narrative and the current US$55.17 price sounds appealing, but the earnings multiple tells a tougher story. The stock trades on a P/E of 41.1x, compared with a US Retail REITs industry average of 26.2x and a peer group around 25.5x.
The fair ratio for Realty Income is 35.2x, which is still rich but lower than where the market prices it today. For you as a shareholder, that spread means less margin for error. If sentiment shifts toward that fair ratio or closer to sector norms, how comfortable are you holding an income REIT at this kind of premium valuation?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Realty Income’s valuation and income appeal are clear, so move quickly, review the full picture, and weigh both sides with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Realty Income?
Do not stop with one REIT. Broaden your watchlist with a few focused stock lists that can surface different types of opportunities quickly and efficiently.
- Explore potential upside by scanning a curated group of 11 elite penny stocks with strong financials that already clear strict financial quality checks.
- Concentrate on value by reviewing a hand picked set of 32 high quality undervalued stocks that pair stronger balance sheets with attractive pricing.
- Manage your downside by focusing on 32 resilient stocks with low risk scores that carry lower risk scores yet still seek to put your capital to work.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com