


Is Boot Barn Holdings (BOOT) Cheap After Its 27% Three Month Slide?
Boot Barn Holdings (BOOT) has drawn investor attention after recent trading left the share price at $112.86. The retailer’s pullback over the past month and past 3 months now sits against solid reported annual revenue and net income figures.
Recent trading paints a different picture. The share price is down 21% over the past month and 27% over the past quarter, contributing to a 40% decline in 1 year total shareholder return, even though 3 year total shareholder return is still positive.
Compare Boot Barn Holdings’ sharp pullback with other retailers under pressure and see which ones our screen has tagged as 32 high quality undervalued stocks.
Bulls see Boot Barn Holdings as a quality retailer temporarily knocked back by sentiment. Bears see a cyclical story losing steam. Which case do the current valuation markers support next?
Most Popular Narrative: 48% Undervalued
On the most followed view, Boot Barn Holdings carries a fair value of $217.00 compared with the recent $112.86 close, which puts the current pullback against a much higher long term earnings and margin story.
Continued capital-efficient store expansion, with 70 planned openings in fiscal 2027 after 17% unit growth in the prior year and a long-term path from 566 stores toward roughly 1,200 locations, gives Boot Barn Holdings a multiyear opportunity to add revenue and scale earnings as new units reach projected first year sales of about $3.2 million with sub two year paybacks.
See why 11 investors see Boot Barn Holdings as 48% undervalued.
Result: Fair Value of $217.00 (UNDERVALUED)
Still, the Boot Barn Holdings story can be knocked off course if aggressive store expansion dilutes returns, or if softer Western demand lingers and drags on sales.
Find out about the key risks to this Boot Barn Holdings narrative.
Another Angle On Boot Barn Holdings Valuation
Analyst targets frame Boot Barn Holdings as undervalued, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow view, the current $112.86 price sits above an estimated value of $52.02, which screens as overvalued. Which lens feels more convincing to you?
To see how those cash flow assumptions are built and stress test them against your own expectations, take a look at the Look into how the SWS DCF model arrives at its fair value..
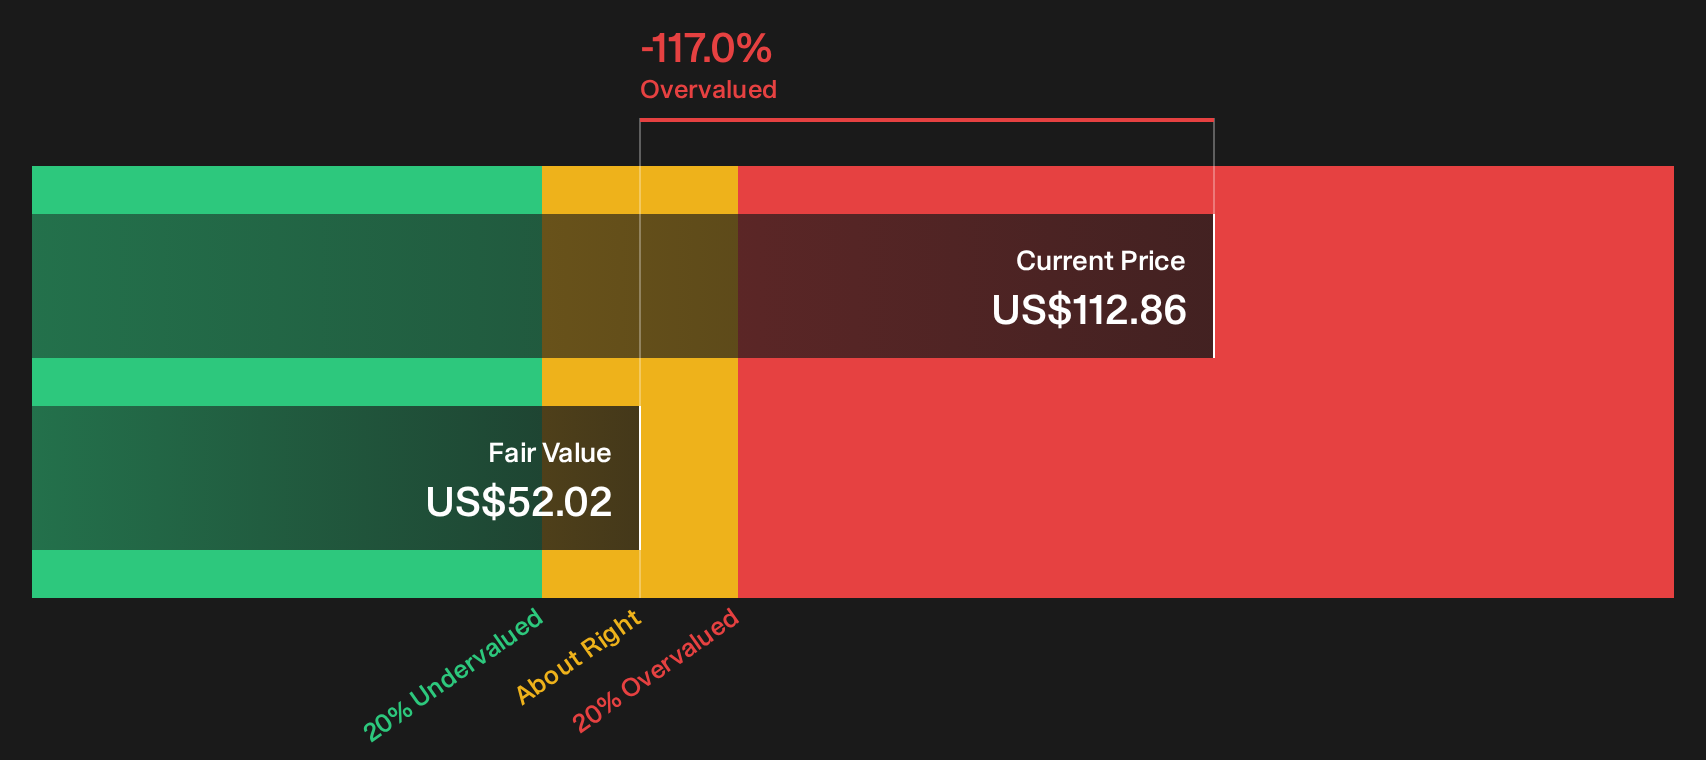
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boot Barn Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this Boot Barn Holdings story is clearly split, so treat this pullback as your prompt to review the data yourself and move fast. To see what has investors optimistic right now, check the 4 key rewards.
Looking for more Boot Barn Holdings style investment ideas?
If you stop your research with Boot Barn Holdings, you risk missing opportunities that better match your return goals, risk comfort, and time horizon.
- Target stronger balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities that combine quality and value by checking the 32 high quality undervalued stocks.
- Spot potential future outperformers before they are widely followed by reviewing the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com