


Barclays Analyst Resets Strategy Stock Price Target. How to Play MSTR Here.
Strategy (MSTR) is among the world's most volatile stocks, as it is often viewed as a Bitcoin (BTCUSD) proxy. Valued at a market capitalization of $58.4 billion, MSTR stock is down 54% from its 52-week high of $308.88. However, the stock has also returned more than 111% in the last five years.
Recently, one Wall Street analyst raised their price target on Strategy stock. Let’s take a closer look at why.
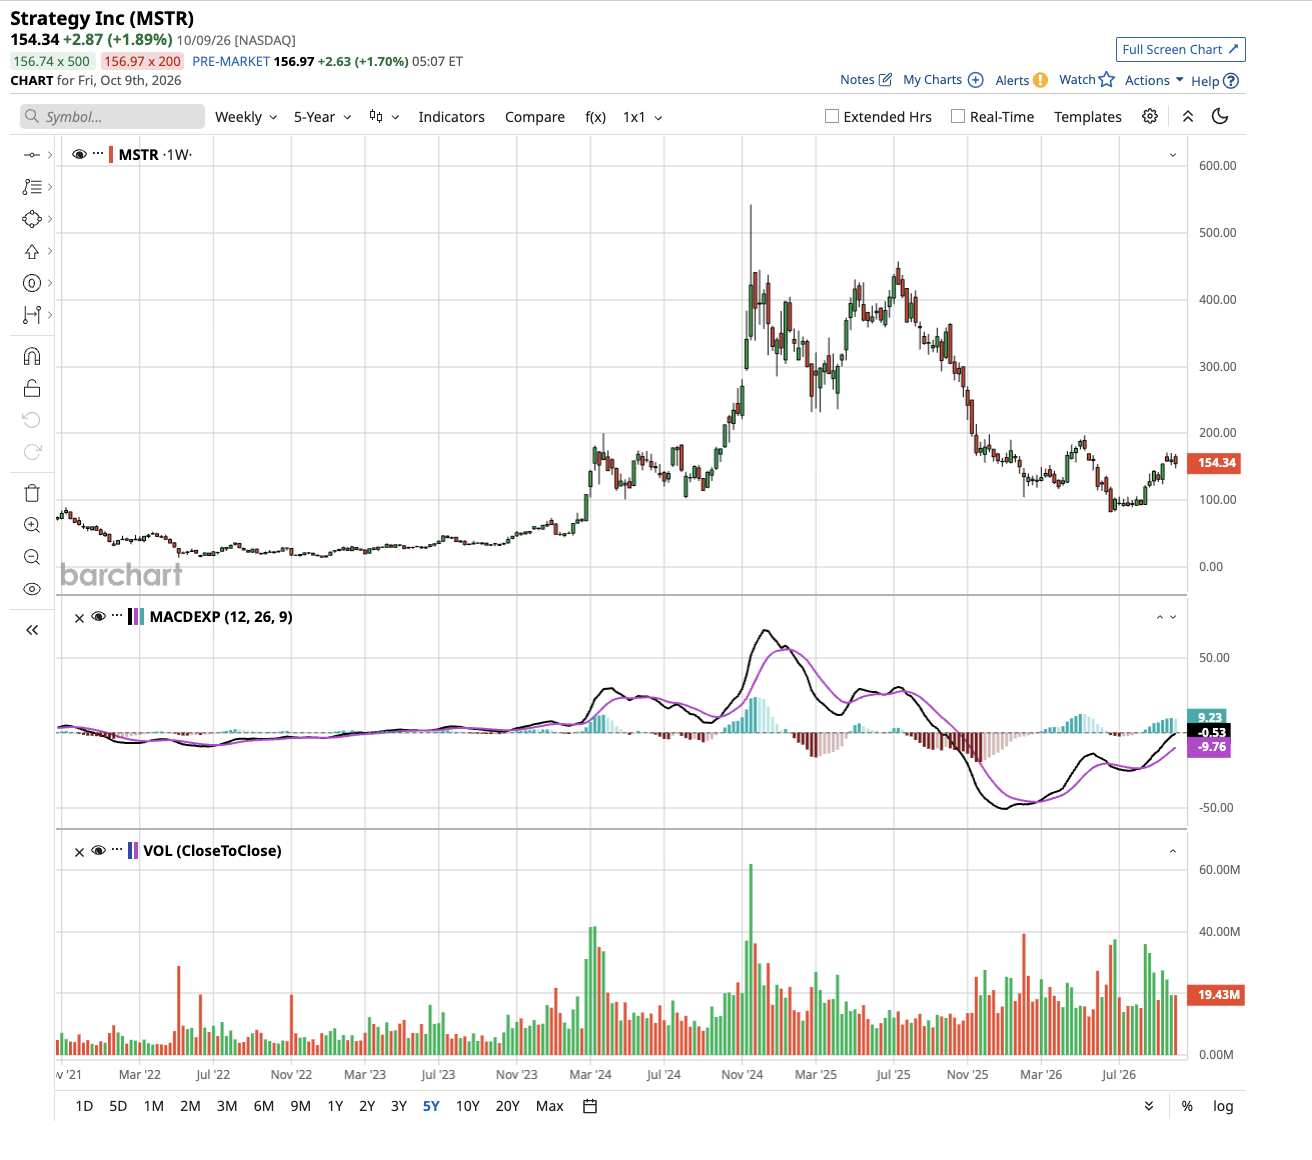
Why Strategy Stock Is Hard to Value
Let’s begin with what Strategy owns. According to its Oct. 4 investor briefing, the company now holds 848,000 BTC, or 4.04% of all Bitcoin that will ever exist.
At roughly $81,000 per coin, its total BTC stash is worth more than $68 billion, which is above Strategy's current market cap. Notably, common shareholders do not own all of the Bitcoin, given the company has significant debt and preferred stock on its balance sheet.
Bitcoin ended the second quarter with $5.91 billion in debt and $13.95 billion of preferred stock. Strategy subtracts that $19.86 billion it owes to debt and preferred-stock holders, then adds back $5.71 billion in dollar holdings, leaving $57.33 billion of net reserve for common shareholders.
Strategy also tracks a ratio called mNAV, which is the premium investors pay over the Bitcoin each share holds after those senior claims. The company presentation showed the ratio at 1.2 times, so MSTR stock trades about 20% above that value.
The structure magnifies MSTR stock moves in both directions. Using the investor briefing’s table and a starting Bitcoin price of $84,289, BTC at $50,000 would cut net reserve per share by roughly 51%, even though the digital asset falls about 41%. At $100,000, net reserve per share rises about 23% on a roughly 19% gain for the crypto. That is the amplification investors sign up for.
Barclays Lifts Its Price Target to $175
On Oct. 9, Barclays analyst Nik Cremo kept an “Overweight” rating on MSTR stock and raised his 12-month price target to $175 from $160. Currently, Strategy stock trades at roughly $143 per share.
Barclays started coverage of Strategy on July 8 with a $130 price target. After the company posted Q2 results, the firm trimmed its target to $125 per share. Since then, though, it has raised its target twice, with the new target of $175 sitting 40% above that post-earnings low target.
Meanwhile, Citi has a target price of $240 for MSTR stock, while B. Riley has a price target of $195 per share.
Is MSTR Stock a Good Buy?
On Aug. 17, Strategy CEO Phong Le said during the company's investor Q&A session that Strategy wants to be "the JPMorgan (JPM) of digital assets." The company is also building products on top of its Bitcoin. Executive Chairman Michael Saylor said in the same Q&A that the real product is digital credit. He wants it to grow from roughly $15 billion today to more than $100 billion over time.
Strategy reported Q2 revenue of $122.4 million, up almost 7% from a year earlier. Subscription services revenue rose 54% to $62.9 million. Still, that revenue is marginal next to the company's BTC pile.
Crypto Briefing notes that net results swing with unrealized moves in Bitcoin's value. The company must also cover $1.58 billion a year in interest and preferred dividends. Cash and reserves cover a little less than four years of that bill.
Strategy says its current cost of credit is 10.63%. So, Bitcoin has to beat that rate over time for common shareholders to come out ahead. Saylor told investors to be ready for a difficult year or two, given BTC prices are down more than 30% from all-time highs.
My Take on the $175 Strategy Stock Target
In my view, the Barclays target raise is a vote of patience. Another raised price target following the post-Q2 price target cut tells me confidence is rebuilding.
However, owning MSTR stock remains risky. If you hold shares of Strategy, the fintech label matters less than three numbers that tell you something different about the underlying risk: Bitcoin's price, the 1.2 times mNAV ratio, and the 10.63% cost of credit.
First, there's Bitcoin’s price. Strategy’s investor briefing shows what happens to net reserve per share as BTC moves. At $84,289, it is $132.89 per share. At $50,000, it drops to $65.49 per share.
Then there's the 1.2 times premium. This is the extra amount investors pay above that $132.89. On Oct. 2, MSTR stock traded at $160 per share, a 20% premium. For context, the Barclays target of $175 would need a premium of roughly 1.32 times at that same Bitcoin price. This shows the target needs either a higher BTC price, a larger premium, or a mix of both.
Finally, the 10.63% hurdle points to Strategy’s current cost of credit. Bitcoin has to earn more than that over time for common shareholders to benefit from the debt and preferred stock the company sells. For every $1 billion of credit, Bitcoin returning 10% leaves a small annual loss of $6 million. At 15%, the gain is $44 million and at 20%, it is $94 million. The company also pays $1.58 billion a year in interest and dividends, regardless of how Bitcoin performs.
With all that in mind, I would ask a simple question before buying MSTR stock: Can you sit through a 50% drop?
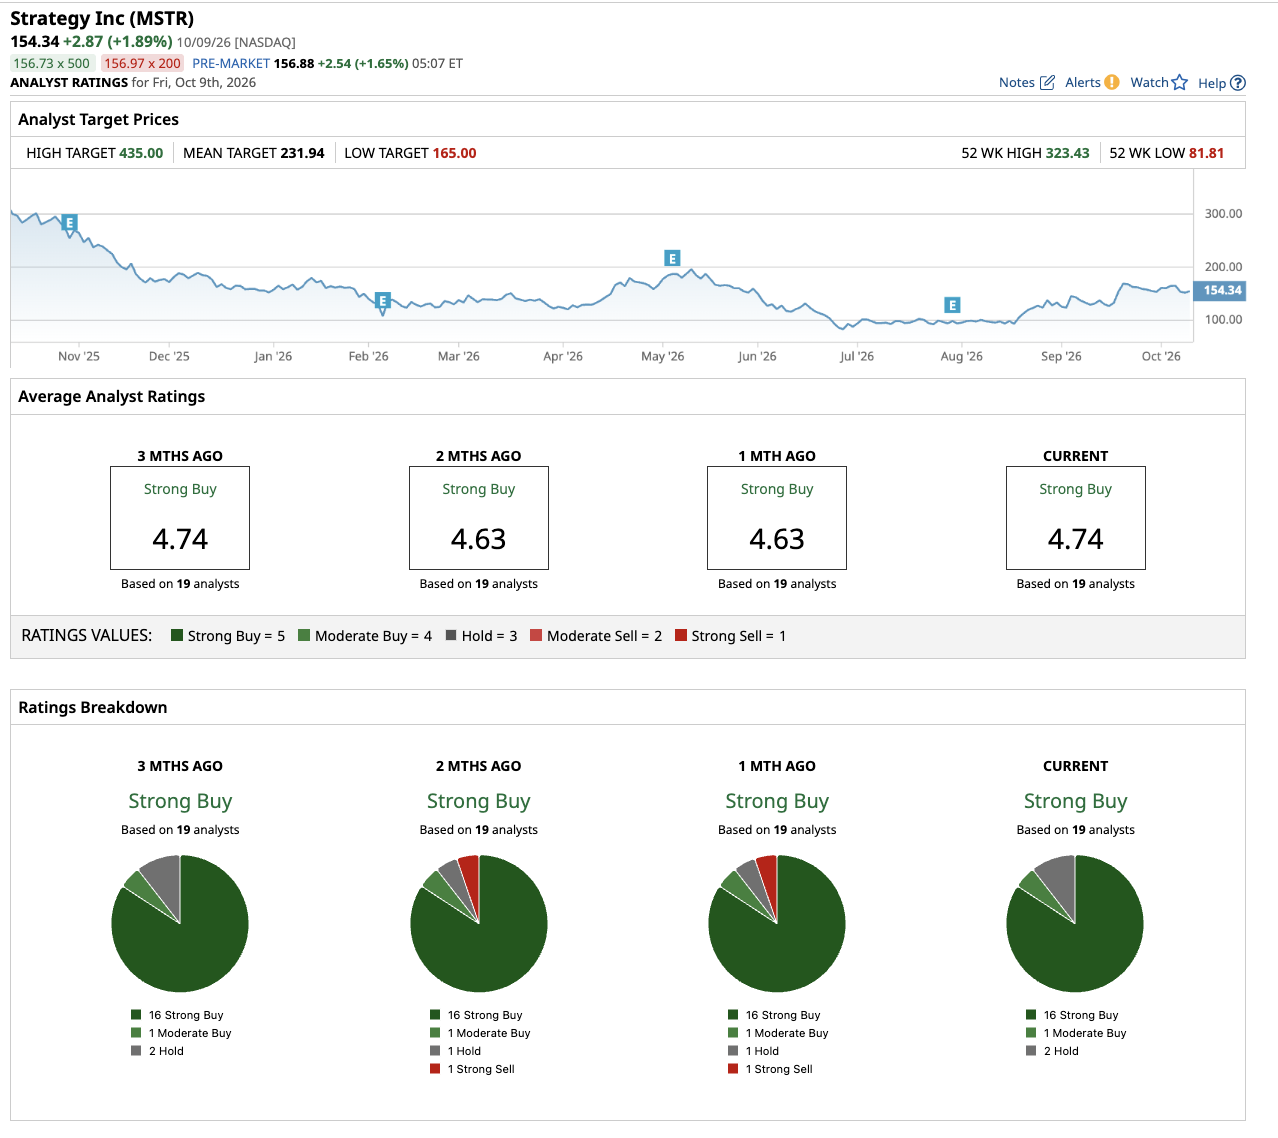
Overall, MSTR stock has a consensus “Strong Buy” rating. Of the 19 analysts covering Strategy stock, 16 recommend a “Strong Buy” rating, one recommends a “Moderate Buy,” and two recommend a “Hold” rating. The average price target of $231.94 represents potential upside of 62% from current levels.
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.