


How Raised Guidance Will Impact OSG Stock Investors
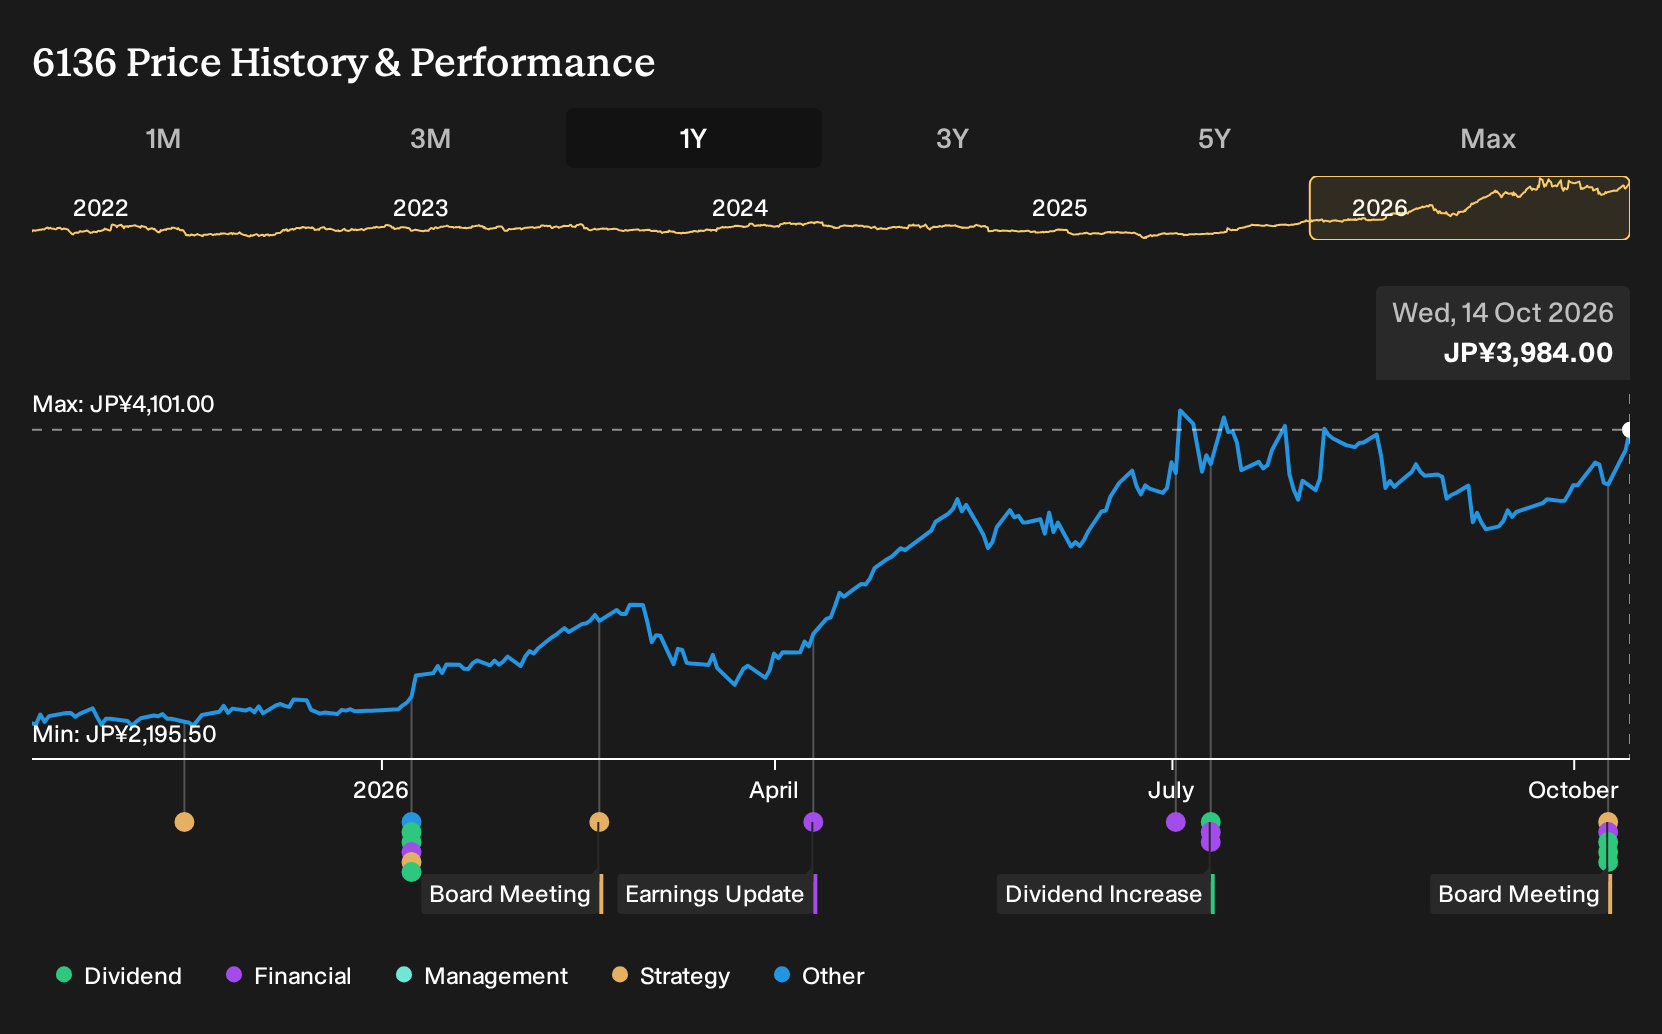
- OSG Corporation approved a share repurchase program of up to 1,500,000 shares for ¥5,000 million and raised full year earnings and dividend guidance after a board meeting on October 9, 2026.
- The company links its higher profit forecast and a sharply higher planned year end dividend of ¥91 per share to firm demand across aerospace, electronics, semiconductors, energy, and medical sectors, as well as operational gains in exports, plant utilization, raw materials, and tariff refunds.
- Attention now turns to how OSG Corporation's higher earnings and dividend outlook may reshape its investment narrative and risk reward profile.
Scan opportunities around OSG's upgraded outlook by reviewing our hand picked list of 15 high quality undervalued stocks that also pair stronger earnings profiles with disciplined capital returns.
What Is OSG's Investment Narrative?
To own OSG, you need to be comfortable with a fairly cyclical industrial tools business that depends on execution, global demand, and disciplined use of cash. The raised full year guidance ties the story to resilient orders in aerospace, electronics, semiconductors, data centers, energy, and medical, along with tangible operational wins around exports, plant utilization, raw materials, and tariff refunds. The fresh ¥5,000 million buyback, covering up to 1,500,000 shares, and the higher dividend outlook indicate that management currently sees sufficient earnings power and balance sheet flexibility to return capital while still funding a capital intensive manufacturing base.
In the short term, the key catalyst is whether this stronger order and margin backdrop can carry through the coming quarters, given prior forecasts that pointed to earnings declining on a multi year view. The repurchase program running to November 30, 2026 may support per share metrics, although by size it is incremental rather than transformative at 1.8% of outstanding equity. Risks remain around demand normalization after a strong year, exposure to raw material pricing shifts, and a historically uneven dividend pattern, so the real test for OSG is whether this upgraded guidance becomes a pattern or proves more one off in nature.
That said, the picture looks less straightforward once you consider ...
There's only one way to know the right time to buy, sell or hold OSG. Head to Simply Wall St's company report for the latest analysis of OSG's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OSG research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for OSG. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSG's overall financial health at a glance.
Looking For More Ideas Beyond OSG?
If you want to stress test your view on OSG against what else is out there, the Simply Wall St Screener can help you line up alternatives with similar traits or very different profiles.
- If you care most about quality at a reasonable entry point, compare OSG with a wider set of candidates that screen as 15 high quality undervalued stocks based on both strong fundamentals and pricing.
- For readers who prioritize resilience and capital strength, use the screener to focus on a list of solid balance sheet and fundamentals (21 results) that can better withstand tougher conditions.
- Income focused investors can broaden their watchlist by hunting for 28 dividend fortresses that combine higher yields with disciplined payout habits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com