


Should Uncrustables Expansion Require Action From Smucker Stock Investors?
- J. M. Smucker reported strong momentum in its Uncrustables line in Q1 FY27, with 12% net sales growth, record quarterly sales and volume, and higher household penetration, supported by plans to accelerate the second phase of its McCalla, Alabama production facility.
- The decision to speed up added Uncrustables manufacturing capacity highlights how demand visibility and brand traction are shaping J. M. Smucker's capital allocation and operational planning.
- We will now look at how J. M. Smucker's investment narrative could be influenced by accelerating Uncrustables growth and added production capacity.
Scan beyond J. M. Smucker and compare this kind of branded food momentum with a curated 20 high quality undiscovered gems that may be quietly building similar consumer traction.
J. M. Smucker Investment Narrative Recap
To own J. M. Smucker, you need to believe its core brands like Uncrustables, Café Bustelo and Meow Mix can offset pressure in U.S. Retail Coffee and Sweet Baked Snacks while supporting steady free cash flow. The Uncrustables strength in Q1 FY27 helps that case, although management still expects FY27 net sales to fall 1% to 2%.
The key near term swing factor is whether growth brands scale fast enough to cover weaker Hostess and coffee trends, while cost inflation outside green coffee stays manageable. The main risk remains execution in Sweet Baked Snacks and any shortfall in productivity actions needed to protect margins from higher freight and commodity costs.
The most relevant development to this recent Uncrustables update is Smucker’s decision to accelerate the second phase of its McCalla, Alabama facility. That step raises available frozen handheld capacity and aligns with record Uncrustables sales, volume and household penetration in Q1 FY27. This tightens the link between capital spending and visible demand.
For you as an investor, the question is whether J. M. Smucker can fill that extra capacity at attractive economics while managing softer company wide net sales guidance and cost inflation outside green coffee. Execution on ramping McCalla, plus maintaining strong Café Bustelo and Meow Mix trends, now sits at the center of the earnings catalyst story.
J. M. Smucker's current analyst narrative points to revenues of US$9.1b and earnings of US$1.0b by 2029, with revenue expected to remain fairly flat and profit climbing from US$229.5m today. This implies an earnings increase of roughly US$770m over that period.
Uncover why J. M. Smucker's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
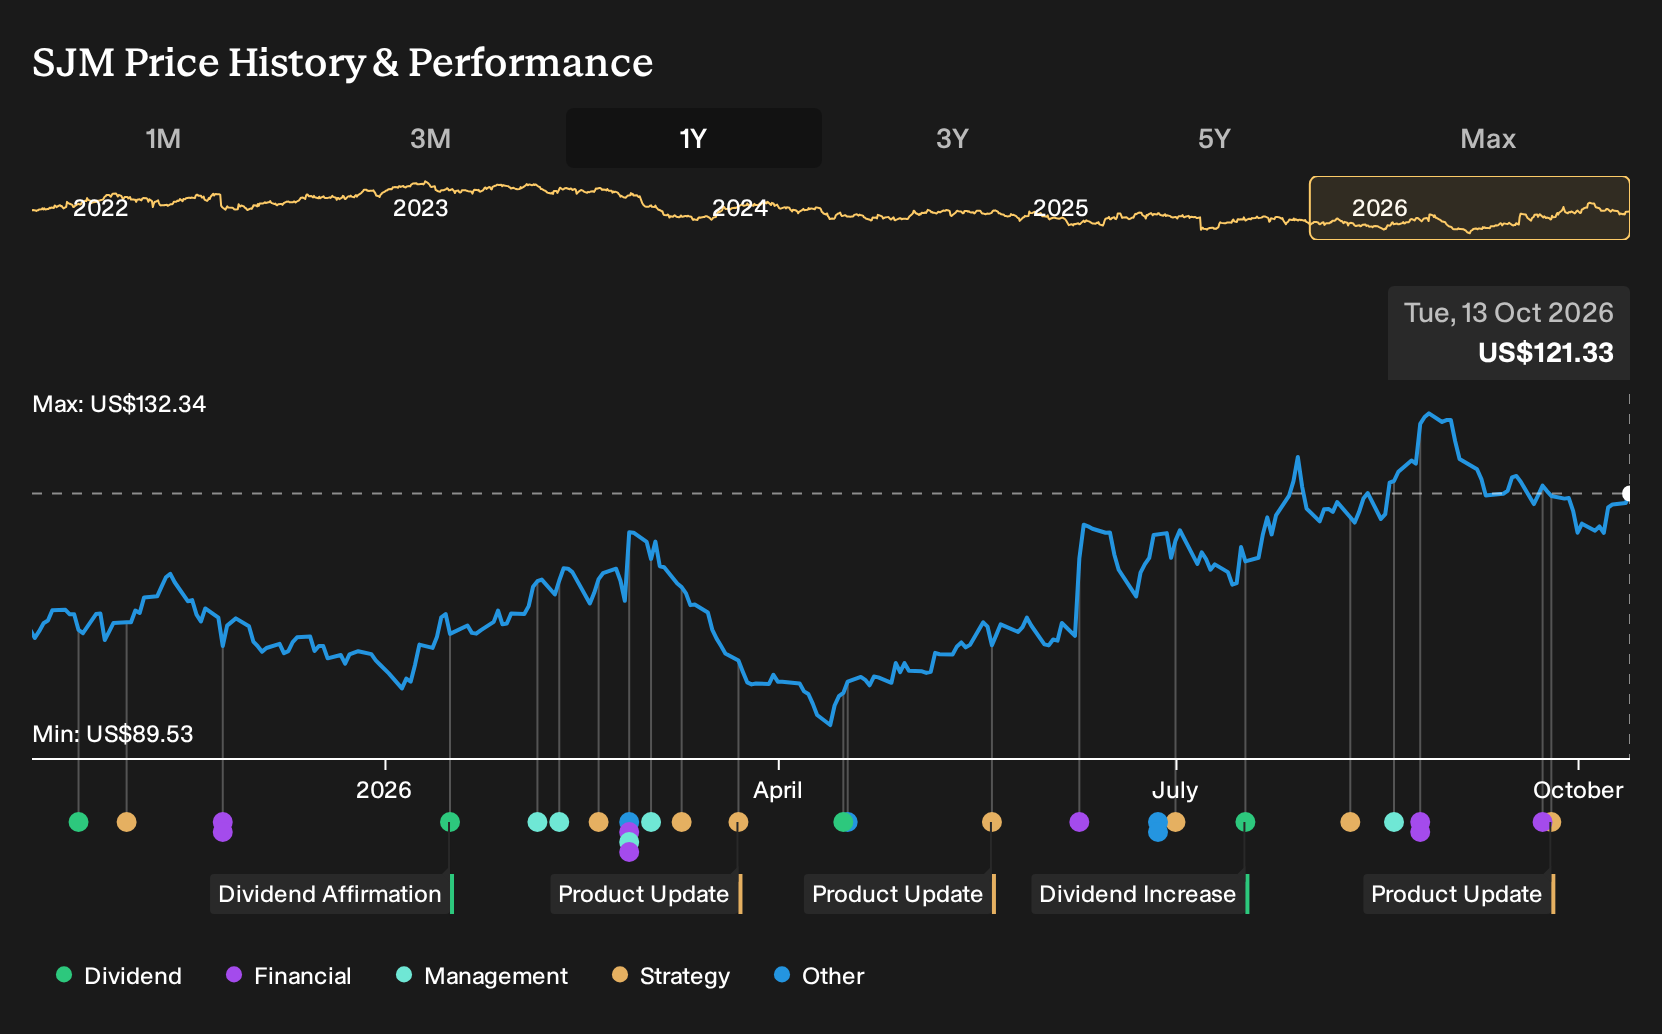
Exploring Other Perspectives
You might see the Uncrustables capacity ramp as a clear win for J. M. Smucker, yet the lowest analysts lean into a different angle. They focus on pressure from higher input costs and capacity spend, and were previously modeling revenue drifting toward about US$8.7b by 2029 with a 1.8% annual decline. That is more cautious than the consensus view of roughly US$9.1b and instead assumes limited benefit from today’s news so far. Opinions span a wide range. Treat this as a prompt to compare several scenarios yourself, then decide which version of the story you find most convincing.
Explore 2 other J. M. Smucker fair value estimates, including one that suggests it could be worth just $142.12.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your J. M. Smucker research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for J. M. Smucker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. M. Smucker's overall financial health at a glance.
Looking for more J. M. Smucker sized investment ideas?
If the J. M. Smucker story has you thinking more broadly about branded cash generators, income plays, or durable balance sheets, it can be useful to cast the net wider using the Simply Wall St Screener.
- For investors who want resilient businesses at appealing prices, scan a curated set of 32 high quality undervalued stocks that may pair solid fundamentals with room for sentiment to improve.
- If portfolio stability matters more to you than excitement, focus on companies in the 32 resilient stocks with low risk scores that score well on balance sheet strength and earnings consistency.
- For those hunting for quality beyond the usual tickers, widen your research with a hand picked pool of 20 high quality undiscovered gems that might be flying under the radar despite strong financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com