


Is Motorola Solutions (MSI) Undervalued On Its Public Safety Demand Narrative?
Motorola Solutions (MSI) is back in focus after fresh data highlighted its mission critical communications and video security footprint for public safety and enterprise clients, prompting investors to revisit the stock’s recent performance.
Recent trading has been choppy. Motorola Solutions shares are up 10.27% over the past 90 days and the year to date share price return is 17.84%. However, the 1-year total shareholder return is slightly down 1.39%, hinting that momentum has cooled after a strong multi year run that produced a 59.96% total shareholder return over three years and 94.26% over five years.
Scan beyond Motorola Solutions and line up other mission critical and security focused players using our hand picked 32 resilient stocks with low risk scores for comparison.
After that strong multi year run yet slightly softer 1 year outcome, the question for Motorola Solutions now is whether the current valuation still tilts the risk reward in buyers’ favour.
Most Popular Narrative: 15% Undervalued
On the widely followed view, Motorola Solutions carries a fair value of about $526.82 against a last close of $449.01. This implies investors are weighing a premium setup supported by recurring software, government contracts and defense exposure.
The accelerating focus on public safety and security, supported by strong technology budgets, record orders and an 11% year over year backlog increase to US$15.6b, continues to point to sustained demand for Motorola Solutions communication and software platforms that can support revenue and earnings over multiple years.
See why 32 investors see Motorola Solutions as 15% undervalued.
Result: Fair Value of $526.82 (UNDERVALUED)
Still, the bullish Motorola Solutions story can crack if government technology budgets slow, or if newer areas like Silvus and D Fend deliver less revenue than analysts expect.
Find out about the key risks to this Motorola Solutions narrative.
Another View On Motorola Solutions Valuation
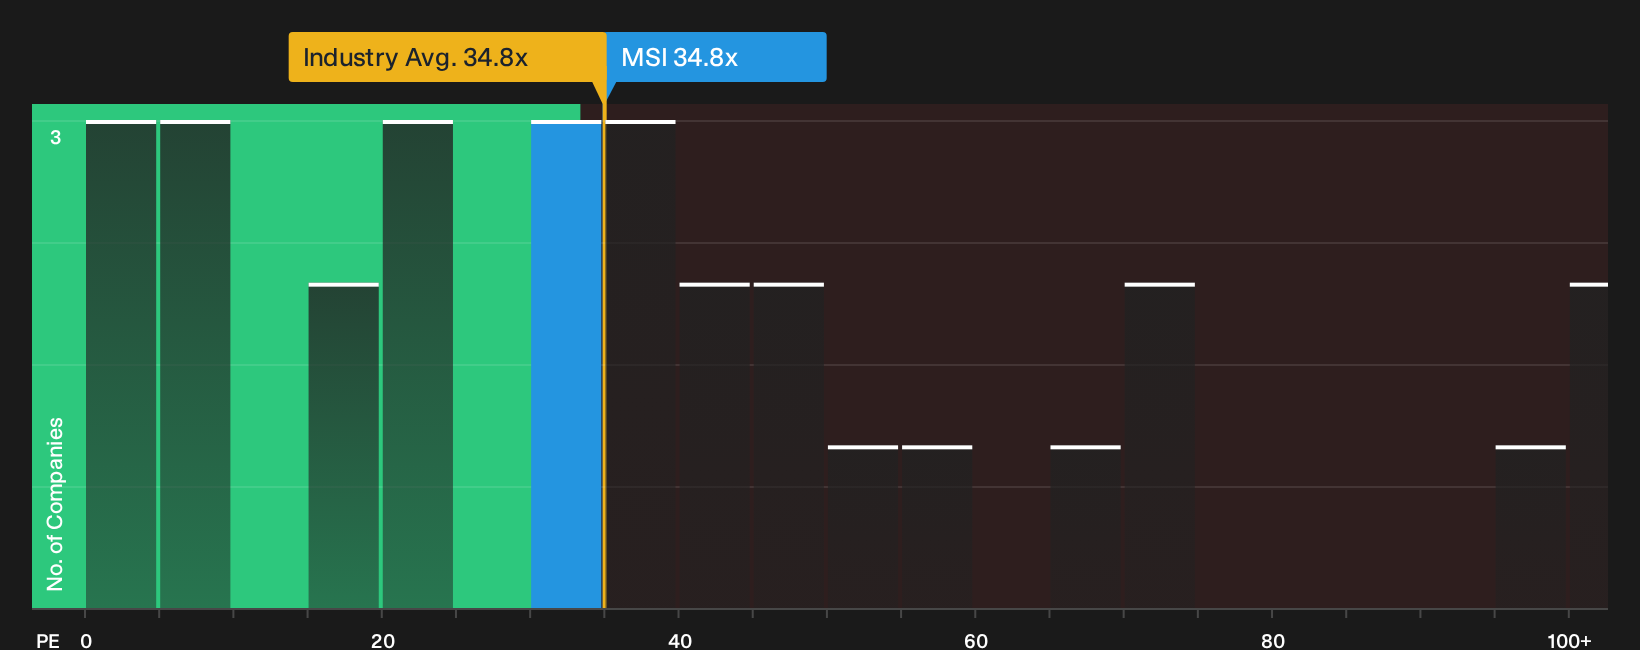
That bullish fair value of $526.82 leans heavily on analyst forecasts and narrative assumptions. A simpler check looks at the current P/E of 34.8x versus a fair ratio of 26.3x, which points to Motorola Solutions trading on a richer multiple that could limit upside from here. So which signal should investors weigh more carefully: the story or the sticker price?
For a closer look at what this P/E gap might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Motorola Solutions valuation often create the real opportunity, so move quickly, review the underlying data, and weigh both sides of the story with the detailed breakdown of 2 key rewards and 2 important warning signs
Looking for more Motorola Solutions investment ideas?
If Motorola Solutions has sharpened your focus, do not stop here. Broaden your watchlist with fresh ideas built from data driven stock screens.
- Target potential mispricing by lining up candidates using our broad 32 high quality undervalued stocks tailored for balance sheet strength and cash flow quality.
- Strengthen your downside protection by filtering companies through the list of solid balance sheet and fundamentals (25 results) that prioritises financial resilience and durable fundamentals.
- Get ahead of the crowd by scanning under followed opportunities in the 20 high quality undiscovered gems before they sit firmly on everyone else’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com