


Dividend Raises Could Be A Game Changer For W. P. Carey Stock (WPC)
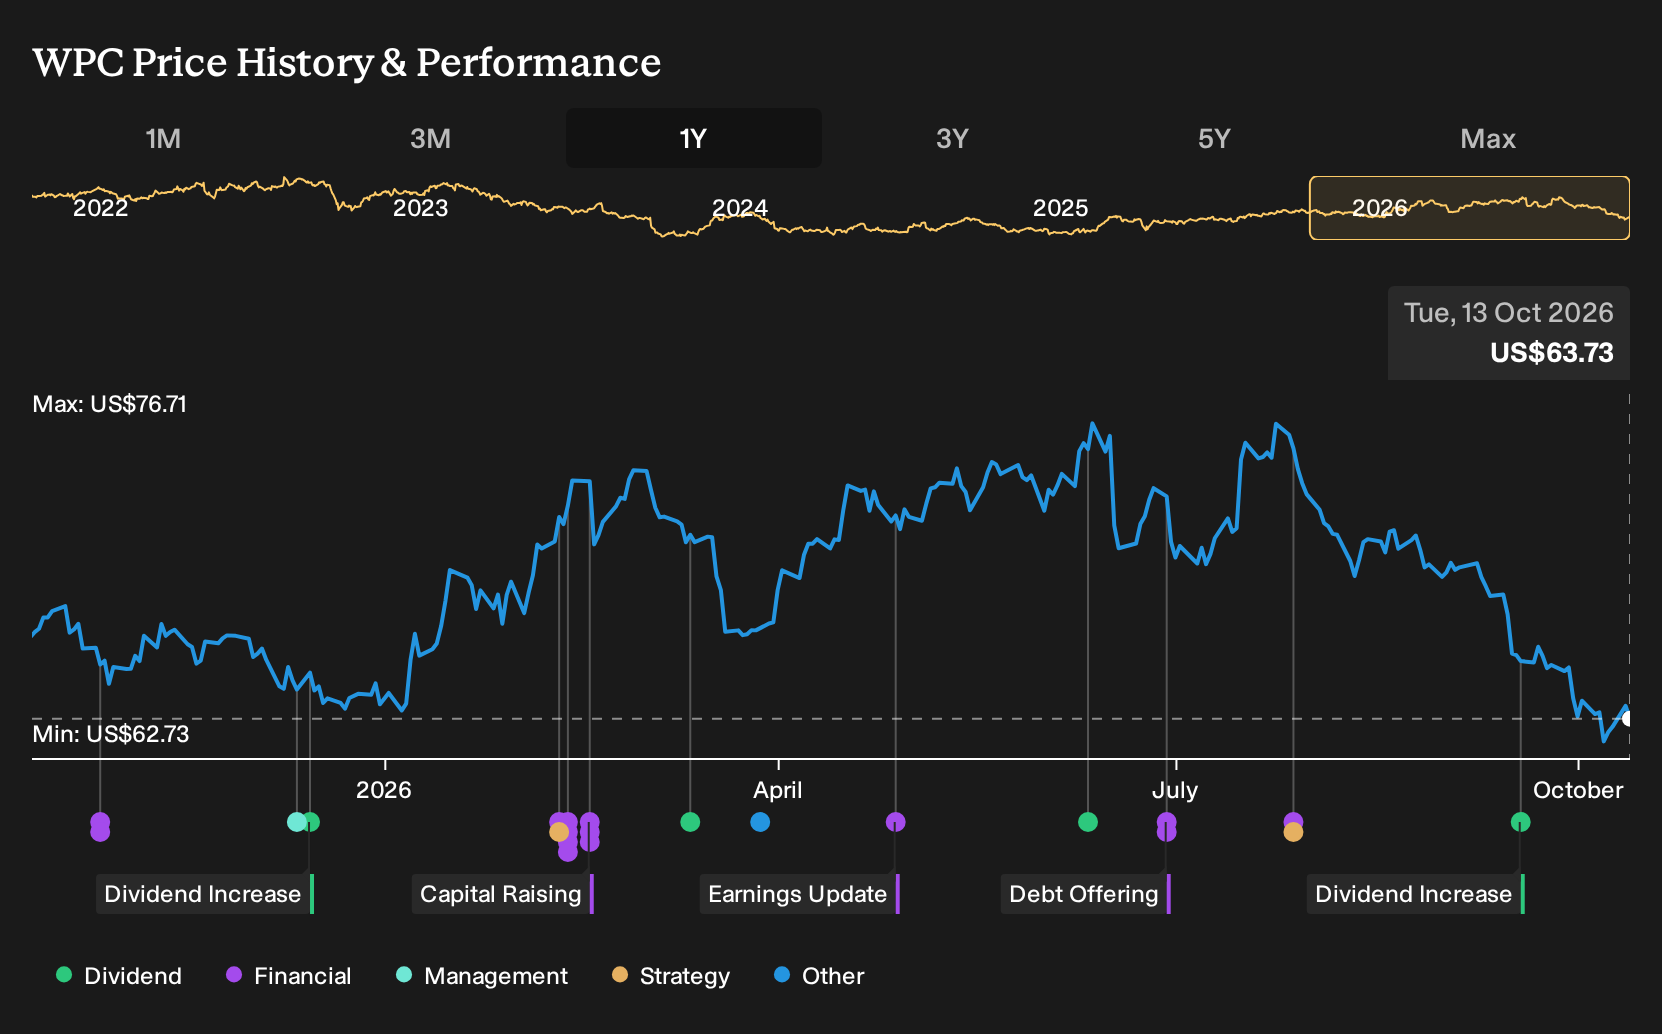
- W. P. Carey currently offers a 6.0% dividend yield, with its fiscal 2025 payout ratio at 73%, and it raised its quarterly dividend three times in 2026 while keeping net debt lower than peer Crown Castle.
- This mix of repeated dividend raises, a payout ratio below 100%, and comparatively lower leverage signals that W. P. Carey is prioritising dividend sustainability over more aggressive balance sheet risk.
- Now the focus shifts to how W. P. Carey's 6.0% yield and 73% payout ratio influence the earlier investment narrative around AFFO growth.
Scan beyond W. P. Carey and compare its income profile with hand-picked 8 dividend fortresses that also combine sizeable yields with a focus on balance sheet strength.
W. P. Carey Investment Narrative Recap
To own W. P. Carey, you need to believe its model of long term, single tenant net leases can keep supporting steady AFFO while tenant concentration and credit quality stay manageable. The big near term swing factor is execution on the current investment pipeline, without taking on meaningfully higher funding costs that would squeeze spreads.
The main operational risk remains a cluster of tenant issues in sub investment grade leases that hits rent collection and occupancy at the same time. The latest dividend coverage metrics and lower leverage compared with Crown Castle do not materially change that key risk, although they give the company more flexibility to handle setbacks.
Among recent developments, the most relevant is W. P. Carey’s use of pre funded capital, including roughly €1.0b of eurobonds, a C$ term loan, US$350m of notes and about US$900m of forward equity. That pool underpins guidance for US$1.7b to US$2.1b of net lease investments at a 7.4% initial cash cap rate.
This funding approach ties directly into the dividend story you are reacting to. If W. P. Carey keeps placing this capital into long lease industrial, warehouse and retail assets while maintaining occupancy around 98% to 99% and rent loss assumptions of US$7m to US$10m, it supports the current income profile but also keeps execution risk firmly in focus.
W. P. Carey’s current analyst narrative points to forecast revenue of US$2.2b and projected earnings of US$811.8m by 2029, based on assumed annual revenue growth of 7.1% and an earnings increase of about US$160.8m from US$651.0m today.
Uncover why W. P. Carey's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$78 to US$170 per W. P. Carey share, so opinions already stretch from deep discount to rich pricing. Those views were formed before the latest funding and tenant updates. Revisit them as you weigh lease concentration risk against the current dividend profile.
Explore 2 other W. P. Carey fair value estimates, including one that suggests as much as 166% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your W. P. Carey research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for W. P. Carey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate W. P. Carey's overall financial health at a glance.
Looking For More Ideas Beyond W. P. Carey?
If the W. P. Carey income story has sharpened your focus on yield, balance sheets and valuation, you can broaden that same framework across a wider watchlist using the Simply Wall St Screener.
- Seek out income opportunities with stronger financial cushions by filtering for companies that appear in our list of solid balance sheet and fundamentals (25 results) and may better match your risk appetite.
- Hunt for potential value setups by scanning through 32 high quality undervalued stocks that combine fundamentals with pricing that may appeal to long term investors.
- If you prefer to keep drawdowns on a tighter leash, narrow your research to 32 resilient stocks with low risk scores that align more closely with a capital preservation mindset.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com