


American Express (AXP) Stock Looks Undervalued As Its 108% Run Continues
American Express has delivered strong share price gains over the past three years. The more pressing issue for investors is whether that climb is actually backed by the returns the business earns on its capital. With fresh headlines around compliance penalties and new AI driven products, the question is how well the current valuation lines up with the underlying economics of the card and payments franchise.
- Over the past 3 years, American Express has returned 107.6%. This puts real weight on the question of whether the returns it earns on capital can support that kind of share price outcome.
- The recent US$350 million fine and required upgrade to anti money laundering controls may affect how management allocates capital between compliance investments and other growth plans. This matters for the returns the firm can continue to earn on its capital base.
- Prefer to judge American Express on earnings? See why American Express's 18.5x P/E tells a different valuation story.
The issue now is whether the returns American Express earns on its capital are strong enough and durable enough to justify where the stock trades today.
To put American Express in context on this theme of returns on capital and AI driven payments, it helps to compare it with other 92 AI infrastructure stocks.
Is American Express a Bargain on Excess Returns?
The Excess Returns model focuses on how much profit American Express earns above the return that investors typically require on its equity. For this stock, the analysis leans heavily on the strength of its profitability relative to its accounting capital base.
Book Value sits at $50.79 per share, while the Stable Book Value estimate is $59.67 per share. In comparison, Stable EPS of $21.80 per share and an Average Return on Equity of 36.54% point to a business that is modeled to earn well above its Cost of Equity of $5.01 per share. The gap between that required return and the Excess Return of $16.79 per share is what drives the model to an estimated intrinsic value that is meaningfully above the current traded level of $309.84.
The recent US$350 million AML penalty helps explain why some investors may question how long those modeled excess returns can last, even though the Excess Returns output still places more value on the franchise than the share price reflects. The model suggests that the earnings power implied by American Express’ book value and projected returns on equity is stronger than what is currently embedded in $309.84. Find out what American Express could be worth using our Excess Returns estimate.
The American Express Narrative: What Would Justify Today's Price?
Narratives for American Express pick up where the excess returns puzzle leaves off and explain which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price on Simply Wall St’s Community page. Each narrative links its figures to a concrete view of how American Express' growth, profitability and risk profile might change over time, and investors can revisit these narratives as fresh information becomes available.
Community models on American Express sit on the same data but reach very different comfort levels around what the current price implies.
Bull case: 30% undervalued
"American Express has spent 176 years selling one product under a dozen different names: trust...
Discover why this Narrative puts American Express at 30% undervalued.
Bear case: roughly fairly valued
"Please remember that the fair value estimate is just a number and, probably, a very wrong number...
Explore why this Narrative puts American Express at roughly fairly valued.
One more factor for American Express investors to weigh before acting
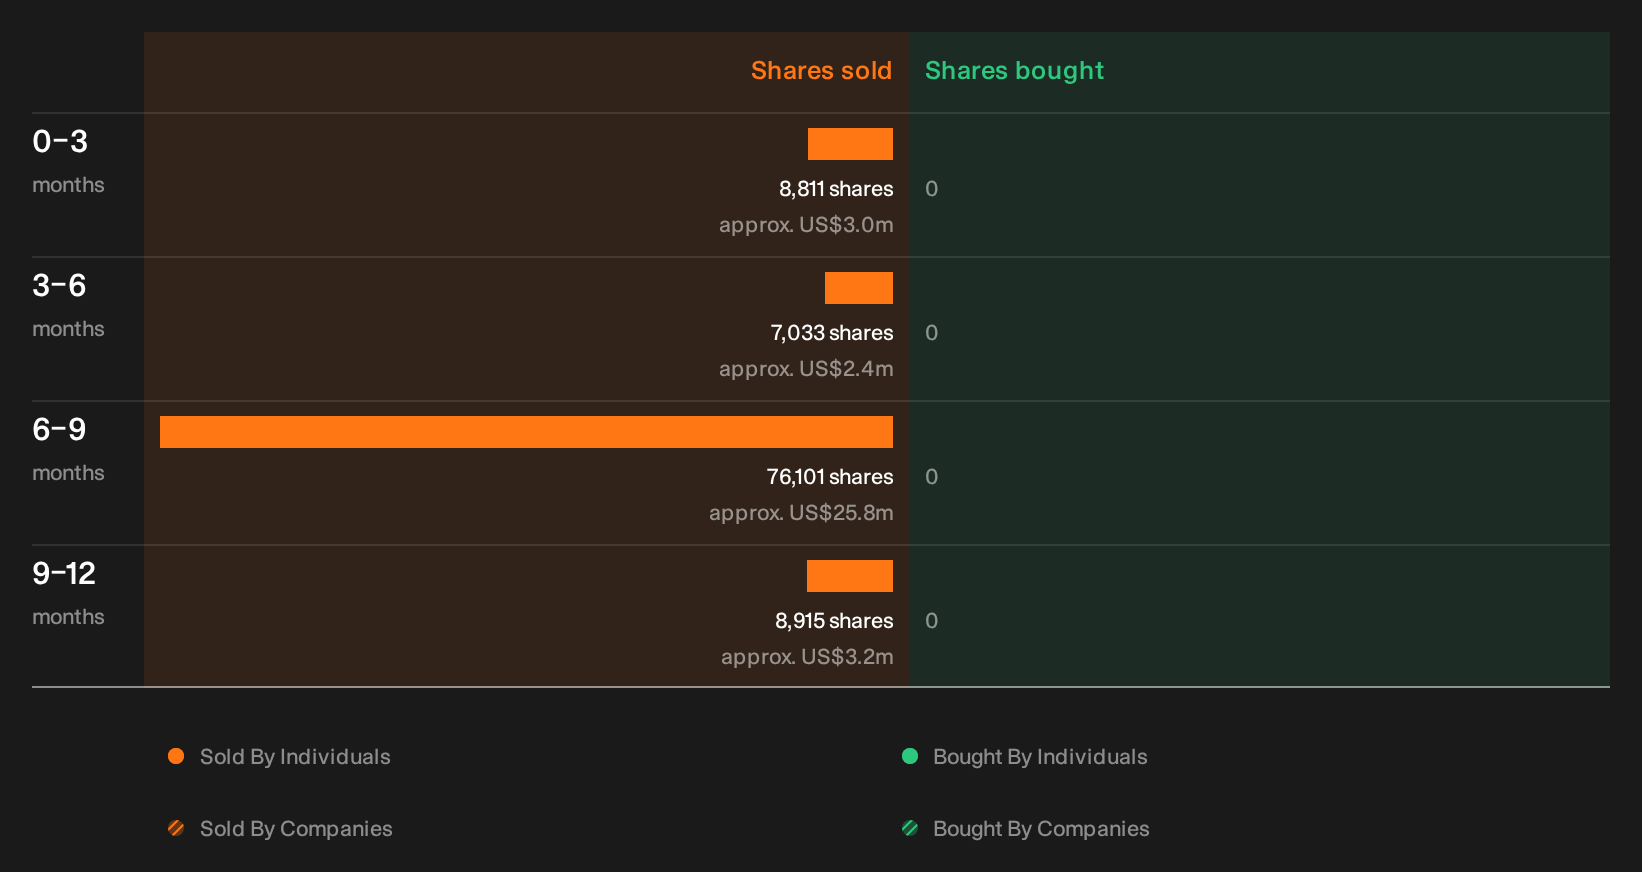
Before you lean too hard on any valuation output for American Express, it is worth pausing on what recent insider trading disclosures may be signalling about management’s own behaviour and timing. See the recent insider selling flagged for American Express.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com