


Dear Roku Stock Fans, Mark Your Calendars for October 14
In June, it was announced that Fox Corporation (FOX) would be acquiring TV streaming platform Roku (ROKU) for $160 per share in a cash-and-stock deal that is roughly valued at $22 billion. As media consolidation takes hold, this move would bring Fox’s news and sports channels, along with its free ad-supported streaming service Tubi, to Roku.
With the deal expected to close in the first half of 2027, Fox and Roku shareholders will vote on the deal on Oct. 14. All eyes turn to the possible approval. However, the regulatory threat remains. Semafor reported that the U.S. Department of Justice is widening its antitrust inquiry into the deal.
If the deal follows through, existing Fox shareholders would own about 73% of the combined company, and Roku shareholders would own about 27%, while Fox sees $400 million in run-rate cost synergies.
Ahead of that, we take a closer look at Roku.
About Roku Stock
Roku, Inc. is an American TV streaming platform company that connects viewers, content providers, and advertisers. The company operates through two segments: Platform, which includes digital advertising, content distribution, and subscription services, and Devices, which covers streaming players, Roku-branded televisions, audio products, and smart home devices.
Roku’s operating system powers smart TVs from multiple manufacturers, while its owned service, The Roku Channel, offers free ad-supported entertainment. The company has expanded beyond hardware into a broader connected-TV ecosystem, monetizing audience engagement through advertising and platform services. Roku, Inc. is headquartered in San Jose, California. It has a market capitalization of $22.69 billion.
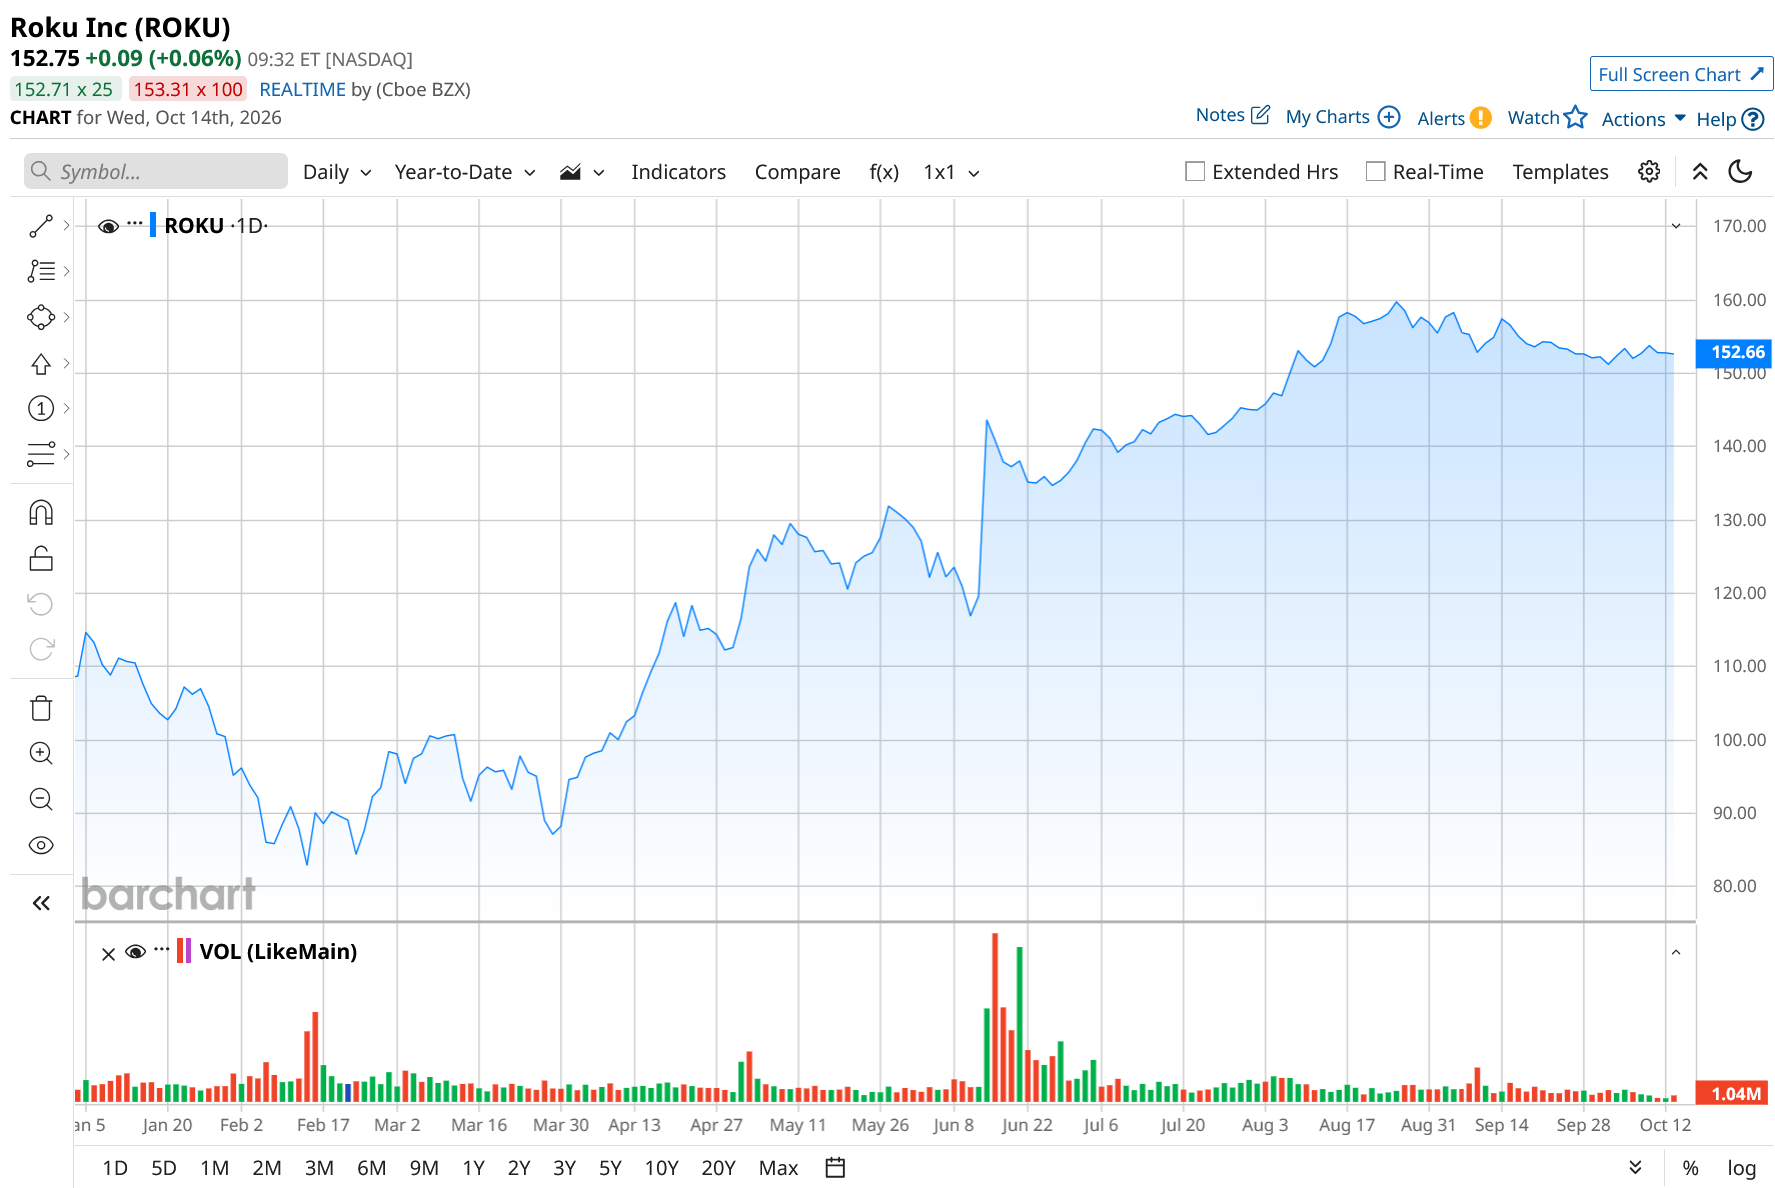
ROKU’s 63% gain over the past 52 weeks is mainly a re-rating around its pending acquisition by Fox, reinforced by a sharp turnaround in profitability and platform growth. It is up 48% over the past six months. The stock reached a 52-week high of $159.89 on Aug. 25 but is down 4.5% from that level.
Ahead of the merger, ROKU stock is trading at a considerably stretched valuation compared to its peers. Its forward-adjusted price-to-earnings ratio of 51.07x is higher than the industry average of 12.24x.
Q2 Earnings: Platform Revenue Grew on Strong Advertising and Subscription Demand
Roku reported a strong second quarter for fiscal 2026. The company’s total net revenue increased 22% year-over-year (YoY) to $1.35 billion. The growth was driven by a 25% YoY jump in platform revenue to $1.22 billion, as advertising and subscriptions advanced.
Advertising revenue grew 25% from the prior-year period to $673 million, while this segment’s gross margin climbed 650 basis points YoY to 62.4% as Roku shifted to higher-margin products, with video advertising outpacing both the U.S. OTT and digital ad markets. Subscription revenue grew 26% YoY to $548 million. However, unlike advertising, subscription gross margin fell about 360 basis points YoY to 41.4%, driven mainly by a shift toward premium subscriptions.
Platform revenue was also boosted by the rollout of the new Roku Home Screen, which was the platform’s biggest update in about a decade. In the U.S., it reaches more than half of broadband households before they choose what to watch.
Roku’s overall gross margin grew 4.9 percentage points YoY to 49.7%. Its adjusted EBITDA improved by a whopping 225% YoY to $254.30 million, with margin improving to 18.8%. Roku’s EPS increased from $0.07 to $1.08 over the same period.
Wall Street analysts are also robustly optimistic about the company’s bottom-line trajectory. For fiscal 2026, Roku’s EPS is expected to climb 394.9% YoY to $2.92, followed by a 33.6% improvement to $3.90 in fiscal 2027. For the third quarter, EPS is projected to rise 250% YoY to $0.56.
What Do Analysts Think About ROKU Stock?
Wedbush analysts believe Roku’s deal with Fox remains on track to close in the first half of 2027, assuming it clears all regulatory hurdles. Citing this, the firm’s analysts kept a “Neutral” rating and a $155 price target. Wedbush thinks the $400 million synergy target may be too low, as Roku’s advertising efforts expand and Fox brings its upfront advertising opportunities to Roku’s inventory.
In August, Wells Fargo analysts downgraded ROKU stock from “Overweight” to “Equal Weight” and cut the price target from $167 to $165. After the second-quarter results, it said the streaming platform’s strong results lifted its estimates but left little room for further upside in its valuation as the company moves toward its planned acquisition.
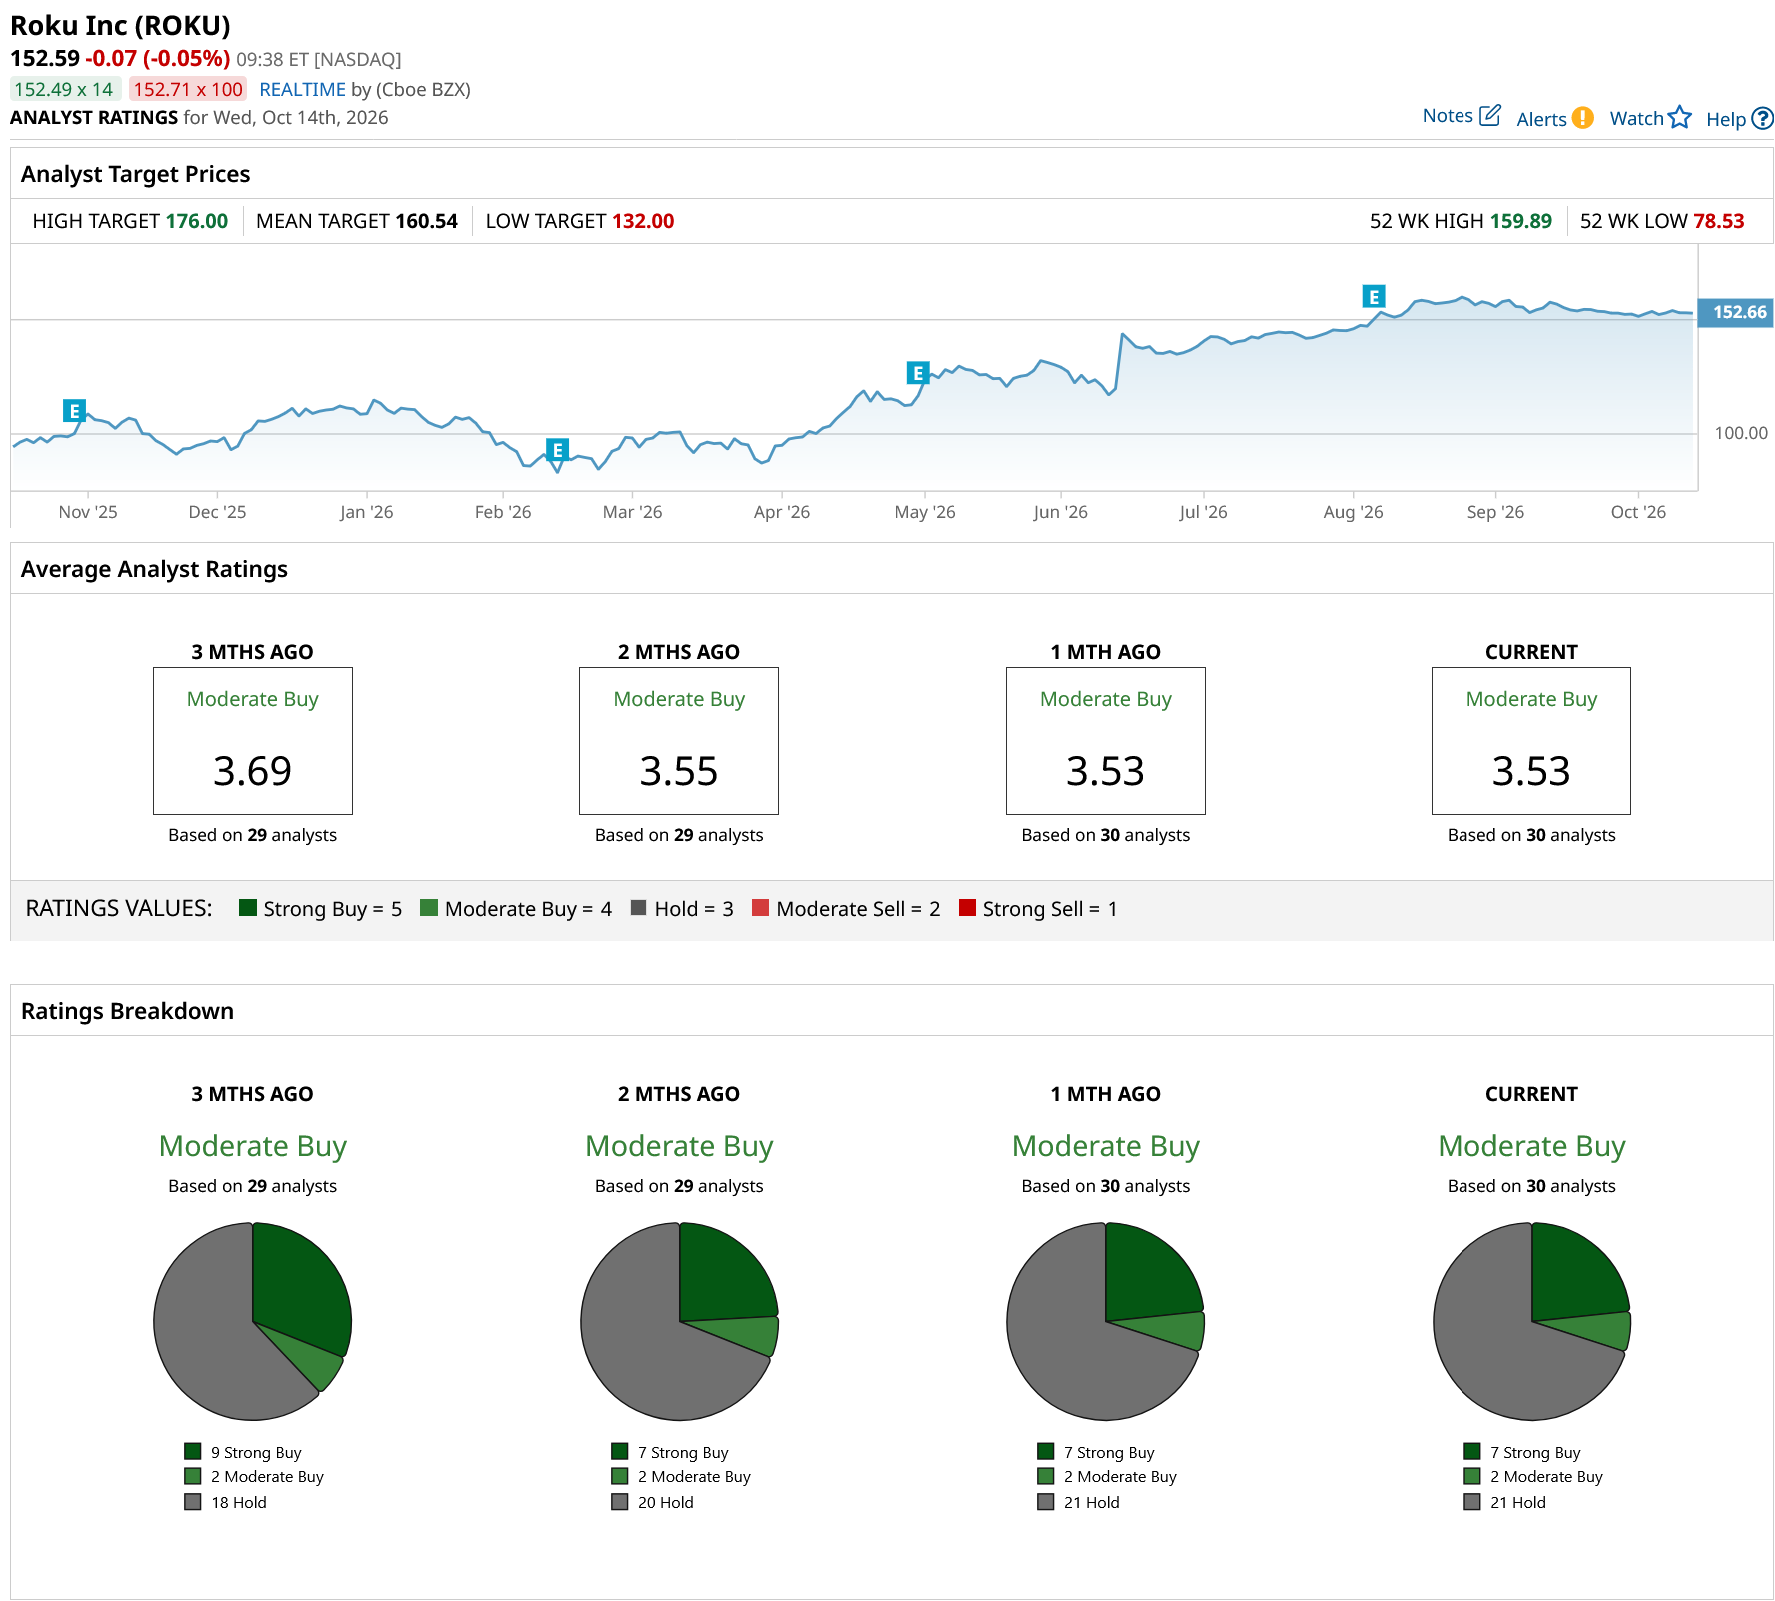
ROKU stock has been in the spotlight on Wall Street due to its impending acquisition, with analysts awarding it a consensus “Moderate Buy” rating overall. Of the 30 analysts rating the stock, seven analysts have given it a “Strong Buy” rating, two analysts suggest “Moderate Buy,” while 21 analysts are playing it safe with a “Hold” rating. The consensus price target of $160.54 represents 5% upside from current levels. The Street-high price target of $176 indicates a 15% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.