


Lam Research (LRCX) Stock May Be Fully Valued After Fresh AI Demand News
Lam Research has turned into a striking long term winner for shareholders, yet the share price around US$301 now raises a very specific question for you as an investor. Do the company’s current earnings really carry enough weight to support what the market is asking you to pay today?
- Over the past 5 years the stock has returned about 454.9%, which puts real pressure on the earnings story to justify how far the valuation has come.
- Recent coverage around AI related demand, supply constraints in semiconductor equipment and Lam Research’s role in advanced process nodes suggests investors may be baking in strong profit expectations that could meaningfully shape how its earnings multiple is viewed.
- Your read on Lam Research is one view; the desks covering it have another. See what analysts think Lam Research's shares could be worth.
The issue now is whether Lam Research’s current share price can be squared with what the business is earning today and what those earnings reasonably support.
If you are weighing Lam Research against other plays on AI driven chip demand, it can help to compare it with companies filtered through 92 AI infrastructure stocks.
Has Lam Research Run Too Far on Earnings?
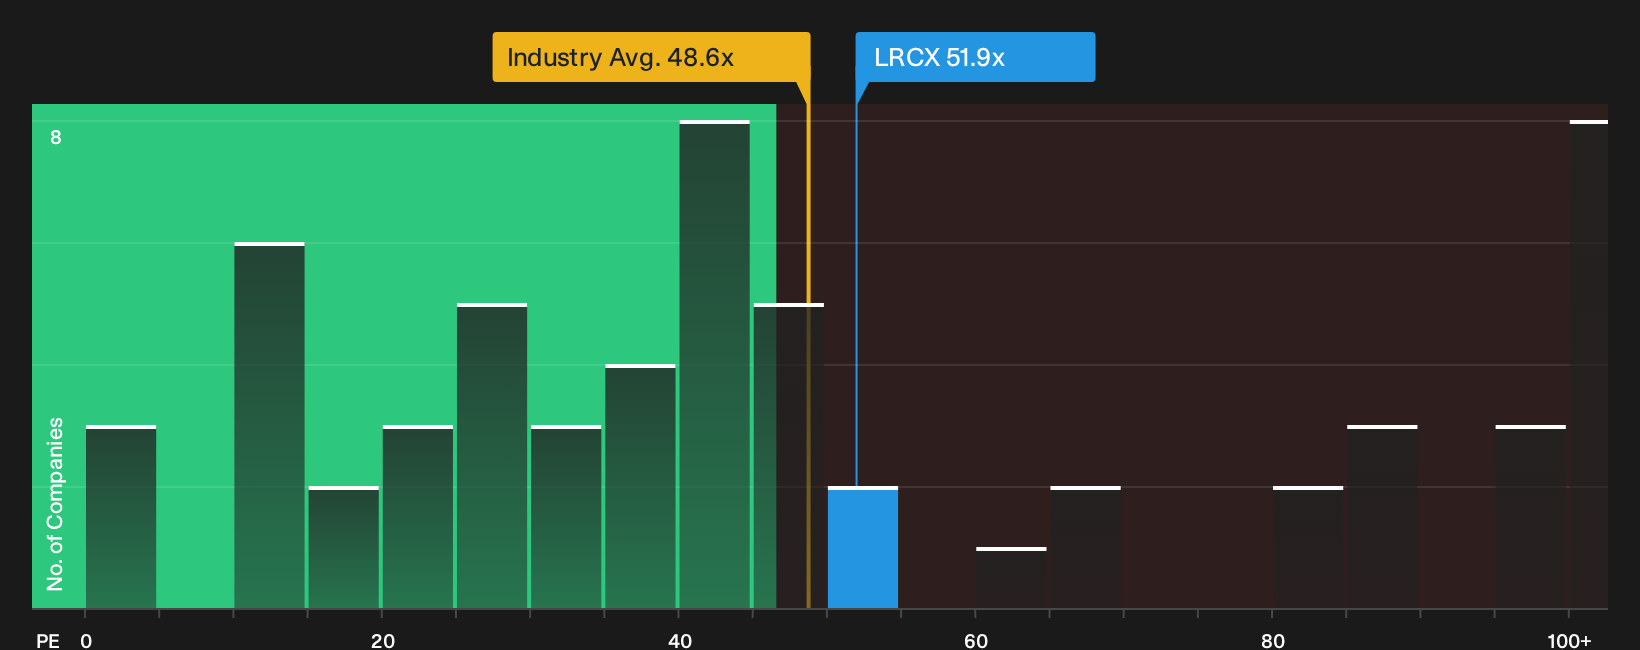
The P/E ratio is a useful lens for Lam Research because earnings remain central to how investors evaluate equipment makers that sell into AI-intensive wafer fabs. On this basis, the stock trades around 51.9x earnings, which is higher than the semiconductor industry average of 48.6x and above a peer group closer to 46.3x.
Recent headlines around record fiscal 2026 revenue and AI-linked demand help explain why the market is willing to pay a richer earnings multiple. However, the current P/E also stands above what a more tailored fair multiple model suggests for Lam Research. That model factors in the group’s growth profile, profitability, size and risks, and on that basis the shares screen as overvalued on earnings. Because of that gap, you need to judge whether AI-related momentum and Lam Research’s role in advanced process nodes justify paying this premium multiple relative to what the underlying business currently delivers. Explore the numbers behind Lam Research's P/E valuation.
The Lam Research Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Lam Research valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price. Each one presents Lam Research's implied fair value as a specific thesis about the business that you can track over time, rather than a one off snapshot on the Community page.
Community views on Lam Research are split between those who see more upside left in the AI memory buildout and those who think expectations already look full.
Bull case: 29% undervalued
"Lam makes money on the shortage and makes money on the response to it, because the capacity that eventually relieves the shortage has to be bought from somewhere…"
Discover why this Narrative puts Lam Research at 29% undervalued.
Bear case: roughly fairly valued
"The numbers imply that the current Lam Research share price already embeds ongoing AI related WFE strength, structurally high margins, and sustained capital returns, leaving limited room for disappointment if sector wide macro or regulatory pressure bites…"
Explore why this Narrative puts Lam Research at roughly fairly valued.
One more Lam Research signal to check before you move on
You have the current multiple and the competing narratives, but the next piece is how professional forecasters think this earnings story could look a few years from now. Explore where analysts expect Lam Research to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com