


Did Value Screens And Buy Upgrades Just Shift Alliance Resource Partners (ARLP) Stock Narrative?
- Alliance Resource Partners is preparing to release its third quarter 2026 results after a period in which value metrics such as Forward P/E and P/CF have screened below sector averages, reinforcing attention on how the coal and royalty portfolio is performing.
- The partnership is leaning into energy related technologies and infrastructure alongside its coal and mineral interests, which places more focus on how efficiently it can convert contracted volumes and royalty production into consistent cash generation.
- We will now examine how Alliance Resource Partners' investment narrative could be shaped by its value metrics screening below industry averages.
Look beyond Alliance Resource Partners and compare its valuation with a hand picked group of 32 high quality undervalued stocks that also appear inexpensive based on earnings and cash flow multiples.
Alliance Resource Partners Investment Narrative Recap
To own Alliance Resource Partners, you need to be comfortable with a coal heavy operation that is trying to squeeze more cash from lower cost mining and a growing oil and gas royalty platform. The short term hinge is whether mine efficiency and nearly fully committed 2026 and 2027 coal volumes offset normalized pricing and keep cash generation resilient.
The biggest risk right now sits in weaker coal economics and asset specific issues. Lower average realized prices, contract mix tilting to index linked volumes and the prior impairment at Mettiki show how quickly mine level returns can change. Volatile Bitcoin holdings also add noise to reported earnings.
The upcoming third quarter 2026 release on 26 October is the key near term checkpoint. Management plans to review results and outlook on a same day call. This will offer a fresh look at how well Alliance Resource Partners is translating coal volume commitments and royalty investments into actual cash flow.
This update matters for the catalyst investors often focus on most: consistent free cash generation from a lower cost coal base and expanding royalties while keeping leverage contained. Any commentary on coal pricing trends, further mine changes or the contribution from recently scaled oil and gas interests will be important for judging that path.
Alliance Resource Partners' current analyst narrative points to revenues of US$2.4b and earnings of US$401.5 million by 2029. That profile assumes revenue growth of 3.7% per year, with earnings increasing by about US$137.8 million from current earnings of US$263.7 million.
Uncover why Alliance Resource Partners' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
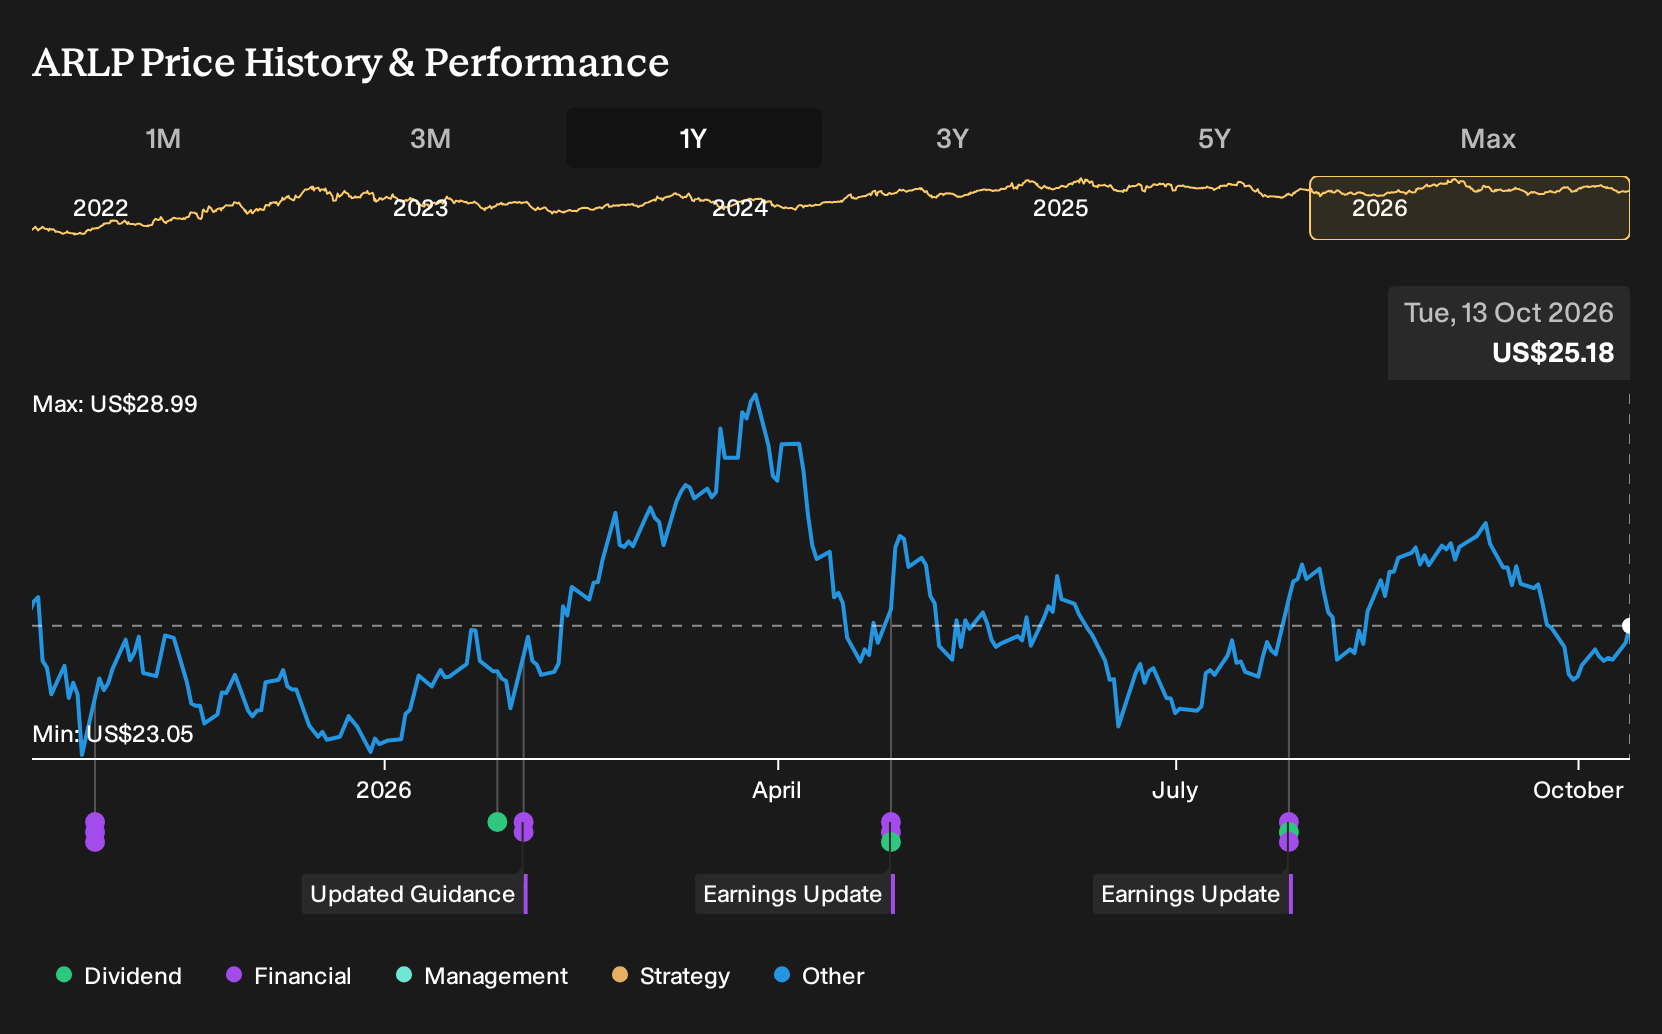
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$31.17 to nearly US$117 per unit, showing how far opinions on Alliance Resource Partners can stretch. As you weigh this against coal pricing pressure, mine level risks and growing royalty volumes, recognise how sharply private investors can disagree, and explore several of these alternative viewpoints before deciding how this partnership fits your portfolio.
Explore another Alliance Resource Partners fair value estimate, including one that suggests it could be worth just $31.17!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alliance Resource Partners research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alliance Resource Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alliance Resource Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alliance Resource Partners?
Once you have a handle on Alliance Resource Partners, it can help to widen the lens and see how other businesses with different profiles stack up on quality, income potential and balance sheet strength.
- If you want potential income combined with resilience, scan for companies that screen as income "fortresses" with the 8 dividend fortresses.
- For investors who care most about financial robustness, start with a list of solid balance sheet and fundamentals (25 results) that meet strict debt and liquidity filters.
- If you like the idea of finding under-the-radar opportunities, check out a 20 high quality undiscovered gems that pair strong fundamentals with relatively low attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com