


Eli Lilly and Company Earnings Preview: What to Expect
Eli Lilly and Company (LLY), based in Indianapolis, Indiana, with a market capitalization of approximately $1.1 trillion, is a global pharmaceutical company that researches, develops, manufactures, and markets medicines. Its treatments address conditions including diabetes, obesity, cancer, Alzheimer's disease, autoimmune disorders, migraines, and other health conditions worldwide.
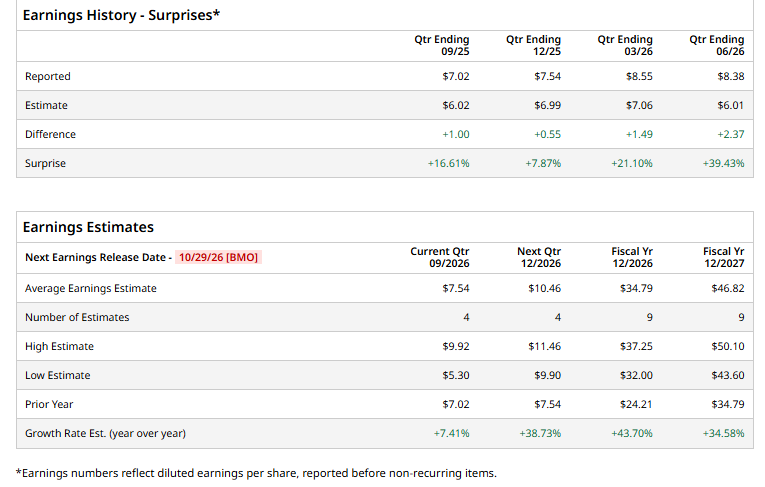
LLY is set to report its Q3 earnings on Thursday, October 29, 2026, before the market opens. Wall Street anticipates diluted EPS of $7.54, a 7.4% increase from $7.02 in the same quarter last year. Notably, the company has topped analysts’ EPS expectations in each of the past four quarters.
For fiscal 2026, analysts expect LLY to report EPS of $34.79, up 43.7% from $24.21 in fiscal 2025. Moreover, earnings growth is expected to remain robust in fiscal 2027, with EPS forecast to climb another 34.6% year over year to $46.82.
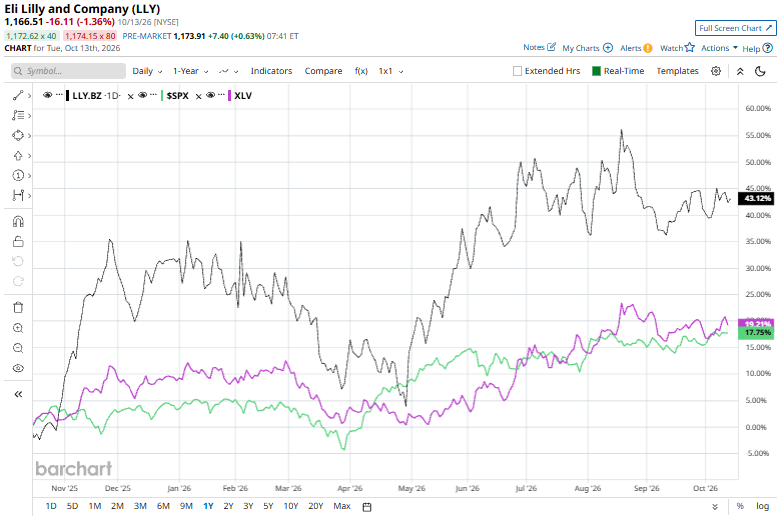
Over the past 52 weeks, LLY stock has climbed 42.4%, outperforming both the S&P 500 Index ($SPX), which advanced 17.3%, and the State Street Health Care Select Sector SPDR ETF (XLV), which gained 19.5% over the same period.
Eli Lilly’s outperformance over the past year was driven by robust revenue growth, market share gains, expanding operating margins, and share buybacks. Revenue grew at an annual rate of 43.1% over the past two years, while the adjusted operating margin expanded by 18.7 percentage points. Share repurchases further boosted earnings per share (EPS) growth relative to revenue growth.
Adding to its growth prospects, Lilly announced on Sept. 30 that its investigational combination therapy, EloraTZP, delivered weight loss of up to 23.3% and A1C reductions of up to 2.9% over 48 weeks in a Phase 2b trial, outperforming tirzepatide alone. The results strengthen Lilly’s obesity and diabetes drug pipeline, with Phase 3 trials planned for the fourth quarter of 2026. However, higher rates of gastrointestinal side effects and treatment discontinuation remain key risks as development advances.
Analysts remain bullish on LLY, with a consensus “Strong Buy” rating. Of the 29 analysts covering the stock, 23 recommend a “Strong Buy,” three assign a “Moderate Buy,” and the remaining three rate it a “Hold.” Meanwhile, the average analyst price target of $1,357.04 suggests potential upside of 16.3% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.