


Spire Healthcare Group (LSE:SPI) Stock Still Looks Cheap On A 46% Run
Spire Healthcare Group shares have logged a solid run so far this year, which naturally raises the question of whether the current price is still grounded in what the business delivers in sales. With the stock now drawing more attention, the key issue for you is how much revenue the market is effectively paying for.
- The share price is up 46.4% year to date, which puts the spotlight on how much revenue support there is behind that move in Spire Healthcare Group.
- The group relies on converting patient volumes and pricing into consistent sales, so expectations around occupancy, case mix and cost control can heavily influence how investors frame what each pound of revenue is worth.
- Your read on Spire Healthcare Group is one view; the desks covering it have another. See what analysts think Spire Healthcare Group's shares could be worth.
The stock's next move may depend on whether today's valuation is well supported by Spire Healthcare Group's sales base and how investors choose to price that revenue stream.
If you want more context on how the market values hospital and healthcare revenue streams like Spire Healthcare Group's, it helps to compare it with solid balance sheet and fundamentals stocks screener (9 results).
Is Spire Healthcare Group a Bargain on Sales?
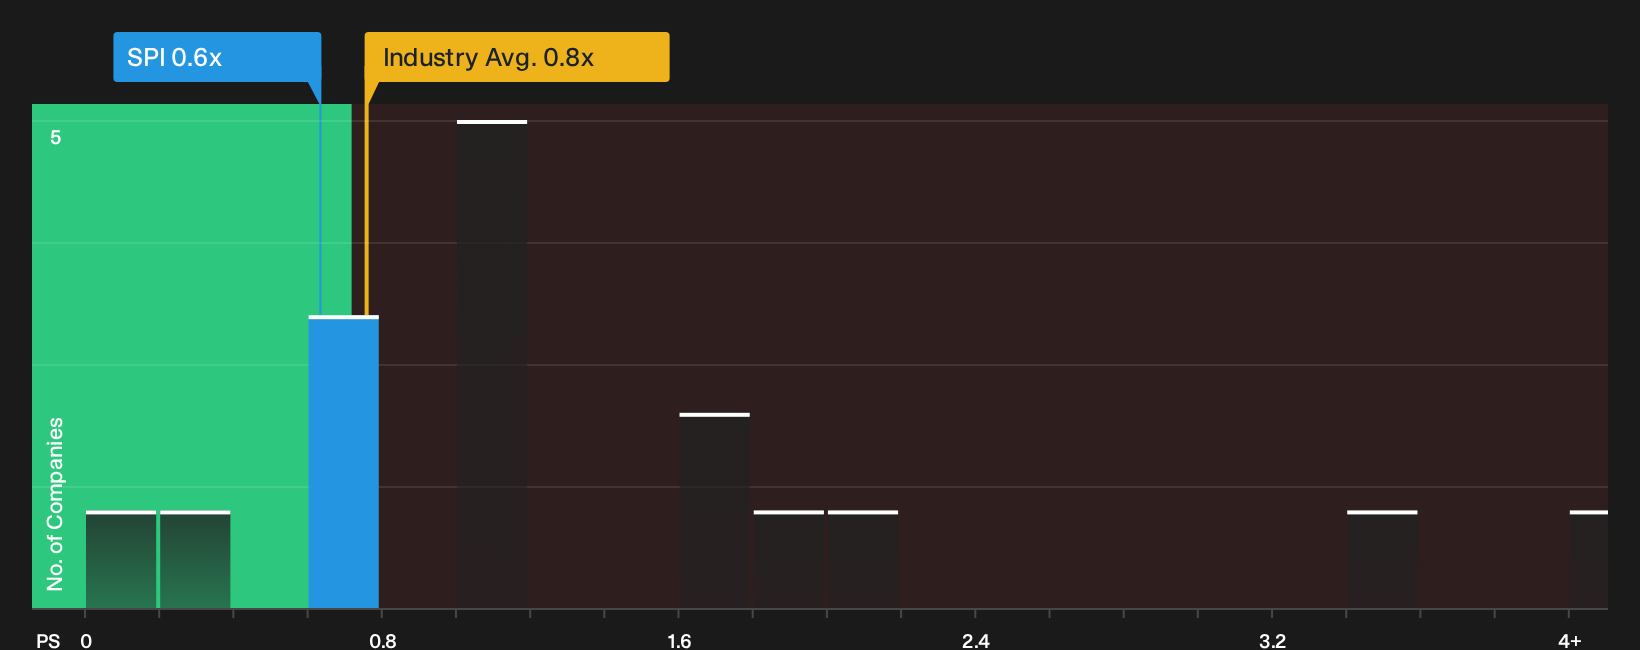
A price-to-sales lens fits Spire Healthcare Group because investors are effectively paying for its ability to turn patient volumes into top line revenue. On this yardstick, the shares trade on a P/S of about 0.6x, which is below both the broader healthcare industry average of 1.3x and a peer group closer to 2.1x. That gap means each pound of Spire Healthcare Group revenue is currently valued at a lower level than many listed hospital and healthcare operators.
The fair P/S that a model might expect for Spire Healthcare Group, after factoring in its margins, size and risk profile, sits higher than the current market multiple. This suggests the stock screens as undervalued on a sales basis, with the market assigning a relatively modest price tag to the existing revenue base compared with what that framework would imply. For you as a shareholder or potential investor, the key judgement is whether Spire Healthcare Group can keep converting that revenue into sustainable cash generation that could justify a stronger multiple over time. Explore the numbers behind Spire Healthcare Group's P/S valuation.
The Spire Healthcare Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the price to sales puzzle leaves off for Spire Healthcare Group by spelling out which combinations of future growth, profitability and earnings outcomes would need to apply for the shares to be worth materially more or materially less than they are today, and they sit on Simply Wall St's Community page. Rather than focusing on a single multiple or model, each scenario lays out the key moving parts behind its fair value estimate so you can later compare those assumptions with the actual results as they are reported.
One of the top community narratives on Spire Healthcare Group: roughly fairly valued
"Persistent labour cost inflation from National Insurance and National Minimum Wage uplifts, alongside broader salary pressure in healthcare, could outpace the £30 million transformation savings already delivered..."
Discover why this Narrative puts Spire Healthcare Group at roughly fairly valued.
One more Spire Healthcare Group check that sits beside the price tag
Price multiples only tell part of the story for Spire Healthcare Group. Another useful cross check is to look at where professional analysts currently expect the business to be a few years from now, and then compare that view with where it stands today. Explore where analysts expect Spire Healthcare Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com