


Strauss Group (TASE:STRS) Sets Investor Conference, Is The Upside Already Priced In?
Investor conference puts Strauss Group in focus
Strauss Group (TASE:STRS) has called an investor conference for 22 October 2026 at the Tel Aviv Stock Exchange to outline its 2027 to 2030 plan, including an English online session.
Strauss Group’s ₪118.9 share price sits against a backdrop of firm short term momentum, with a 1 day share price return of 4.12% and 7 day gain of 9.18%. A 1 year total shareholder return of 30.78% and 3 year total shareholder return of 71.73% suggest the investor conference arrives at a time when optimism has already been building into the story.
Scan momentum-driven consumer stocks connected to Strauss Group’s story by reviewing the hand picked 185 high quality undervalued stocks that combine balance sheet support with stronger recent share price trends.
Bulls point to Strauss Group’s recent run and upcoming plan as evidence that the rerating may have room to extend. Bears see a crowded trade already. The question is which side the current valuation actually supports next.
Price-to-earnings of 22.7x: Is it justified?
Strauss Group changes hands at a P/E of 22.7x, which places the ₪118.9 share price at a lower earnings multiple than its direct peers but higher than the broader Asian food sector.
The P/E ratio compares what investors pay for each unit of current earnings. For a consumer staples group like Strauss Group, where products range from yogurts and coffee to water systems, that benchmark helps you judge how the market is weighing its profit profile against other food producers.
On a peer set basis, the stock trades at a discount, with its 22.7x P/E below the 27.5x average. That kind of gap can signal that the market is assigning a more conservative stance on future profitability or balance sheet risk, even though the business has high quality earnings and has grown profits by 6.7% per year over the past 5 years.
Stacked against the wider Asian food industry, the picture flips. The same 22.7x P/E sits well above the 14.8x sector average, which points to investors accepting a richer valuation than many regional food peers for Strauss Group’s earnings stream.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 22.7x (ABOUT RIGHT)
Still, the story can fray if Strauss Group faces weaker demand in key coffee markets or if its water systems segment requires heavier investment than investors currently expect.
Find out about the key risks to this Strauss Group narrative.
Another view on Strauss Group’s value
The earlier P/E check painted Strauss Group as roughly fairly priced. A second lens tells a different story. Our DCF model puts the future cash flow value at ₪35.56 per share, while the market price is ₪118.9. That points to a much richer tag than the cash forecasts suggest. The key question is which signal you trust more when sentiment cools.
Look into how the SWS DCF model arrives at its fair value.
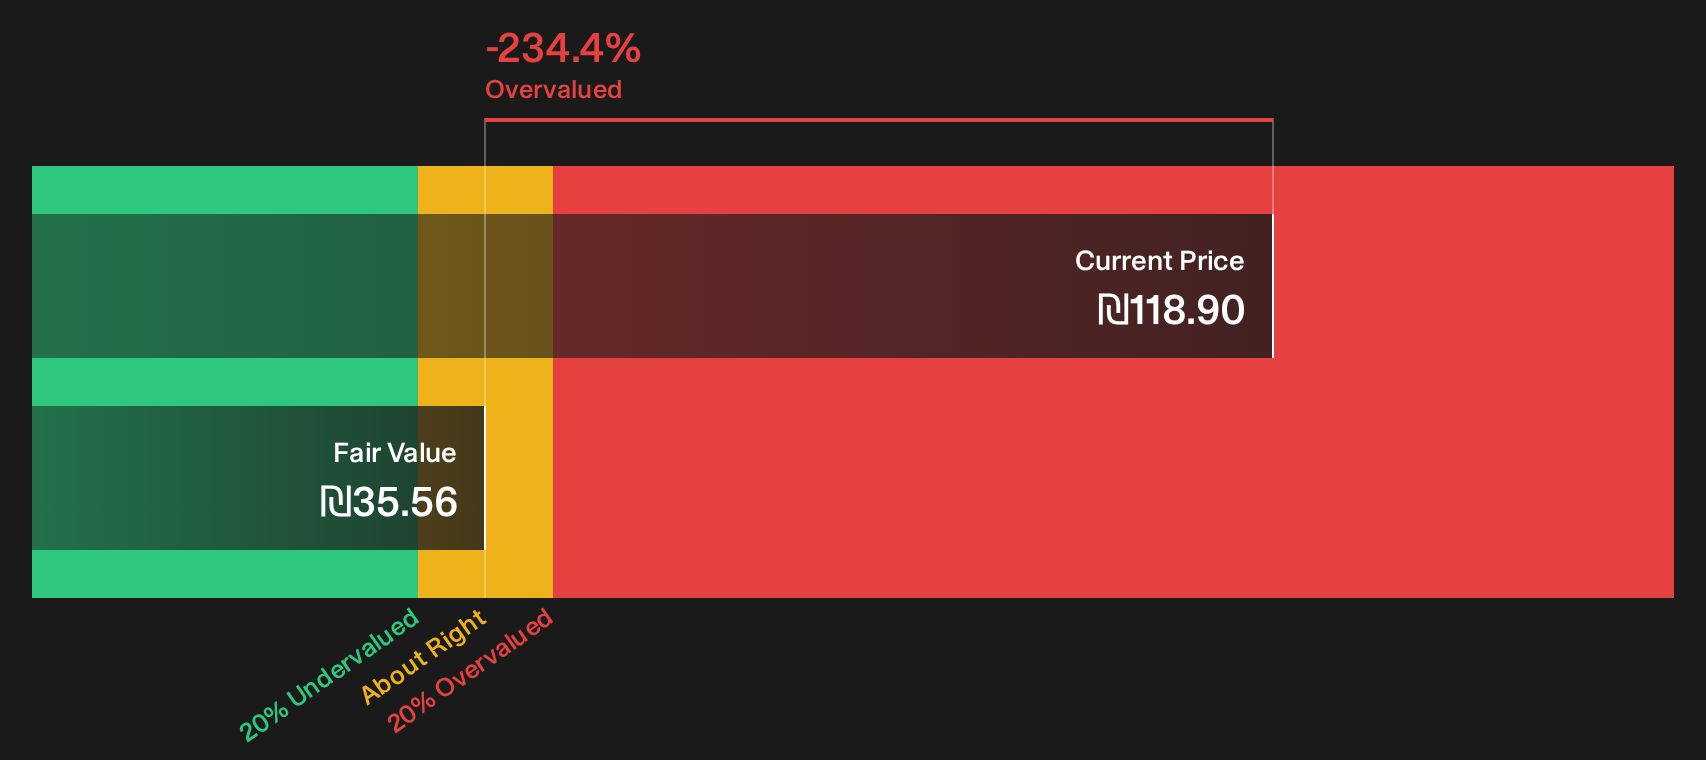
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Strauss Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Strauss Group looks upbeat, yet the risk picture is more nuanced and worth checking directly before forming a firm view. If you want to see the specific concern that has been flagged, review the 1 important warning sign.
Looking for more investment ideas beyond Strauss Group?
If Strauss Group has sharpened your thinking, do not stop here. The right watchlist often comes from comparing very different setups side by side.
- Target reliable cash generators by scanning income focused stocks through the 223 dividend fortresses.
- Spot resilient businesses that aim to protect capital first by reviewing the 224 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities with strong fundamentals using the 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com