


Softcat (LSE:SCT) Upgraded Guidance Again, Is It Still Below Fair Value?
Softcat (LSE:SCT) is back in focus after its latest full year results, which followed two profit forecast upgrades and fresh commentary on deploying recent equity raise proceeds for acquisitions and further investment.
Recent trading has leaned positive, with a 7 day share price return of 4.96% and a year to date share price gain of 40.03% at a current level of £19.24. Total shareholder return sits at 25.87% over one year and 44.88% over three years. This suggests momentum has been building around Softcat as investors reassess both its growth potential and risk profile following the upgrades and full year numbers.
Compare Softcat's momentum and IT focus with a curated 92 AI infrastructure stocks that benefits from the same push into cloud, security, and data-heavy workloads.
Bulls see Softcat as a high quality IT reseller that justifies a richer tag after upgrades. Bears view the move as froth. Which story does the current valuation actually support?
Most Popular Narrative: 10.5% Undervalued
On the latest narrative, Softcat's fair value of £21.51 sits above the £19.24 close, which frames the recent rally as still leaving some headroom if those assumptions hold.
Softcat's expansion in cybersecurity services, driven by customer prioritization of cyber investments and the enhancement of internally delivered services, positions the company for continued revenue growth in this segment. Growth in data center and networking demand, supported by a robust pipeline and ongoing technological advancement, is expected to drive revenue upward, reflecting in higher gross profits.
See why 15 investors see Softcat as 11% undervalued.
The most followed narrative rests on a discount rate of 9.81%, forecast revenue growth of 20.12% and an expected net margin of 6.40%. Those inputs combine into a fair value estimate of £21.51 per share, which is 10.5% above the last close. This implies investors are paying below that narrative's view of long term earnings power.
Analysts within that storyline also look for earnings of £194.3m by 2029 and apply a forward P/E of 29.3x to those future profits. That multiple is slightly below the 33.6x used for the wider GB IT sector in the same framework. This suggests the scenario does not rely on Softcat trading at a large premium to domestic peers to reach the fair value level.
At the same time, the narrative assumes revenue of £3.0b and a lower margin profile than today. This keeps the model grounded in a mix of higher top line and thinner profitability. For readers, the key question is whether those revenue and margin paths feel realistic when set against Softcat's current £1,750.4m sales base and £141.1m net income.
Result: Fair Value of £21.51 (UNDERVALUED)
Still, the Softcat story could shift quickly if software margins compress further or if rising commissions and wage costs outpace the expected revenue progress.
Find out about the key risks to this Softcat narrative.
Another View: Softcat Through The Cash Flow Lens
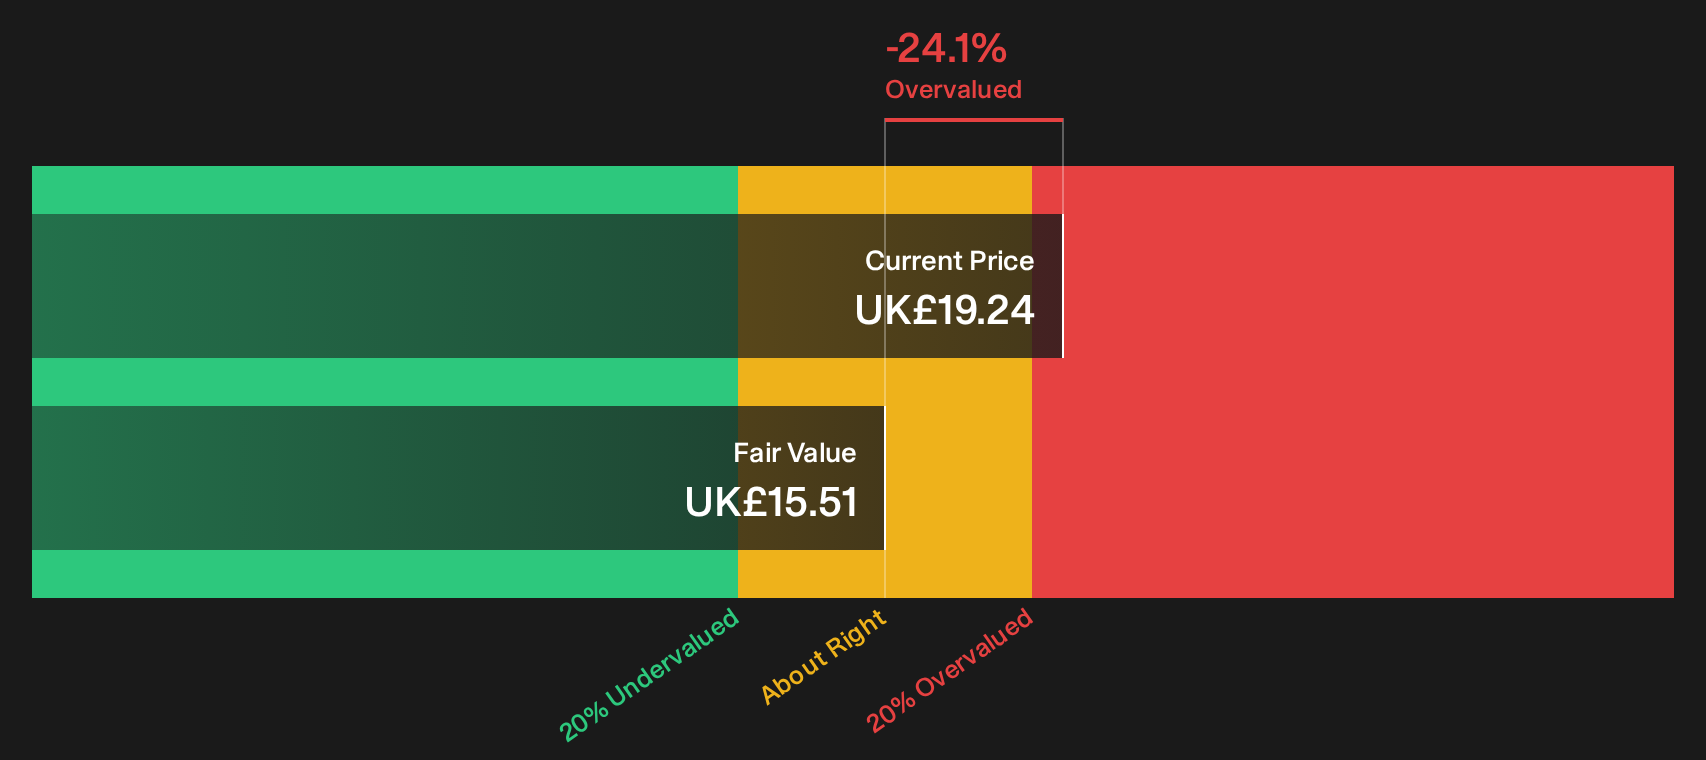
A different lens paints a less generous picture. The SWS DCF model puts Softcat's future cash flow value at £15.51 per share versus the £19.24 market price, which frames the stock as overvalued on this approach rather than 10.5% undervalued. So which story deserves more weight in your process?
For readers who want to see how those cash flow assumptions are built and discounted back, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Softcat for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Softcat's value make this a moment to move quickly. Review the underlying forecasts and interrogate both the risks and the upside case for yourself, then pressure test that view against the 3 key rewards and 2 important warning signs.
Looking for more Softcat-like investment ideas?
Do not stop your research at Softcat. Broaden your watchlist with other clear setups so you are not relying on a single story to carry your portfolio.
- Target resilient upside by scanning a 4 resilient stocks with low risk scores that aims to prioritise businesses with steadier return and risk profiles.
- Hunt for mispriced quality through a 8 high quality undervalued stocks focused on companies where fundamentals and market prices appear out of sync.
- Spot future standouts early using a 5 high quality undiscovered gems that concentrates on quieter tickers with solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com