


3 UK Penny Stocks With Market Caps Larger Than £100M
Amidst the backdrop of a faltering FTSE 100, influenced by weak trade data from China, investors are increasingly looking beyond traditional blue-chip stocks for opportunities. Penny stocks, though often associated with smaller or newer companies, continue to hold potential for those seeking value and growth outside the mainstream. While the term may seem outdated, these stocks can offer significant opportunities when supported by strong financials and robust fundamentals.
Underneath we present a selection of stocks filtered out by our screen.
Mercia Asset Management (AIM:MERC)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Mercia Asset Management PLC is a private equity and venture capital firm that focuses on a wide range of investment stages including incubation, venture debt, and growth capital, with a market capitalization of £130.64 million.
Operations: The company generates revenue through its Proactive Specialist Asset Management segment, which contributed £34.14 million.
Market Cap: £130.64M
Mercia Asset Management, with a market cap of £130.64 million, focuses on diverse investment stages and remains unprofitable with negative return on equity. Despite this, the firm is debt-free and has stable weekly volatility. Its seasoned management and board provide experienced oversight. Recent developments include a $38 million facilities agreement with Metro Bank to support growth initiatives under its Mercia '27 strategic plan. Although earnings are forecasted to grow significantly at 117.83% annually, past losses have increased by 66.7% per year over five years, highlighting potential risks for investors in this penny stock segment.
- Get an in-depth perspective on Mercia Asset Management's performance by reading our balance sheet health report here.
- Review our growth performance report to gain insights into Mercia Asset Management's future.

Gulf Keystone Petroleum (LSE:GKP)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Gulf Keystone Petroleum Limited explores, evaluates, develops, and produces oil and gas in the Kurdistan Region of Iraq with a market cap of £430.54 million.
Operations: The company generates revenue of $192.76 million from its exploration and production activities in the oil and gas sector.
Market Cap: £430.54M
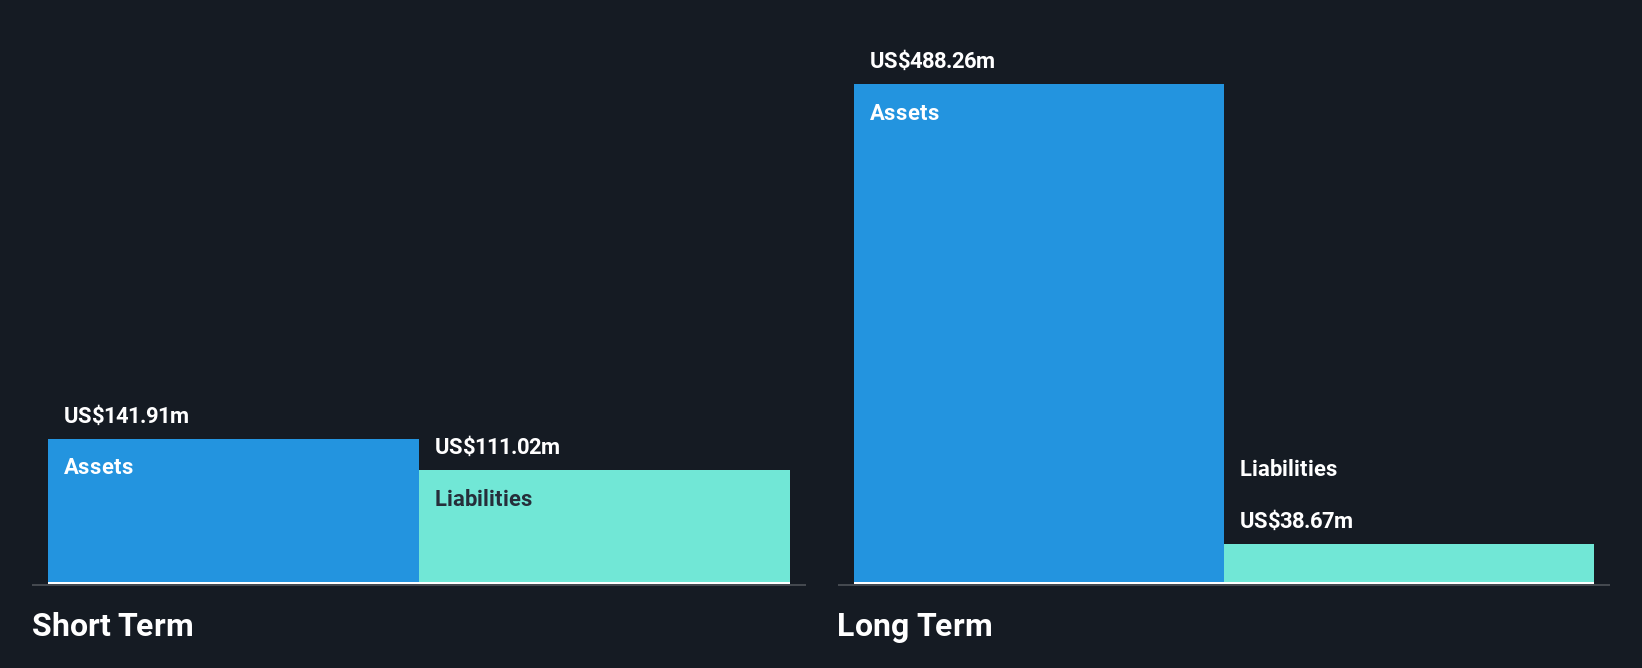
Gulf Keystone Petroleum, with a market cap of £430.54 million, has shown resilience despite challenges. The company reported net income of US$12.9 million for H1 2026, recovering from a net loss the previous year, although production was impacted by regional security issues leading to temporary shut-ins. Despite trading at 84.9% below fair value estimates and having no debt, its dividend yield of 3.94% is not well covered by earnings or cash flows. The management team is seasoned with an average tenure of 5 years and continues to navigate operational hurdles effectively in the volatile oil sector.
- Click here and access our complete financial health analysis report to understand the dynamics of Gulf Keystone Petroleum.
- Gain insights into Gulf Keystone Petroleum's future direction by reviewing our growth report.
QinetiQ Group (LSE:QQ.)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: QinetiQ Group plc offers science and technology solutions in the defense, security, and infrastructure sectors across the United States, Australia, Canada, and Germany with a market cap of £2.33 billion.
Operations: The company generates revenue through its EMEA Services segment, which accounts for £1.53 billion, and its Global Solutions segment, contributing £393.4 million.
Market Cap: £2.33B
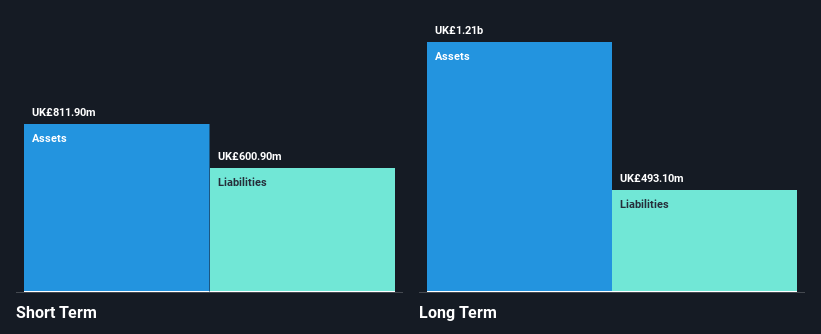
QinetiQ Group, with a market cap of £2.33 billion, has recently turned profitable, marking a significant shift in its financial trajectory. The company's debt is well managed, with operating cash flow covering 69.2% of its obligations and interest payments covered 13.1 times by EBIT. Despite an increase in the debt-to-equity ratio over five years to 60.5%, short-term assets exceed both short-term and long-term liabilities, highlighting robust liquidity management. Trading at 37.5% below estimated fair value and offering a reliable dividend yield of 2.42%, QinetiQ presents potential value despite previous earnings declines impacted by one-off losses of £57.5 million.
- Navigate through the intricacies of QinetiQ Group with our comprehensive balance sheet health report here.
- Explore QinetiQ Group's analyst forecasts in our growth report.
Key Takeaways
- Gain an insight into the universe of 251 UK Penny Stocks by clicking here.
- Ready For A Different Approach? Rare earth metals are the new gold rush. Find out which 32 stocks are leading the charge.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com