


Is BlackBerry (TSX:BB) Undervalued Or Is Its Turnaround Story Already Priced In?
BlackBerry (TSX:BB) has drawn fresh attention after its recent share move, with the stock up over the past month but lower across the past 3 months and week. Investors are reassessing the software-focused business.
At around CA$12.09, BlackBerry’s share price has swung sharply, with a 13.95% 1 month share price return followed by a 7 day decline of 11.43%. The year to date share price return of 131.61% and 3 year total shareholder return of 137.99% point to strong momentum that has recently cooled.
Scan how BlackBerry’s recent swing compares with other fast moving software and tech plays using our hand picked 10 high quality undiscovered gems.
Bulls see a software turnaround gaining traction, while bears point to choppy returns and a modest discount to targets. Which case does BlackBerry’s current valuation actually lean toward?
Most Popular Narrative: 25% Undervalued
BlackBerry is trading at CA$12.09 against a narrative fair value of CA$16.22, so the story that followers are focused on is a material gap between price and estimated worth.
The market is pricing BlackBerry as a maturing automotive software company. What it actually has is the safety infrastructure layer that physical AI cannot be commercially deployed without. The automotive royalty backlog took fifteen years to reach $950M. The physical AI backlog is starting from zero right now, in a faster-growing market, with the same royalty model and the same impossibility of removal once embedded.
See why 23 investors see BlackBerry as 25% undervalued.
Result: Fair Value of CA$16.22 (UNDERVALUED)
Still, the BlackBerry narrative can unravel quickly if physical AI royalties arrive slower than expected or if more automakers push certified operating systems fully in house.
Find out about the key risks to this BlackBerry narrative.
Another View: What BlackBerry’s P/E Signals
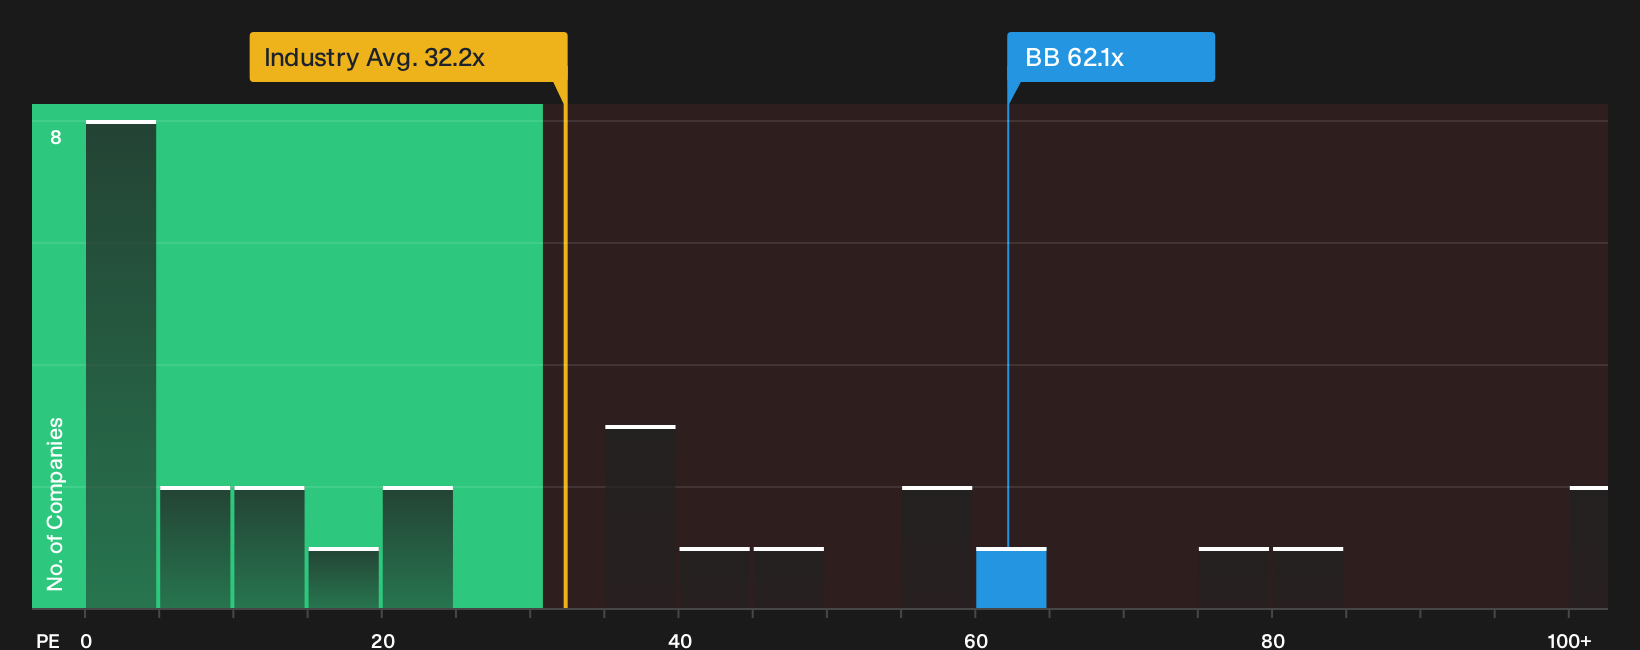
The story flips when you switch from narrative fair value to the plain P/E math. BlackBerry trades on about 62x earnings while the North American software group is around 32x and the fair ratio is 33x. That is a wide premium. Is that gap compensation for growth, or just extra risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mood around BlackBerry appears mixed after recent developments. Review the underlying risks and potential upsides, then decide where you stand with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BlackBerry?
If BlackBerry has you thinking harder about where to put fresh capital next, do not stop here. Broaden your watchlist and pressure test your thesis across other sectors using targeted screeners that surface specific traits instead of just headlines.
- Target potential bargains by focusing on quality businesses priced below their estimated worth through the 7 high quality undervalued stocks.
- Strengthen your downside protection by searching for companies with clean balance sheets using the list of solid balance sheet and fundamentals (8 results).
- Identify potential income ideas by zeroing in on payout-focused stocks with the 2 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com