


Discovering Undiscovered Gems in Asia This October 2026
As October 2026 unfolds, Asian markets are navigating a complex landscape marked by fluctuating oil prices and geopolitical tensions, with the broader market sentiment reflecting cautious optimism amid these challenges. In this dynamic environment, identifying promising small-cap stocks requires a keen eye for companies that demonstrate resilience and potential growth despite the prevailing economic uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Hyosung TNC (KOSE:A298020)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Hyosung TNC Corporation manufactures and sells fiber in South Korea and internationally, with a market capitalization of ₩1.15 trillion.
Operations: Hyosung TNC generates revenue primarily from its Textile and Trade sectors, with the Textile segment contributing ₩5.32 trillion and the Trade sector adding ₩5.37 trillion. The company experiences internal sales adjustments of -₩2.33 trillion between these sectors, impacting overall figures.
Hyosung TNC, a relatively small player in the textile industry, has made significant strides with its innovative bio-based spandex. The company's earnings surged by 42.7% over the past year, outpacing the chemicals industry average. Its recent expansion into European and global markets with eco-friendly products like regen Bio Spandex highlights a commitment to sustainability. Despite a high net debt to equity ratio of 99.5%, interest payments are well covered by EBIT at 4.5 times, indicating strong financial management. Trading at nearly 89% below estimated fair value suggests potential for future growth as it strengthens partnerships globally.

Intermestic (TSE:262A)
Simply Wall St Value Rating: ★★★★★☆
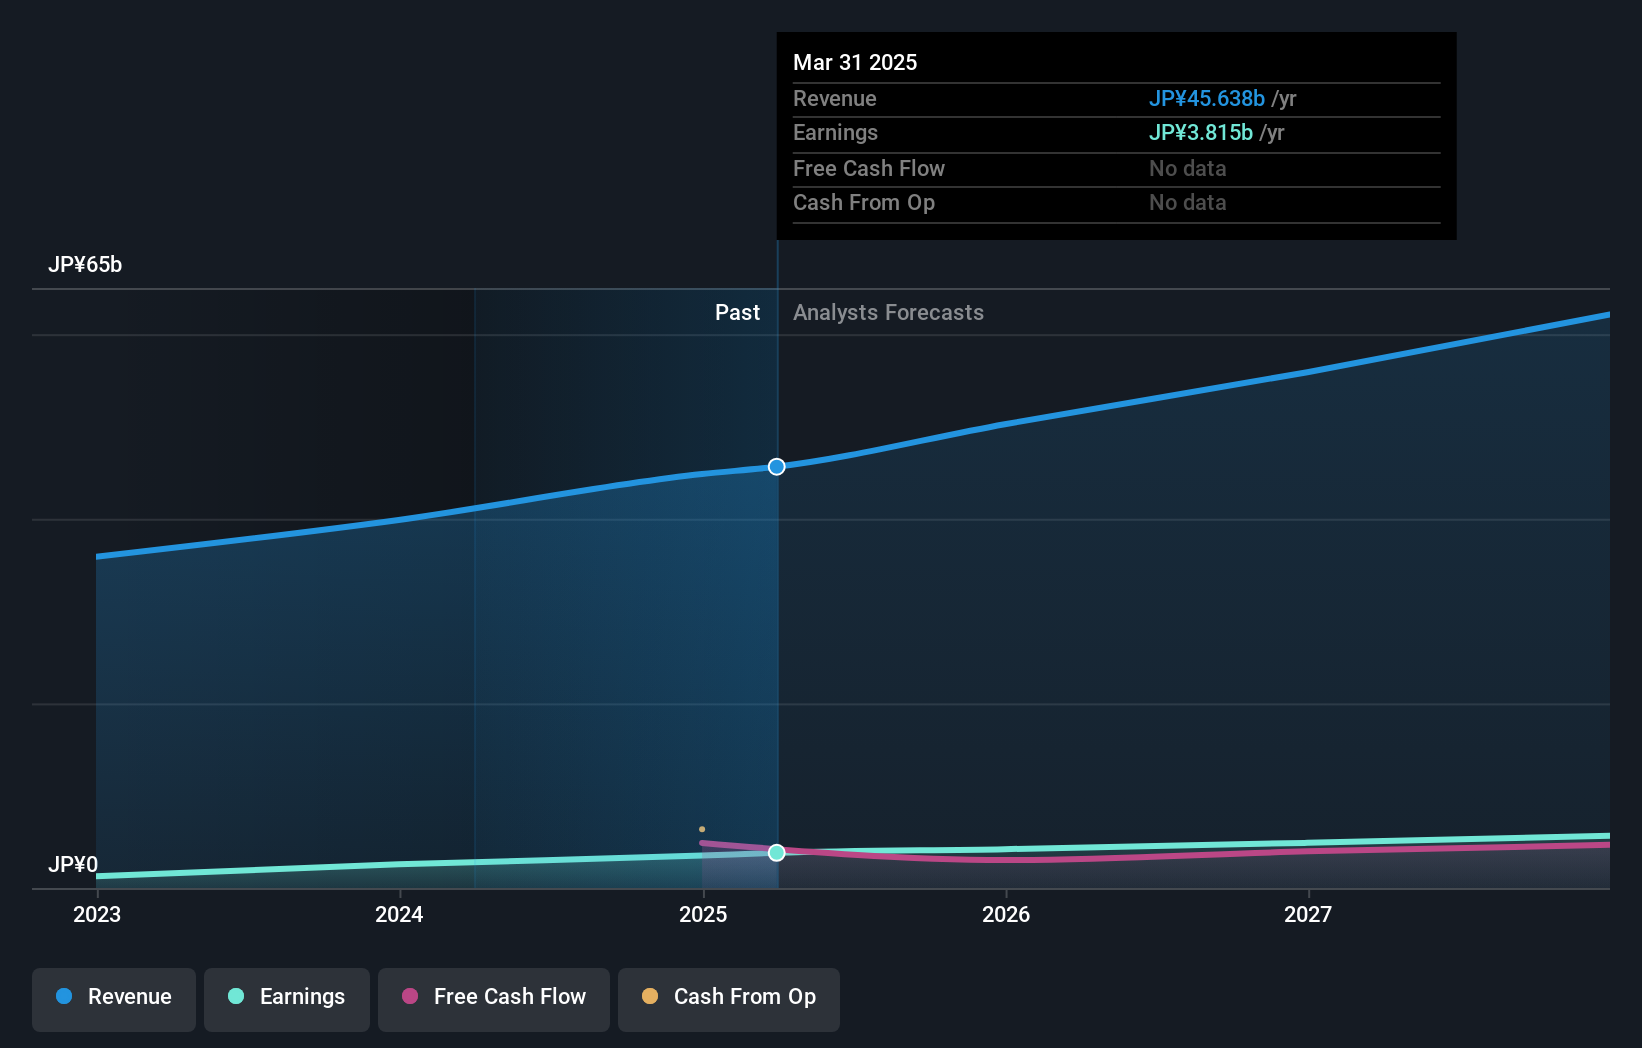
Overview: Intermestic Inc. is a company that specializes in selling eyeglasses and sunglasses in Japan, with a market capitalization of ¥50.43 billion.
Operations: Intermestic generates revenue primarily from its Domestic Business segment, which brought in ¥68.89 billion, while its Overseas Segment contributed ¥880 million.
Intermestic stands out with its earnings growth of 11.7% over the past year, surpassing the Specialty Retail industry average of 9%. Trading at 68.5% below its estimated fair value, it presents a compelling opportunity. The company boasts high-quality earnings and has a satisfactory net debt to equity ratio of 16%, indicating financial stability. Recent sales figures show all store sales increased by 2.2%, while same-store sales rose by 2.9%. With EBIT covering interest payments 48 times over, Intermestic is well-positioned for future growth, forecasting an annual earnings increase of 20.21%.
- Get an in-depth perspective on Intermestic's performance by reading our health report here.
Assess Intermestic's past performance with our detailed historical performance reports.
Noritsu Koki (TSE:7744)
Simply Wall St Value Rating: ★★★★★★
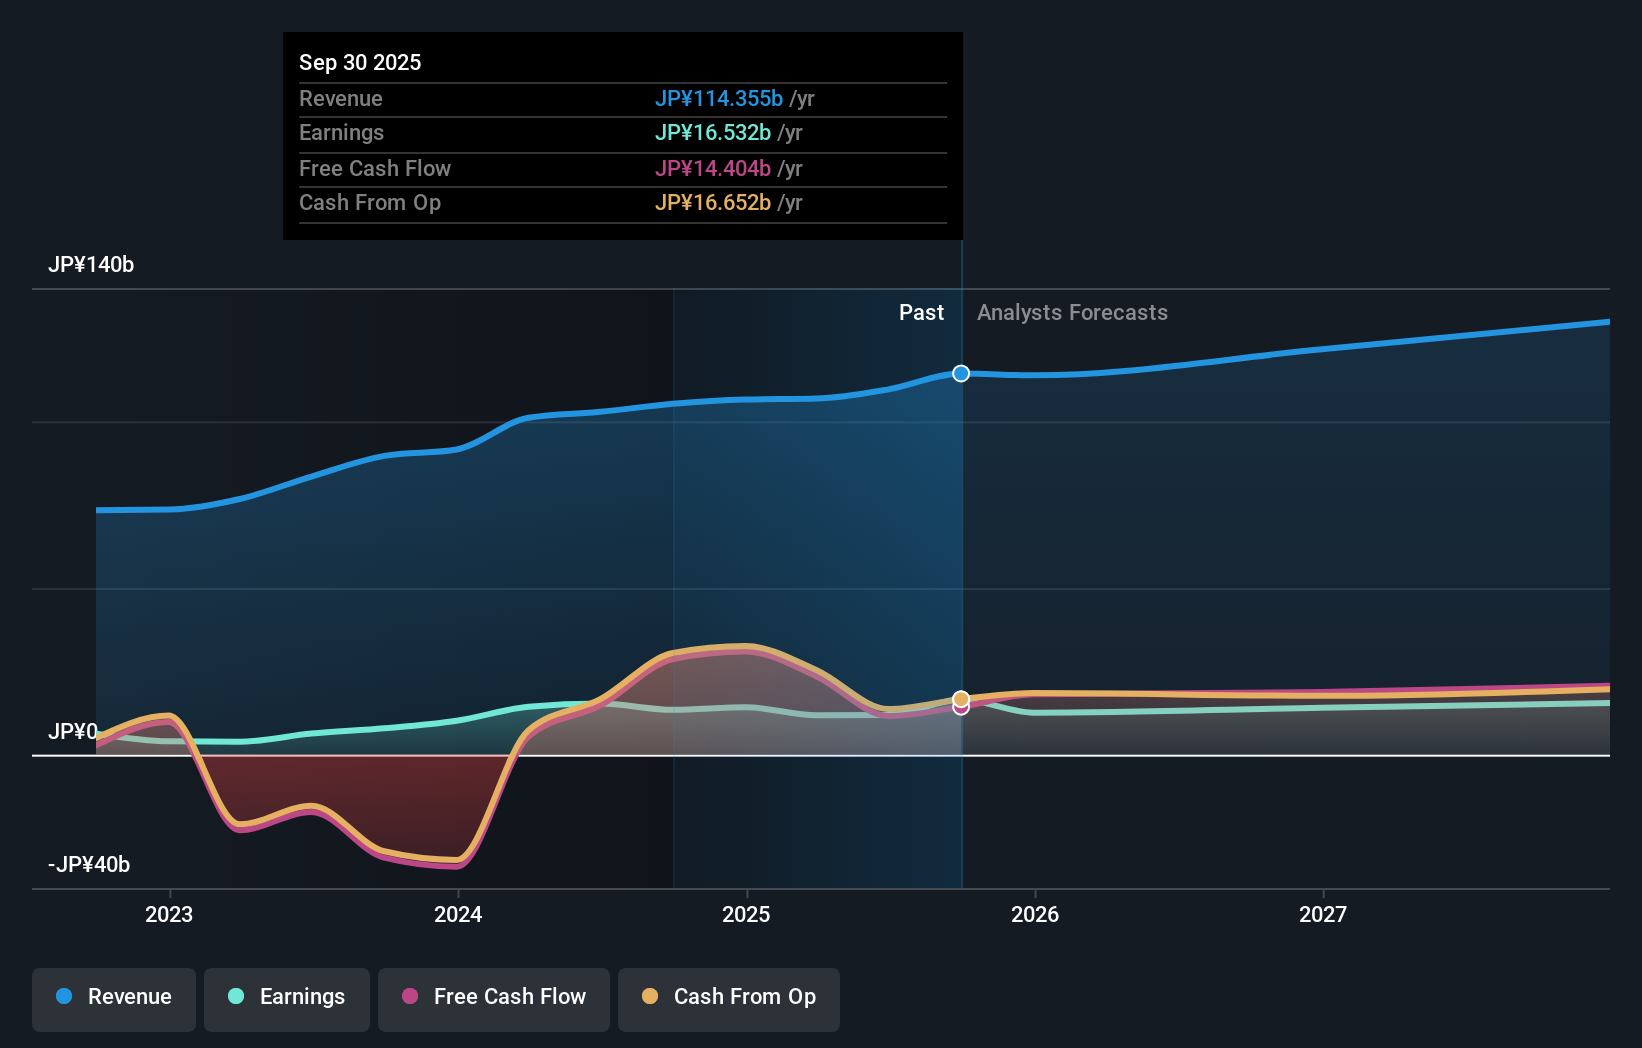
Overview: Noritsu Koki Co., Ltd. is a company that, along with its subsidiaries, engages in the manufacturing and sale of audio equipment and peripheral products across various global markets including Japan, China, the United States, Europe, Central and South America, the Middle East, and Africa; it has a market capitalization of ¥223.05 billion.
Operations: Noritsu Koki generates revenue primarily from manufacturing audio equipment and peripherals, contributing ¥118.48 billion, with parts and materials adding ¥27.43 billion. The company focuses on these segments to drive its financial performance across diverse international markets.
Noritsu Koki is making waves with a notable earnings growth of 74.6% over the past year, outpacing the Leisure industry's 1.5%. The company seems to be in a strong financial position, with its net debt to equity ratio at a satisfactory 5.8%, having reduced from 71.7% over five years to just 33.7%. Their EBIT covers interest payments an impressive 371 times, suggesting robust profitability and high-quality earnings. Recent reports show sales hitting ¥82 billion for half-year ending June 2026, up from ¥56 billion previously, while net income rose to ¥12 billion compared to last year's ¥7 billion.
- Take a closer look at Noritsu Koki's potential here in our health report.
Explore historical data to track Noritsu Koki's performance over time in our Past section.
Taking Advantage
- Investigate our full lineup of 116 Asian Undiscovered Gems With Strong Fundamentals right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com