


Is Vår Energi (OB:VAR) Pricey Following Its 2026 Production Outlook Cut?
Vår Energi (OB:VAR) has just cut its full year 2026 production outlook after unplanned issues at Johan Castberg, the Jotun FPSO and irregular output from the Åsgard area.
Despite the revised 2026 production outlook, Vår Energi’s recent trading tells a different story of investor reaction. The share price is NOK54.16 after a 24.33% 90 day share price return and a 1 year total shareholder return of 89.21%, suggesting momentum is still building.
Scan how other energy producers with recent operational hiccups but strong price momentum are trading by reviewing our list of solid balance sheet and fundamentals (204 results) alongside Vår Energi’s latest moves.
Vår Energi has rallied strongly even as 2026 production expectations have been revised lower. The key question now is straightforward: has the rerating already done the heavy lifting, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 1% Overvalued
Against a narrative fair value of NOK53.84 and a last close of NOK54.16, Vår Energi is framed as slightly rich, with the core story hinging on how long its project pipeline can support cash generation before mature assets start to weigh more heavily.
Heavy reliance on mature North Sea assets, despite current growth, may lead to natural production decline post-2030. This would require significant capital expenditures or new discoveries to sustain output and future cash flow. Persistent industry-wide decommissioning obligations as infrastructure ages will likely cause rising abandonment costs. This could burden free cash flow and potentially impact net margins and dividends over time.
See why 52 investors see Vår Energi as 1% overvalued.
Result: Fair Value of NOK53.84 (OVERVALUED)
Still, a faster than expected decline from mature North Sea fields or rising decommissioning and climate related costs could quickly challenge the current Vår Energi narrative.
Find out about the key risks to this Vår Energi narrative.
Another View: Vår Energi Through The P/E Lens
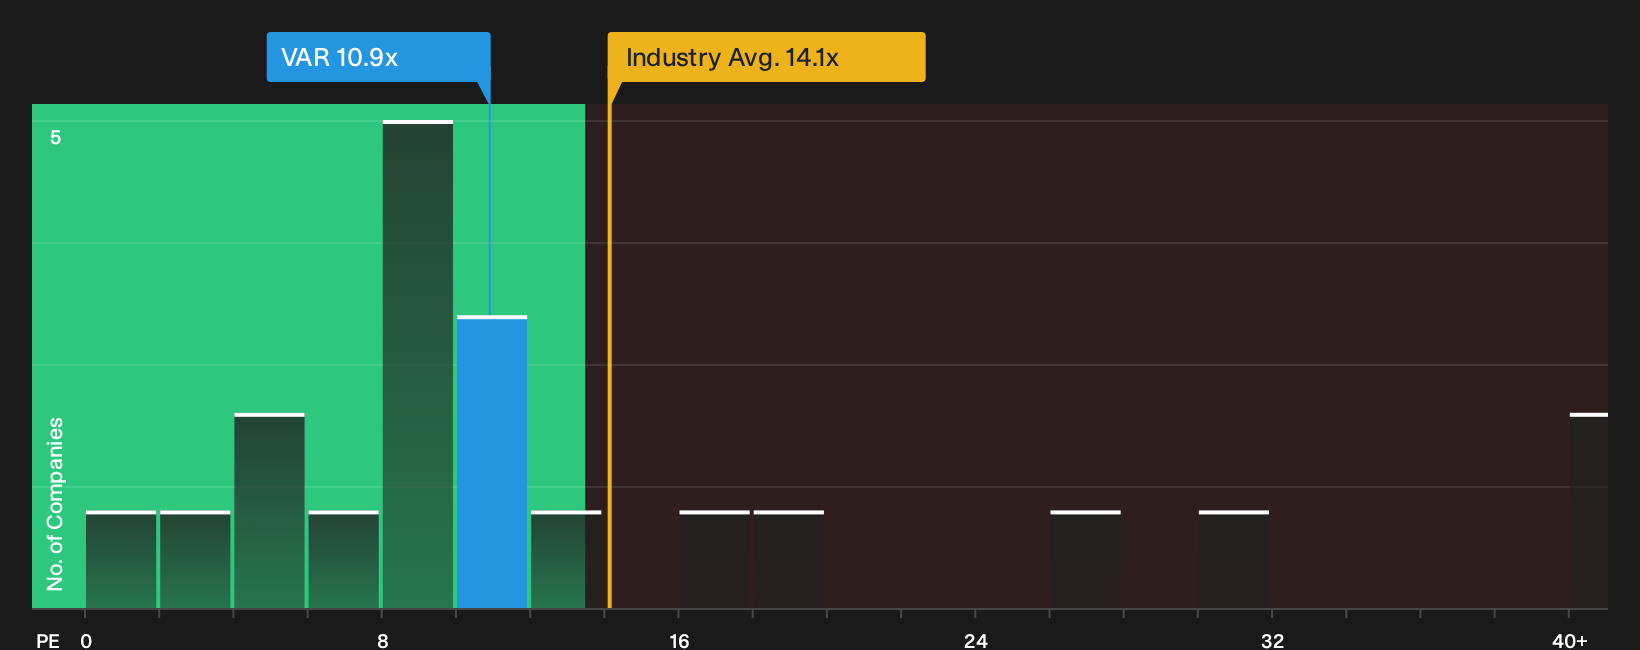
The SWS checks using the P/E ratio paint a different picture for Vår Energi. At 10.9x earnings, the stock trades well below both peer levels at 23.4x and the wider European Oil and Gas group at 14.1x. Yet it sits above a fair ratio of 8x, which hints at some valuation risk if sentiment cools.
For anyone weighing the gap between current pricing, peers and that fair ratio, the granular breakdown of this multiple helps clarify whether the risk or the opportunity feels larger for their own approach. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and unease around Vår Energi feels familiar, treat it as a prompt to check the numbers yourself and move quickly while sentiment is still forming. To weigh the potential upside against the downside risks, start with the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Vår Energi?
Do not stop with Vår Energi alone. Use this momentum as a spark, widen your watchlist, and give yourself more high quality options to compare.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (204 results) that highlight businesses built to handle tougher conditions.
- Hunt for potential mispricings by checking the 185 high quality undervalued stocks that match strong fundamentals with prices that may not fully reflect them yet.
- Build a cash flow focused shortlist by reviewing the 223 dividend fortresses that combine higher yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com