


Our Pick Of The Best Growth Stocks In October 2026
AI driven investment is keeping global growth forecasts afloat, even as the IMF flags record budget gaps and rising debt risks. That mix of strong tech spending and fragile public finances puts extra focus on companies that can grow earnings from their own operations and still keep their balance sheets in decent shape. This piece highlights three such high growth, financially solid stocks from our screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses that still keep their finances in check. However, if you want the standouts, these 487 best high growth potential stocks are the most outstanding.
CXMT (SHSE:688825)
CXMT Corporation is a Hefei based memory chip producer that designs, manufactures, and sells DRAM products such as DDR4, DDR5, LPDDR4X, and LPDDR5/5X for servers, phones, PCs, and smart cars, aligning closely with the screener’s focus on earnings driven by higher performance memory demand. CXMT is valued at about CN¥3,189.9b.
CXMT fits the healthy high growth potential theme through forecast earnings expansion of about 37.5% a year and a recent swing to profitability on CN¥150,310.08 million of first half 2026 revenue and CN¥77,605.23 million of net income. This upside story still hinges on how one unseen pressure shapes future DRAM pricing power.
That pricing wildcard is exactly why the DCF valuation analysis for CXMT can help you see whether CXMT’s current expectations already account for the next leg of the cycle.
Ubtech Robotics (SEHK:9880)
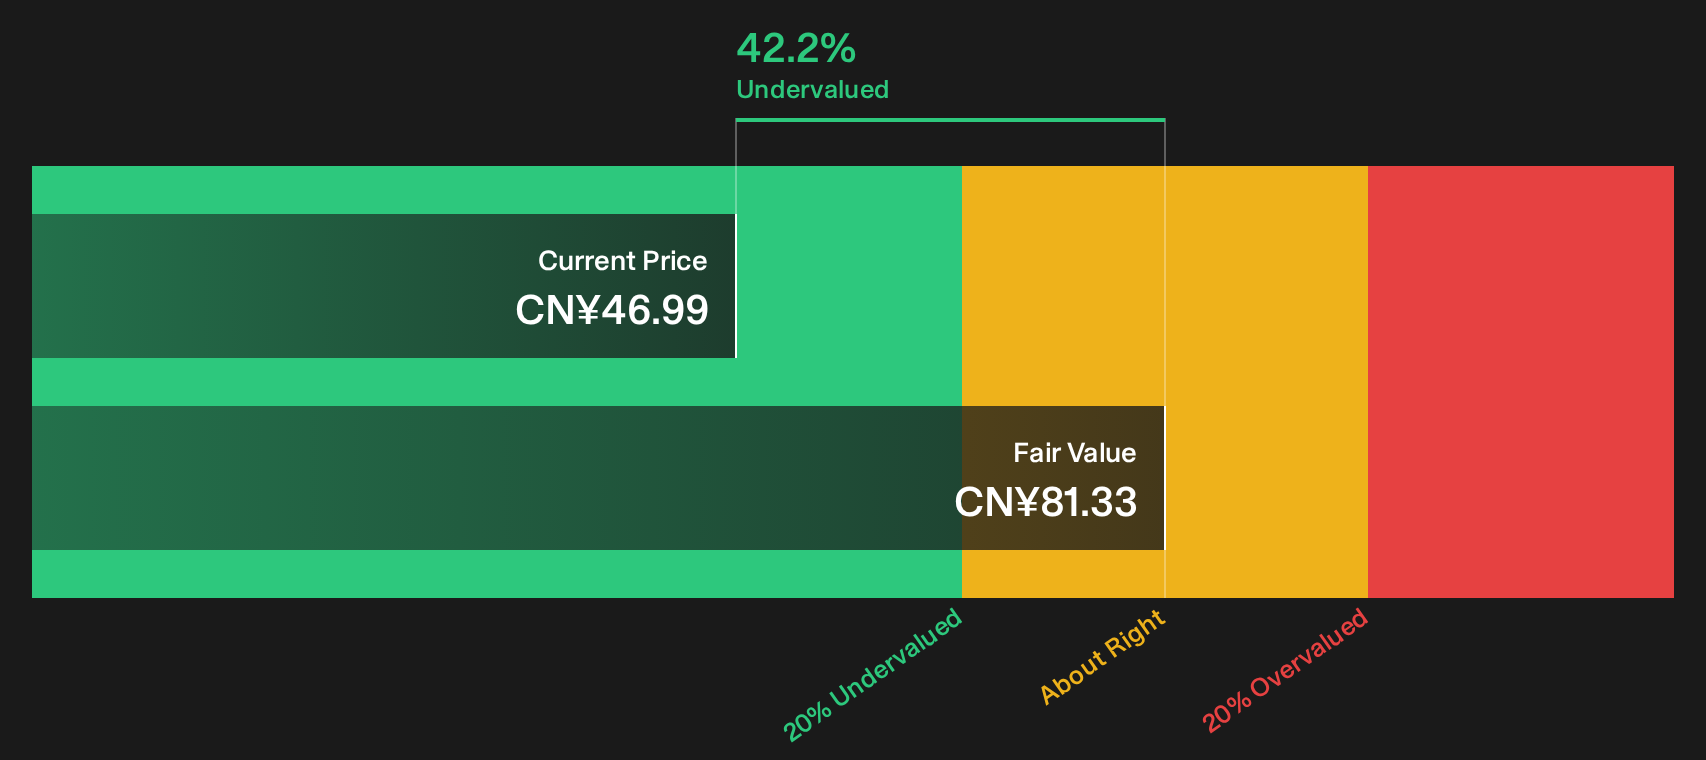
Ubtech Robotics builds humanoid and commercial service robots, along with unmanned logistics systems that directly tie into the screener’s high earnings growth focus. It reported CNY 2.1 billion from Mainland China and CNY 543 million from Hong Kong and overseas. The business has a market value of about HK$33.9 billion.
Sales reached CNY 1,269.13 million for the first half of 2026, with the loss narrowing to CNY 311.48 million. Analysts expect earnings to grow about 121.25% a year over the next three years, and that forecast hinges on how efficiently Ubtech Robotics turns more robots and logistics contracts into better margins if a single leverage point in its cost structure shifts.
If that leverage point matters to you, the analysis report for Ubtech Robotics shows where Ubtech Robotics could accelerate or stall if contract volumes and costs decouple.

Technoprobe (BIT:TPRO)
Technoprobe designs and builds probe cards and test interfaces that help chip makers qualify advanced devices for 5G, AI, and automotive use, placing it squarely in the Healthy high growth potential theme. It generated about €766.6 million from semiconductor equipment and services and is valued at roughly €20.2b.
For the Healthy high growth potential screen, Technoprobe matters because its probe cards sit directly in the path of growing chip complexity, and that testing role underpins both its earnings profile and the attention it is getting from analysts right now.
"Acceleration of AI data center investment, with GPUs, CPUs and custom AI ASICs representing more than half of Technoprobe revenues, points to sustained demand for high performance probe cards that can support complex devices and longer test times."
What happens to that earnings trajectory depends on how one carefully watched capacity build plays through margins over the next phase of growth.
If that capacity build is what you are watching, the full narrative for Technoprobe maps how Technoprobe’s test footprint, pricing power and capital choices could compound or stall margins next.

Seeking Fresh Alternatives Before They Fly
Markets move quickly and potential opportunities can shift from under the radar to fully priced while investors hesitate. Review these fresh breakout ideas before the crowd catches up and consider them promptly.
- Target dependable income streams by reviewing 223 dividend fortresses that aim to keep cash returns flowing even when prices swing.
- Explore the buildout of next generation energy by scanning 16 nuclear energy infrastructure stocks supporting power infrastructure while it is still relatively under the radar.
- Follow developments in automation by tracking 91 robotics and automation stocks as factories, warehouses, and services upgrade at speed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com