


Amazon Isn’t Done Spending on AI: How a $7B Acquisition Could Help Take AMZN Stock Higher
Amazon (AMZN) is considering another multibillion-dollar investment in artificial intelligence, according to a published report.
According to The Wall Street Journal, Amazon is in talks to acquire Decart, an artificial intelligence startup, for approximately $7 billion. The potential deal would add another substantial commitment to Amazon's AI ambitions as the company competes with Microsoft (MSFT), Alphabet (GOOG) (GOOGL), and other technology giants.
But there's an important distinction here. Amazon has already committed billions of dollars to AI infrastructure and partnerships. Buying a startup would give it more direct control over technology and talent that could help it develop new products.
About Amazon Stock
Amazon has been pouring money into artificial intelligence, particularly through Amazon Web Services (AWS), its cloud computing business. AWS provides the computing infrastructure that companies use to develop and operate AI applications, putting Amazon in direct competition with Microsoft's Azure and Alphabet's Google Cloud.
Amazon also has a major relationship with Anthropic, the developer of the Claude family of AI models. The partnership gives AWS a prominent AI customer while supporting demand for Amazon's custom-designed Trainium chips.
A potential Decart acquisition would represent a different approach. Rather than supplying the computing power behind another company's AI products, Amazon could bring additional AI development capabilities directly into its own business.
Decart develops software that makes it easier for developers to switch between different AI chips. That's important for Amazon, which is developing its own Trainium processors to compete with Nvidia (NVDA). Amazon reportedly gave Decart early access to its chips in 2025, so the companies already have a relationship. Acquiring Decart could help Amazon make its processors more attractive to AI developers who don't want to be locked into one company's hardware.
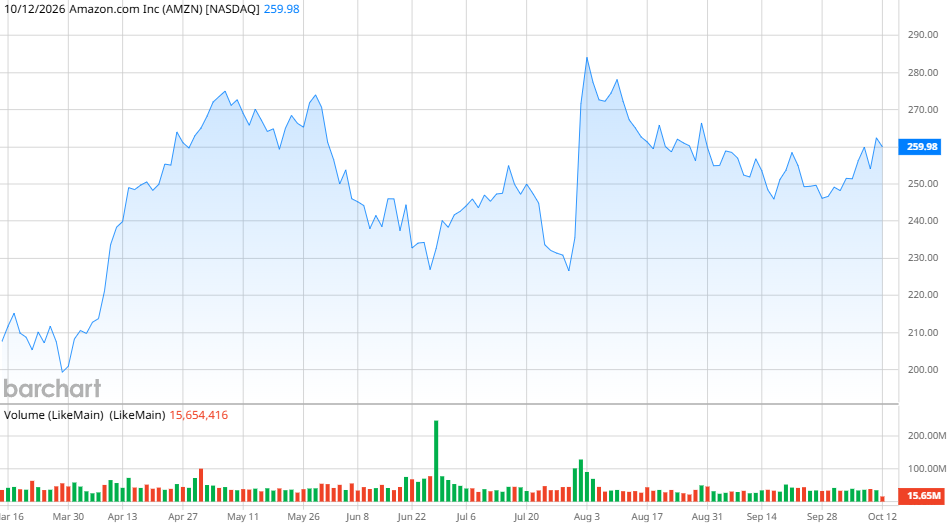
AMZN stock has been up 14% so far this year and 19% in the past 12 months, which roughly mimics the performance of the S&P 500 ($SPX). The stock has been bolstered through the company’s success in building its AI business, indicating that investors are more than willing to forgive the company’s ambitious spending plans as long as it delivers returns.
The company currently has a market cap of $2.8 trillion.
Beats on Earnings
Amazon’s earnings report for the second quarter was nothing short of outstanding. Revenue was $200.6 billion, up from $167.7 billion a year ago. Sales in North America were up 16% to $116.2 billion, while international sales increased 15% to $42.2 billion.
But the biggest percentage increase was with AWS.
“AWS is booming, growing 36.7% year-over-year in Q2—our fastest growth in 18 quarters—and our AI and Chips businesses each eclipsed run rates of more than $25 billion,” CEO Andy Jassy said.
Amazon also recorded $53.39 billion in non-operating income, which the company attributed to its investment in Anthropic. Net income was $62.64 billion, up from $18.16 billion a year ago, and earnings per share were $5.75.
Management issued guidance for the third quarter for revenue in the range of $197 billion and $202 billion, which would be growth between 9% and 12% from a year ago. The company is also expecting operating income between $22.5 billion and $26.5 billion, up from $17.4 billion in the third quarter of 2025.
What Do Analysts Expect From AMZN Stock?
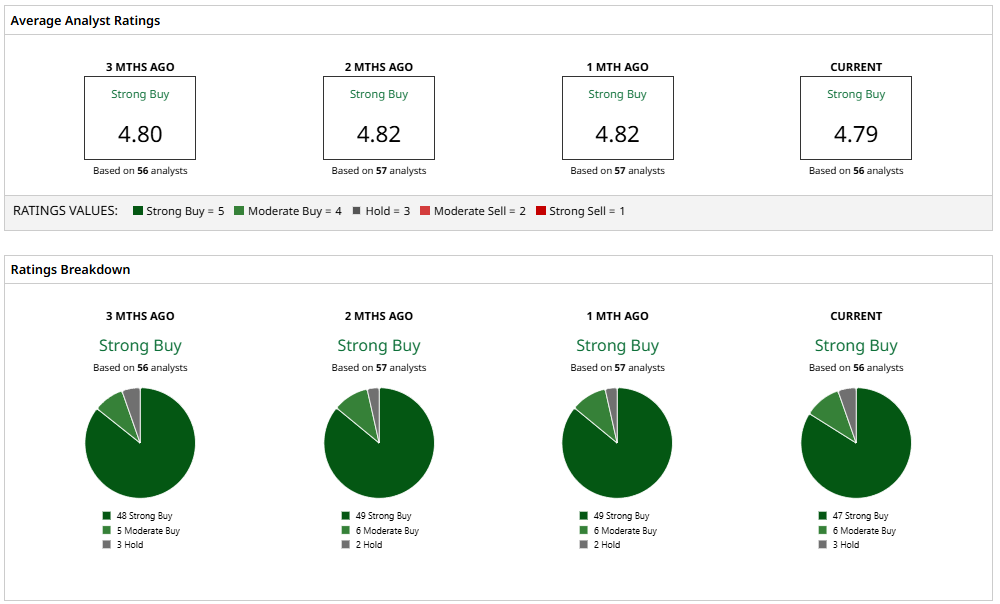
Sentiment surrounding AMZN stock has remained bullish, and there’s nothing in Amazon’s current situation that has changed that. Fifty-three of 56 analysts surveyed by Barchart have “Buy” ratings on the stock, with the other three suggesting shareholders hold. The mean price target of $328.56 represents a potential upside of 29%.
Amazon isn’t afraid to invest in itself to gain an advantage in the AI race. The company has the resources to make substantial investments in AI while continuing to operate its established e-commerce and cloud businesses. A Decart acquisition could give it another way to develop AI products rather than relying entirely on outside partners.
The price tag would be substantial, but Amazon has repeatedly demonstrated its willingness to spend heavily when it sees an opportunity to build a business for the long haul. For investors who believe AI will drive future demand for computing and digital services, that's a compelling reason to keep Amazon on the radar.
On the date of publication, Patrick Sanders had a position in: NVDA . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.