


Realty Income (O) Stock May Look Fully Priced As Europe Expansion Picks Up
Realty Income has delivered a 27.3% gain over the past three years, helped by steady rent streams and a recognisable monthly dividend profile, which puts fresh attention on what investors are paying for each dollar of its earnings today. With expansion in Europe picking up and the share price recently at US$54.70, the live question is whether that current tag lines up with the underlying profit power of the business.
- The 27.3% return over three years puts real money on the line for anyone asking whether the recent share performance still matches the earnings Realty Income generates.
- The new €528 million joint venture with KKR in UK and European retail parks may support expectations for steadier rental income and could influence how investors think about the durability of the trust’s earnings stream.
- The analysts covering Realty Income have run their own numbers. See what analysts think Realty Income's shares could be worth.
The issue now is whether Realty Income’s current share price is adequately supported by the earnings the company produces today.
If you are questioning whether Realty Income's current P/E still makes sense after a 27.3% three year gain and fresh European deals, it can help to compare that earnings lens against 29 high quality undervalued stocks.
Has Realty Income Run Too Far on Earnings?
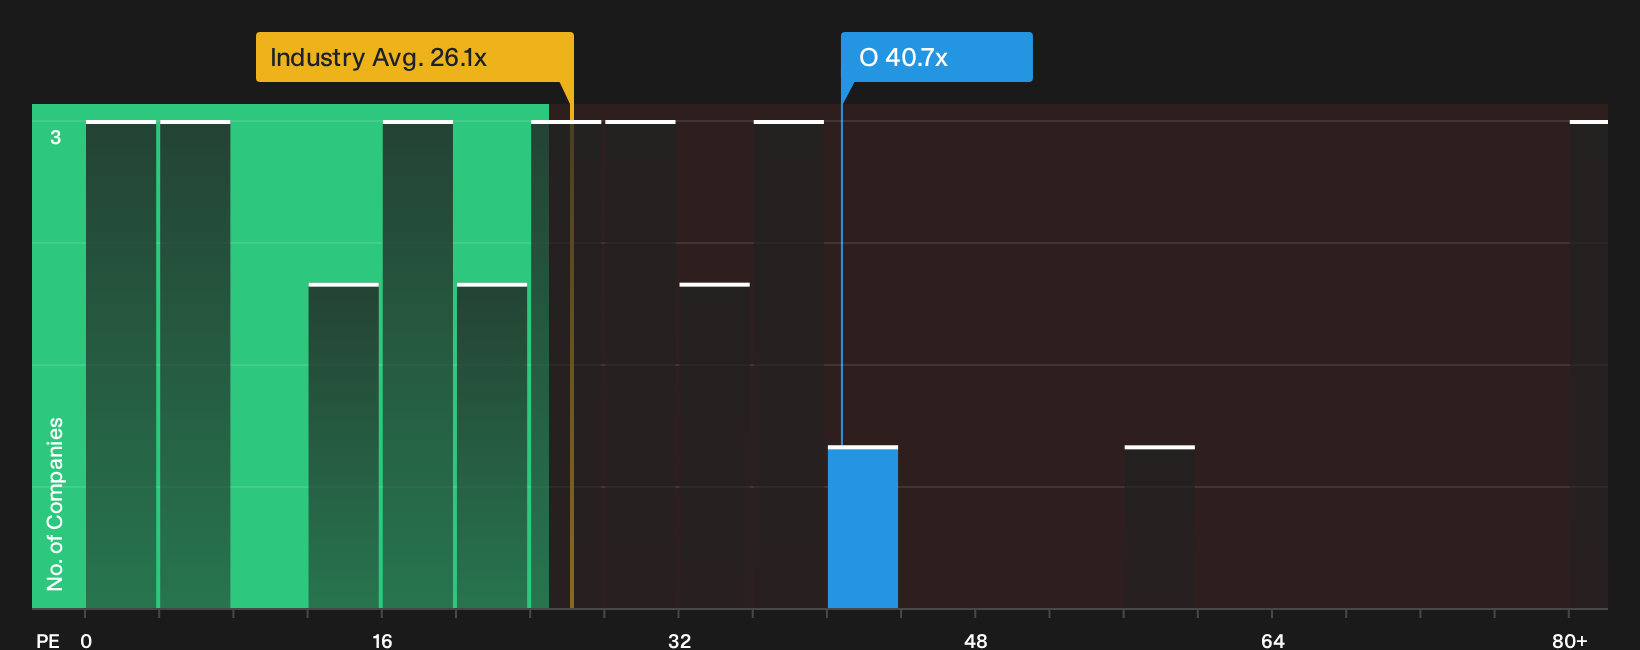
A P/E ratio usually suits a REIT like Realty Income because investors focus heavily on the stream of recurring earnings that supports its dividends. At a current P/E of 40.7x, the stock trades well above the Retail REITs sector average of 26.1x and above the peer group at 25.6x, which means each dollar of Realty Income earnings currently carries a richer price tag than much of its sector.
The Fair Ratio, which reflects what might be expected given Realty Income’s own mix of growth potential, margins, size and risk, sits below that headline multiple, so the shares screen overvalued on this framework. Despite the new €528 million joint venture with KKR in UK and European retail parks adding to the story around long leases and necessity retail tenants, the market is already attaching a premium P/E that assumes those earnings are worth more than a broad REIT benchmark would suggest. Explore the numbers behind Realty Income's P/E valuation.
The Realty Income Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Realty Income pick up where the P/E debate stops by spelling out which growth, margin and earnings paths would need to play out for the stock to appear meaningfully more expensive or cheaper than today’s price on the Community page. Rather than leaving you with a single valuation output, these scenarios describe the future that number relies on so you can see, over time, whether Realty Income's actual progress matches that implied script.
One of the top community narratives on Realty Income: 12% undervalued
"Overall it seems Realty Income is fairly valued or at most a little undervalued at its current market price…"
Discover why this Narrative puts Realty Income at 12% undervalued.
One more Realty Income check that belongs beside the price tag
Share price and earnings only tell part of the story, because the people deciding where Realty Income goes next and how they are rewarded for it can tilt the risk and reward balance in ways the P/E ratio never shows. See who runs Realty Income and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com