


SoundHound AI (SOUN) Stock Trades At A Premium After Its 163% Run
SoundHound AI has seen its share price swing sharply in recent years, which puts fresh attention on a simple question for investors who care about fundamentals: Is the current US$4.97 price tag adequately supported by the company’s sales base?
- Over the past 3 years, SoundHound AI has returned about 163.0%, which makes the link between its share price and underlying revenue power especially important to scrutinise.
- The roll out of SoundHound AI’s real time generative voice assistant in the Kia Sorento in India can shape expectations for how quickly the business turns product wins into meaningful sales and, eventually, operating scale.
- There is a second opinion on SoundHound AI worth weighing. See what analysts think SoundHound AI's shares could be worth.
The issue now is whether SoundHound AI’s recent share price sits on a footing that its current sales and implied sales multiple can reasonably support.
If you are weighing SoundHound AI against other AI focused plays, a focused stock screen is a useful second step in your research, starting with 38 AI small caps.
Does SoundHound AI Look Pricey on Sales?
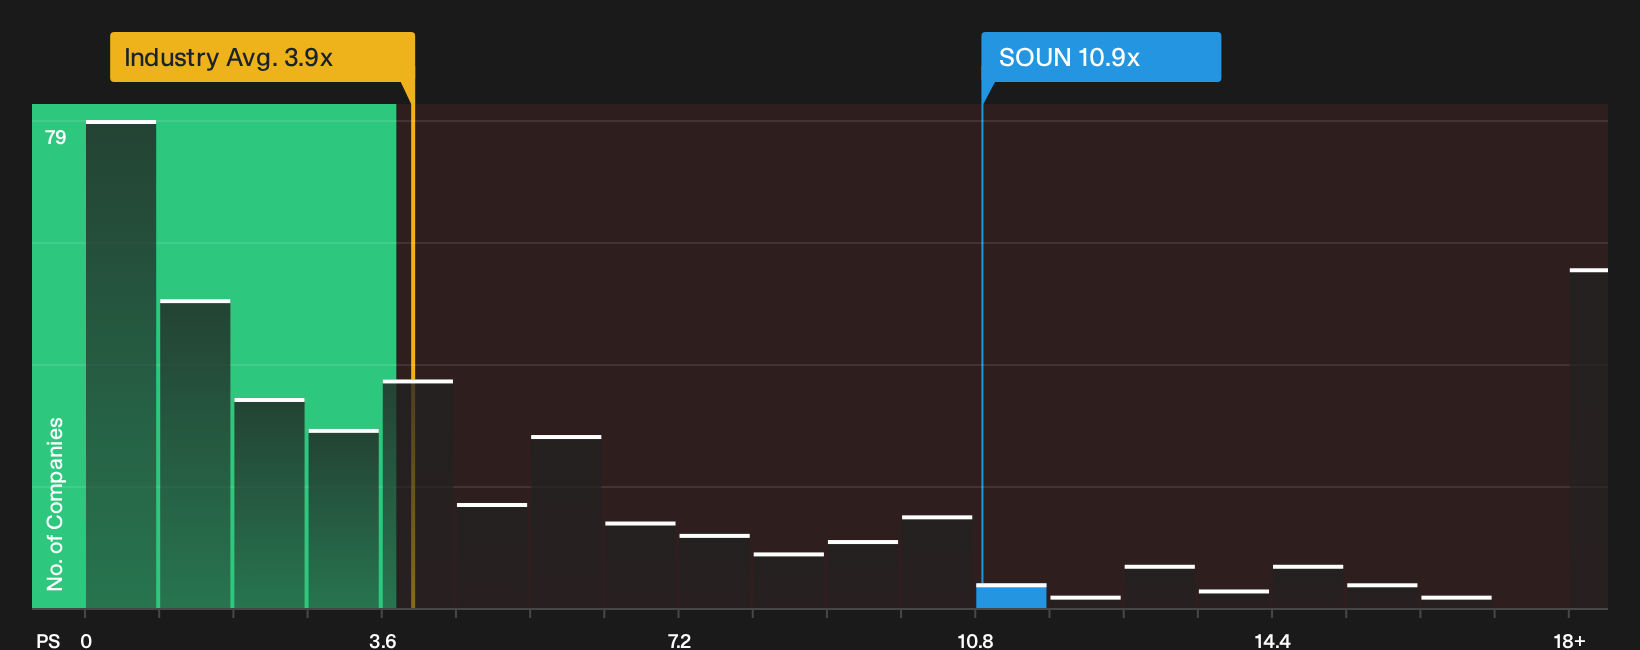
P/S is a useful lens for SoundHound AI because investors are focusing on revenue potential rather than current profits. At around 10.9x P/S, the stock trades well above both the broader Software sector average of about 3.9x and a peer group closer to 7.9x. That gap means every dollar of SoundHound AI’s sales is valued more highly than many software rivals.
Because the Kia Sorento launch in India gives the story a fresh real world proof point, enthusiasm around future contracts may be helping to support this richer multiple. The current P/S ratio still sits above the level suggested by a fair value model that adjusts for growth, margins, scale and risk, which points to the shares screening as overvalued on this metric alone. To judge whether that premium makes sense for you, the key question is how much revenue you think SoundHound AI can realistically build on top of its current deals over time. Explore the numbers behind SoundHound AI's P/S valuation.
The SoundHound AI Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for SoundHound AI pick up where the valuation puzzle leaves off and outline which potential future paths for growth, profitability and earnings would need to occur for the stock to appear materially higher or lower than today’s price. Each scenario links its implied value to a clear view on where SoundHound AI's expansion, margin profile and risk balance could go next, providing a reference point you can revisit as new information emerges.
One of the top community narratives on SoundHound AI: 60% undervalued
"Expansion across multiple industries and partnerships is fueling broader adoption, improved customer diversification, and increased recurring revenue opportunities…"
Discover why this Narrative puts SoundHound AI at 60% undervalued.
For SoundHound AI, the share price is only one piece of the puzzle
Before treating today’s valuation as the full story, it is worth seeing which underlying checks on SoundHound AI have triggered concern and how serious those issues might be for you. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com