


3 Canadian Penny Stocks With Up To 95% Fair Value Upside
The IMF is warning that high government debt and rising bond yields could lead to sharper swings in markets, which puts a spotlight on balance sheets that can handle stress. That is where financially solid Canadian penny stocks come in. You get exposure to early stage growth stories, but with an extra filter on financial health. This article breaks down three of the most compelling ideas from that universe.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with healthier balance sheets. However, if you want the strongest names, these 18 elite penny stocks are at the top of the list.
Cronos Group (TSX:CRON)
Overview: Cronos Group is a cannabinoid producer that grows and sells branded cannabis products like flower, vapes, edibles, and oils worldwide.
Operations: Cronos generates about $179 million from cultivating, manufacturing, and marketing cannabis products, with $105 million from Canada and $52 million from Israel.
Market Cap: CA$1.7b
Cronos Group matters for this Financially Fit Penny Stocks screen because its cannabis brands are tied directly to real, recurring product demand.
"Expanded access to international medical cannabis markets, such as Israel, Germany, and Switzerland, positions Cronos to participate in regulatory reforms and broader global acceptance of cannabinoid-based wellness products, supporting revenue generation and market diversification."
What happens to Cronos Group’s margin profile if a single pressure point in its funding mix or cost base shifts against expectations?
That margin question is exactly what the full narrative for Cronos Group unpacks, showing where Cronos Group’s funding risks are contained and where growth could accelerate if conditions tilt in its favor.

Omai Gold Mines (TSXV:OMG)
Overview: Omai Gold Mines focuses on acquiring and advancing its 100% owned Omai gold project in Guyana, targeting new gold and precious metal deposits.
Operations: Omai Gold Mines currently reports no revenue as it concentrates on exploration and development activities at the Omai prospecting license.
Market Cap: CA$1.5 billion
Omai Gold Mines offers pure exposure to a penny-priced, single-asset gold project that screens well for focused exploration, but it may be challenging to view it as financially strong given its lack of revenue, widening losses and short cash runway. The investment case therefore depends heavily on how the assumptions embedded in its project study ultimately compare with actual outcomes.
Those project assumptions are exactly what the analysis report for Omai Gold Mines unpacks, so you can see where the Omai Gold Mines story could accelerate or stall.

McChip Resources (TSXV:MCS)
Overview: McChip Resources is a Canadian resource investor focused on oil and gas interests, with additional exposure to the Saskatchewan potash project.
Operations: McChip Resources generates about CA$3.6 million from oil and gas exploration and production activities, all sourced within Canada.
Market Cap: CA$4.4 million
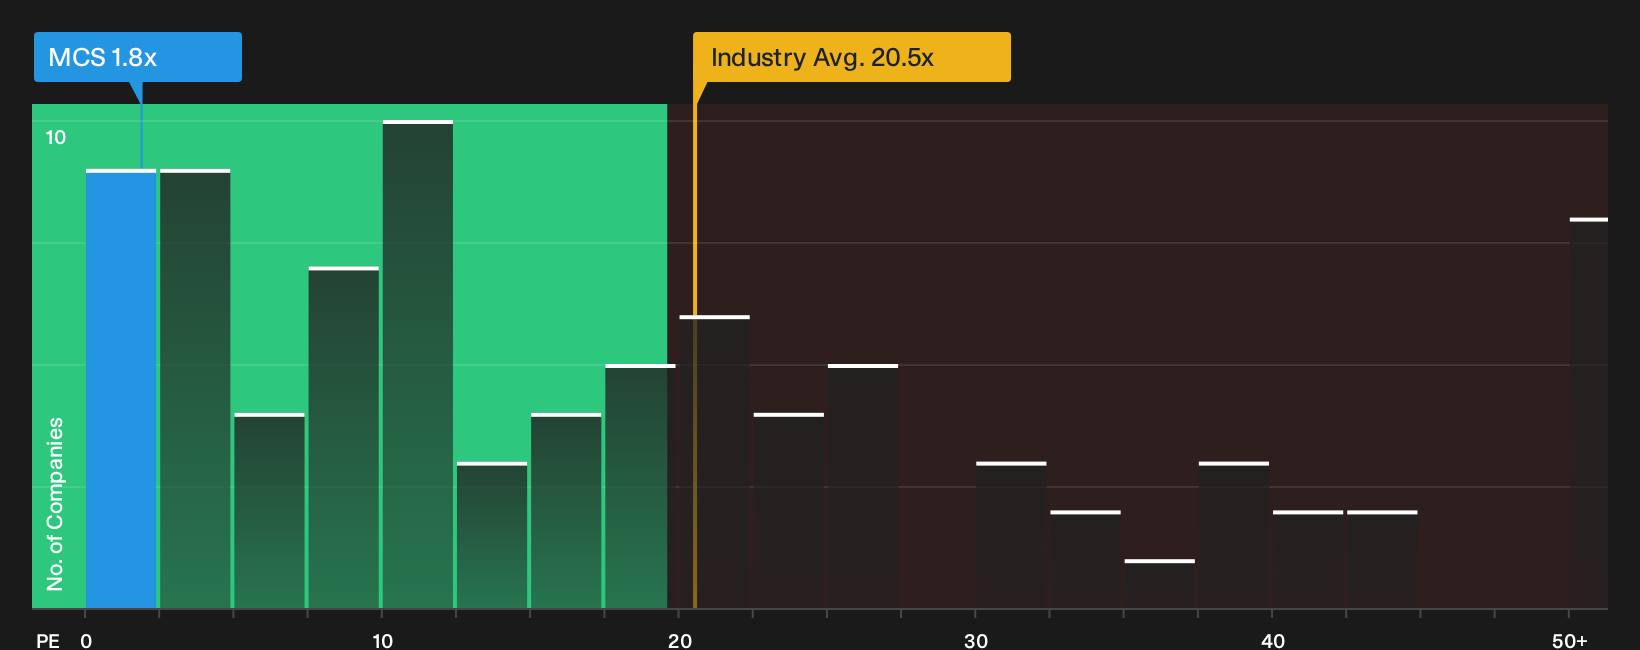
For a Financially Fit Penny Stock screen, McChip Resources combines very small scale with real resource exposure, including the Saskatchewan potash project, plus earnings growth of 80.9% and a P/E of 1.8x against an oil and gas industry closer to 20.5x. This makes the balance between its strong ROE and reliance on external funding hinge on how one unseen pressure on future cash coverage evolves.
That unknown cash coverage pressure point is exactly what the 2 key rewards and 3 important warning signs clarifies, showing where McChip Resources’ tiny valuation could be masking either real resilience or sharp downside.
Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. While attention chases yesterday's headlines, quieter tickers build breakout momentum under the radar for now. Scan what others miss and get in early.
- Spot cash generative outliers early and review the curated 8 high quality undervalued stocks that combine quality fundamentals with pricing that has not yet caught wider momentum.
- Ride long term income trends by screening the curated 3 dividend fortresses that focus on resilience, payout strength, and yields that could matter if rates start dropping.
- Stay ahead of the energy transition and track the curated 16 nuclear energy infrastructure stocks before renewed infrastructure spending gets fully priced in by the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com