


Has Chesnara (LSE:CSN) Become Overvalued After A 94% Climb?
Chesnara’s share price has put in a strong multi year performance, and with the stock closing at £3.29 most recently, the live question is whether that level is supported by the sales the business generates.
- Over the past 5 years the share price has gained 93.9%, so anyone looking at Chesnara today is effectively asking if that climb is matched by what its revenue base can justify.
- The group’s model of managing in force life and pensions books, with a focus on capital efficiency and cash conversion, can shape how much investors are willing to pay for each pound of current and future sales.
- Your read on Chesnara is one view; the desks covering it have another. See what analysts think Chesnara's shares could be worth.
The issue now is whether Chesnara’s current share price is appropriately aligned with its sales when set against the wider industry average.
If you are weighing Chesnara against other options where sales and valuation are front and center, a focused screener built around 7 high quality undervalued stocks can be a useful next step.
Is Chesnara Getting Expensive on Sales?
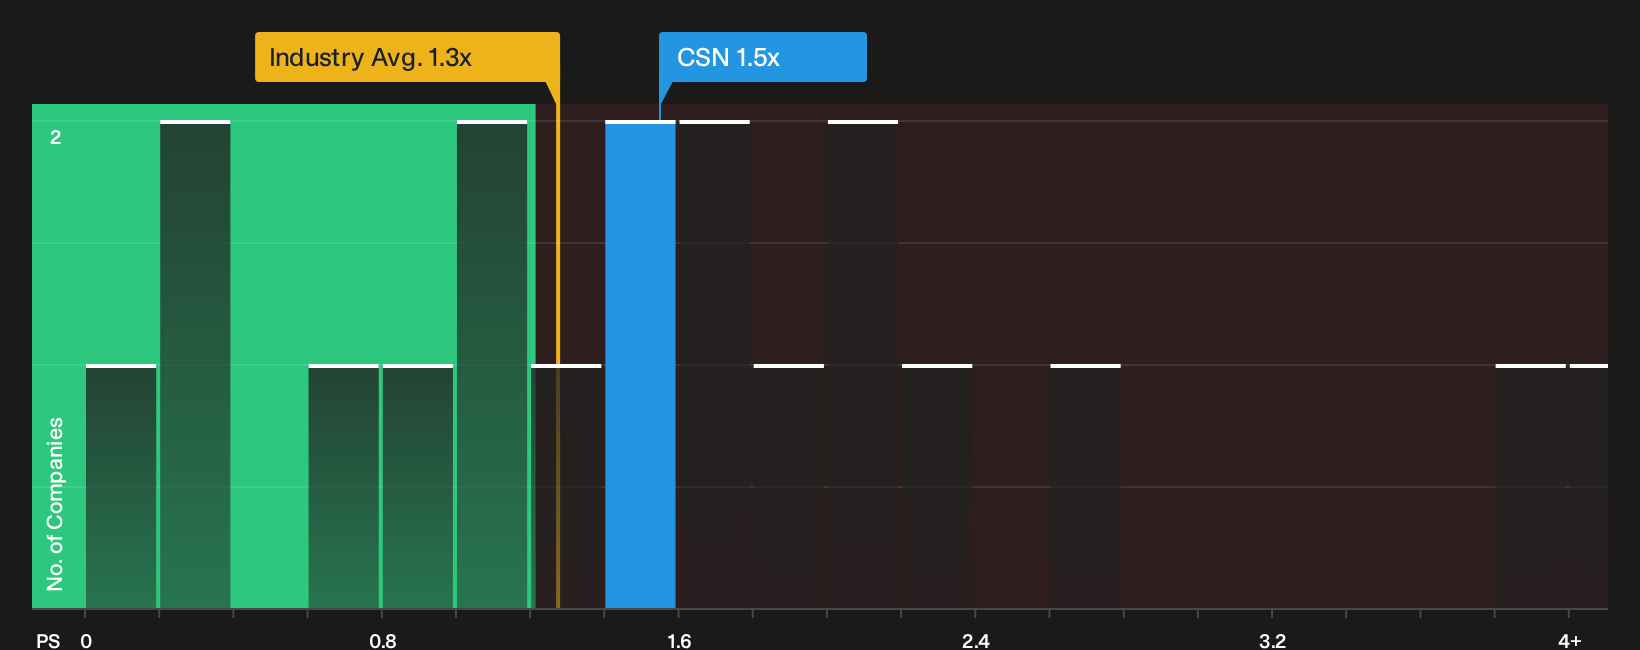
P/S fits Chesnara because investors focus heavily on the value of its existing policy books and the revenue those contracts can reliably throw off. On this measure, Chesnara trades on a P/S ratio of 1.5x, compared with an insurance industry average of about 1.1x. That gap means buyers today are paying a richer price for each pound of Chesnara’s recent sales than for a typical sector peer.
Against a peer average of roughly 1.0x, the stock again screens as overvalued on sales. This suggests the market is assigning a premium to Chesnara’s approach to managing in force life and pensions portfolios. For a holder, the key question is whether the quality and stability of those revenues, plus the group’s focus on capital efficiency and cash generation, justify that higher multiple or leave limited room if expectations slip. Explore the numbers behind Chesnara's P/S valuation.
The Chesnara Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Chesnara's rich P/S leaves off and explain which future paths for growth, profitability and earnings would need to occur for the shares to appear meaningfully higher or lower than today. All of this is hosted on the platform's Community page. Each Narrative links its number to a clear view on how Chesnara's growth, margins and key risks might evolve, which you can revisit as new information becomes available.
A written, number driven view on Chesnara helps turn loose opinions about its P/S premium into clear assumptions. You can then check those assumptions against the company’s actual delivery over time. That kind of explicit roadmap gives you a way to judge whether shifts in Chesnara's growth, margins and execution still line up with the valuation you see on screen.
Share your own Narrative for Chesnara and set out the assumptions behind your valuation.
One more Chesnara check that sits beside the price tag
Before you stop at the P/S multiple, it is worth asking who is steering Chesnara and how their rewards line up with the outcomes you care about as a shareholder. See who runs Chesnara and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com