


Irish Continental Group (LSE:ICGC) Stock Looks Rich On Earnings After 113% Run
Irish Continental Group has delivered a strong 112.5% share price return over the past 5 years, which naturally raises the question of whether its current earnings are enough to support where the stock now trades. With that kind of run already in the rear-view mirror, investors are starting to ask if today’s €6.75 price still lines up with the profits the business is generating.
- A 112.5% gain over 5 years puts long term holders in a comfortable position and also puts more weight on whether Irish Continental Group's earnings justify locking in or extending that exposure.
- The group’s earnings power is closely tied to how efficiently it runs its ferry and freight operations, so future returns may hinge on whether profitability and cash conversion can keep pace with the current share price.
- Irish Continental Group's multiple only means something next to the competition. See how Irish Continental Group's 16.0x P/E compares with its peers.
The issue now is whether Irish Continental Group's current market value is fully supported by its earnings when compared with the wider industry average.
If you want to balance Irish Continental Group’s strong 5 year run with other ideas linked directly to earnings power, a focused screen of 7 high quality undervalued stocks can be a useful next step.
Is Irish Continental Group Getting Expensive on Earnings?
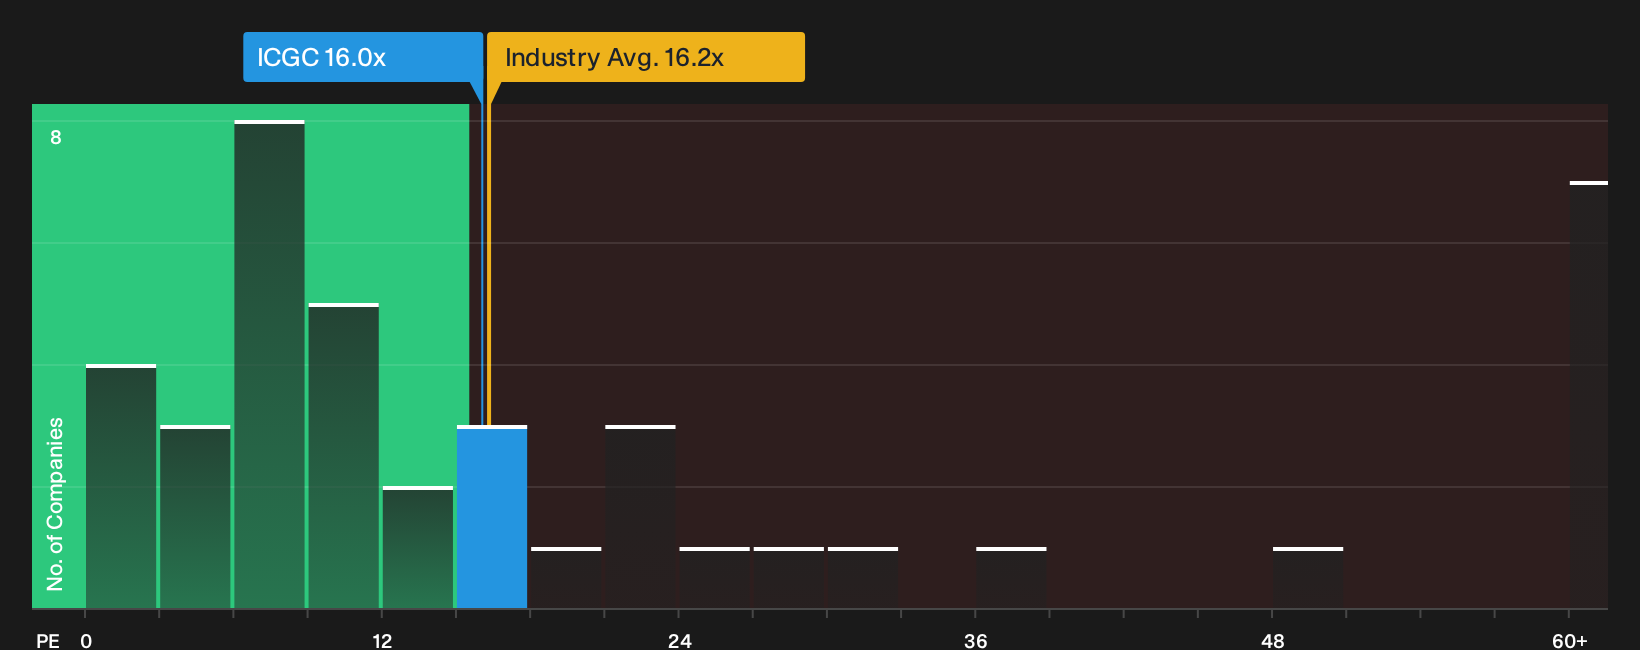
A P/E lens suits Irish Continental Group because earnings are a key anchor for a transport operator with meaningful asset intensity. The stock currently trades on a P/E of 16.0x, which is above the Shipping industry average of about 11.6x and also higher than the peer group level of roughly 12.4x. That gap implies investors are paying a clear premium for each euro of profit the business produces.
This richer multiple suggests the market is already assigning Irish Continental Group a higher quality or resilience premium than the typical shipping operator. Anyone looking at the shares now needs to decide whether the company’s earnings profile, balance sheet and route mix justify paying more than sector and peer benchmarks for the same euro of earnings. Explore the numbers behind Irish Continental Group's P/E valuation.
The Irish Continental Group Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where this valuation question leaves off and spell out what would need to happen to Irish Continental Group's future growth, margins and earnings for the shares to look meaningfully cheaper or richer than the current price. Each one treats Irish Continental Group's fair value as a hypothesis about how the business might progress, which you can then track over time, and they sit on the stock's Community page.
A clear, number driven narrative on Irish Continental Group helps you spell out what earnings, margins and capital use would need to look like for today's P/E premium to keep making sense. It also gives you a concrete yardstick you can revisit as future results reveal whether the business is tracking ahead of, in line with, or behind those expectations.
Share your own Narrative for Irish Continental Group and set out the assumptions behind your valuation.
One more Irish Continental Group check that belongs beside the earnings multiple
The price on Irish Continental Group only tells part of the story, because the people choosing where cash gets spent and how they are rewarded can tilt long term outcomes in subtle ways. See who runs Irish Continental Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com