


BridgeBio Pharma (BBIO) Gains Clinical Momentum, Is The Upside Already Priced In?
BridgeBio Pharma (BBIO) has just packed several important clinical and regulatory updates into a short window, including fresh real-world data for acoramidis in ATTR-CM as well as Phase 3 progress and Priority Review status for encaleret.
BridgeBio Pharma’s recent run of clinical headlines has arrived after a tougher stretch for the ticker, with the share price down 21.8% over the past 90 days and 16.0% year to date. Even so, the 1-year total shareholder return sits at 17.5% and the 3-year total shareholder return is very large, suggesting long-term holders have still seen substantial gains despite fading near term momentum.
Scan how BridgeBio Pharma fits into a wider pipeline story by comparing it with 33 healthcare AI stocks that are also pairing data-heavy clinical programs with targeted therapies in complex diseases.
Bulls see BridgeBio Pharma’s selloff as a mismatch between a broad rare disease portfolio and a falling share price. Bears point to ongoing losses and execution risk. Which side do the current valuation markers lean toward next?
Most Popular Narrative: 163% Overvalued
BridgeBio Pharma last closed at $65.75, while the leading narrative on Simply Wall St assigns a fair value of $25.00. This frames the current quote as richly priced before factoring in any additional clinical upside.
The "BridgeBio Commercial Bonanza" is priced for perfection, treating the upcoming Acoramidis launch as an automatic cash cow while ignoring a brutal multi-front commercial dogfight.
Here is why the market is mispricing the structural hurdles for BBIO:
1. The Pfizer Moat & SG&A Bleed: Outperforming Vyndaqel in a clinical trial does not guarantee market share. Pfizer’s commercial entrenchment in the ATTR-CM space is institutional. For BBIO to compete, marketing and launch expenses will skyrocket, severely depressing free cash flow and delaying true profitability far past consensus timelines.
See why 4 investors see BridgeBio Pharma as 163% overvalued.
According to AnimalDoctorKwon, this valuation view leans heavily on the idea that BridgeBio Pharma is walking into entrenched rare disease franchises that could demand heavy selling and marketing spend just to secure share, which in turn could keep free cash flow under pressure even if top line growth remains strong.
Result: Fair Value of $25.00 (OVERVALUED)
Still, BridgeBio Pharma could see this bearish narrative challenged if acoramidis uptake proves resilient against silencers, or if commercialization spending tracks more tightly than feared.
Find out about the key risks to this BridgeBio Pharma narrative.
Another View: What Our DCF Model Says About BridgeBio Pharma
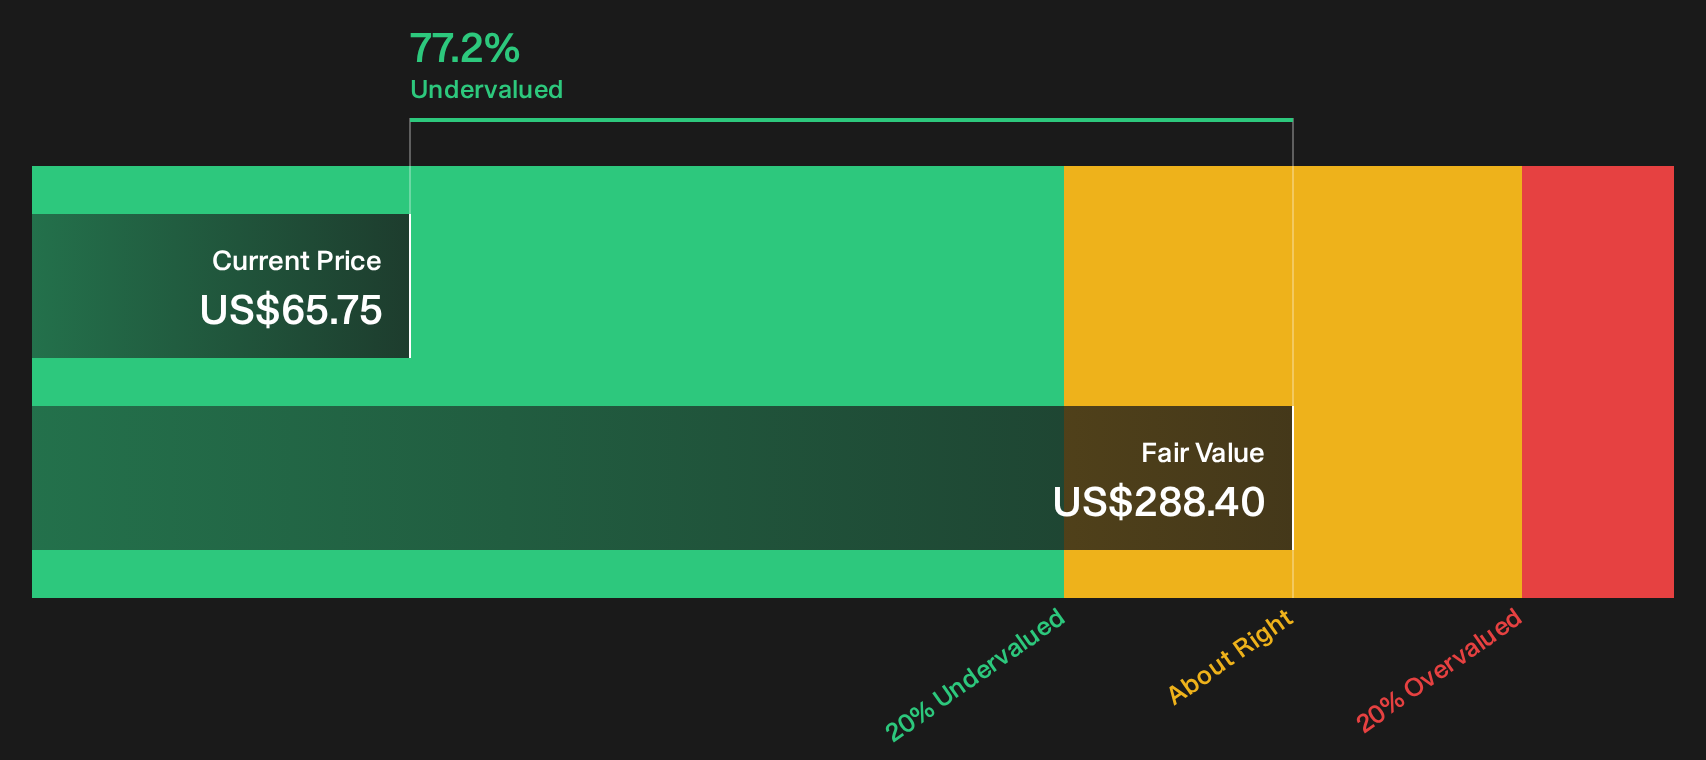
The narrative fair value of $25.00 paints BridgeBio Pharma as expensive, yet our DCF model points in the opposite direction. In this view, BBIO at $65.75 is described as trading 77.2% below an estimated future cash flow value of $288.40, which highlights a very different kind of risk question for investors.
This kind of gap suggests the real debate is less about whether BBIO is rich or cheap, and more about which assumptions around long run cash generation investors trust most and which they treat as optional.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around BridgeBio Pharma can either sharpen your thinking or pull you in opposite directions, so move fast and pressure test the numbers for yourself with 3 key rewards and 1 important warning sign
Ready for more investment ideas beyond BridgeBio Pharma?
If the back and forth around BridgeBio Pharma sharpened your thinking, use that energy to scan for other opportunities before the next move leaves you behind.
- Target potential value shifts by reviewing companies flagged in the 29 high quality undervalued stocks that may trade below what their fundamentals suggest.
- Prioritise resilience and sleep-at-night holdings by focusing on the 31 resilient stocks with low risk scores that score well on financial stability and volatility checks.
- Search for possible future standouts early by scanning the 20 high quality undiscovered gems that combine solid fundamentals with limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com