


Vesuvius (LSE:VSVS) Could Be 7% Undervalued Following Its Recent Rally
Why Vesuvius stock is drawing attention now
Vesuvius (LSE:VSVS) has been attracting fresh interest after a strong month, with the share price moving sharply higher while annual revenue and net income figures give investors more concrete numbers to work with.
Recent trading paints a picture of momentum building for Vesuvius, with a 30-day share price return of 25.22% and a year-to-date share price gain of 15.76%. The 1-year total shareholder return of 29.97% points to steady longer-term progress.
Scan how Vesuvius compares with other industrials showing strong price moves and solid fundamentals by reviewing the hand picked list of solid balance sheet and fundamentals (9 results) in the same bracket.
After a 30 day surge and a share price still sitting below both analyst targets and some fair value estimates, is Vesuvius being mispriced, or is the market simply applying sensible caution to this recovery story?
Most Popular Narrative: 7% Undervalued
Against a last close of £4.63, the most followed narrative pegs Vesuvius at a fair value of about £4.96, so expectations already price in a decent uplift and hinge on how well the underlying growth story holds together.
Vesuvius is experiencing rapid, sustained revenue and profitability growth in India, driven by structural increases in infrastructure and steel demand. The company's large, modern manufacturing footprint, strong management teams, and "India for India" strategy position it to capitalize on this multi-year growth tailwind, with Indian operations now representing higher than average group margins and continuing to expand as a share of total sales.
See why 14 investors see Vesuvius as 7% undervalued.
Result: Fair Value of £4.96 (UNDERVALUED)
Still, the Vesuvius story can unravel if European steel demand stays weak or if lower cost rivals in Asia continue to chip away at pricing power.
Find out about the key risks to this Vesuvius narrative.
Another View: What the P/E Ratio Says About Vesuvius
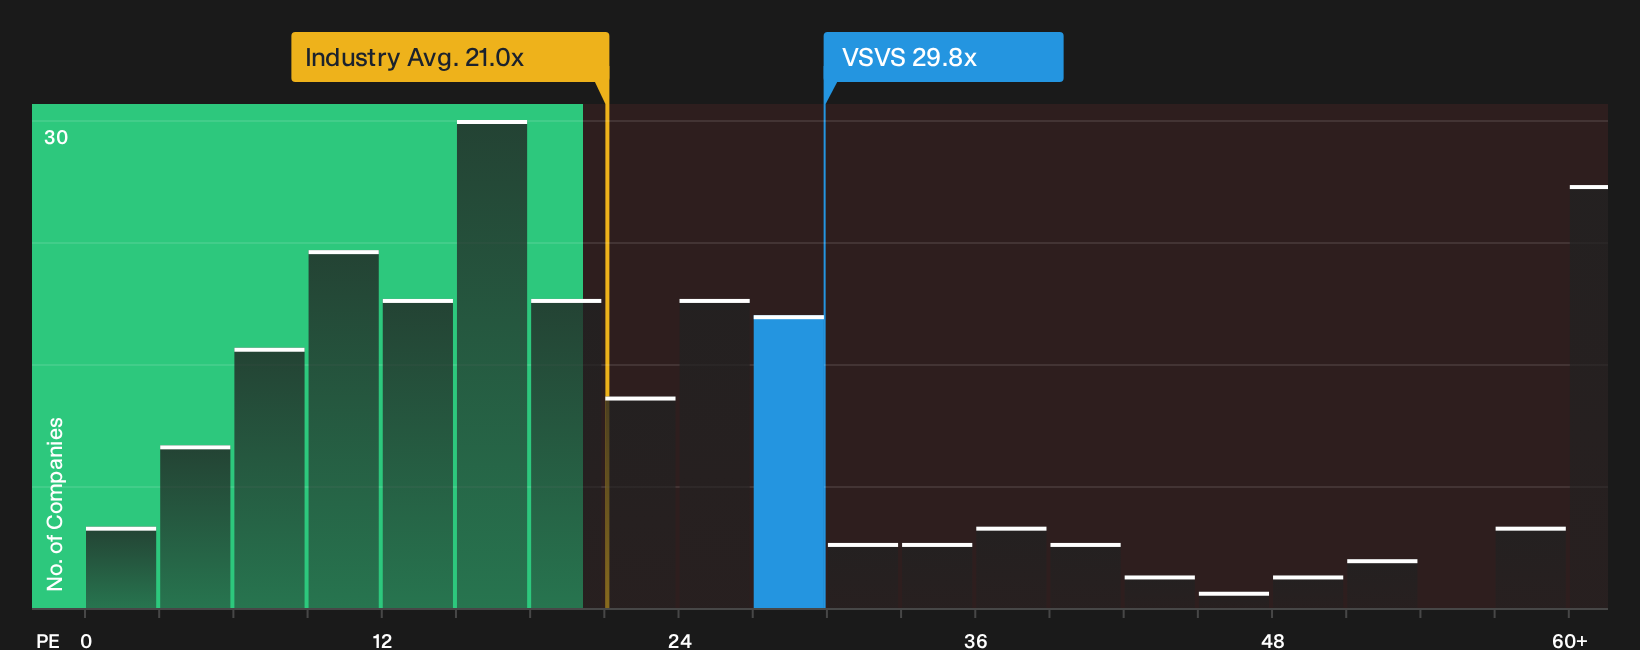
Looking at Vesuvius through a simple P/E lens makes the picture harder to read. The shares trade on 29.8x earnings, above the European Machinery average of 21x, yet below an estimated fair ratio of 35.3x that the market could move toward over time.
This gap implies investors are already paying a richer multiple than the sector, while still leaving room if that fair ratio proves right. The key question is whether current earnings quality, recent profit pressure, and the bid interest justify paying this valuation today or call for a wider margin of safety.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Vesuvius, with both risks and rewards in play, mean the next move is not straightforward, so move quickly and inspect the detail for yourself, then weigh up the 2 key rewards and 4 important warning signs.
Looking for more Vesuvius sized opportunities?
If Vesuvius has caught your eye, do not stop there. Broadening your watchlist across quality ideas can sharpen your next move and reduce blind spots.
- Target potential mispricings by scanning companies flagged as high quality and possibly below fair value through the 7 high quality undervalued stocks.
- Prioritize resilience by using the 4 resilient stocks with low risk scores to spot businesses with steadier profiles that can help balance bumpier holdings.
- Hunt for fresh opportunities before the crowd by checking the 5 high quality undiscovered gems that pair strong fundamentals with relatively low attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com