


What Credicorp (BAP)'s Earnings Beat Streak Means For Shareholders
- Credicorp has recently outperformed earnings expectations in two consecutive quarters, and analysts currently assign the company a positive Earnings ESP of 4.71% ahead of its next results.
- This run of earnings surprises highlights how Credicorp’s business model is converting operational execution into stronger reported profits, rather than sentiment driven optimism.
- We will now explore how Credicorp’s recent earnings outperformance streak could reshape its investment narrative around digital and fee growth.
Compare Credicorp’s earnings momentum with other financials converting execution into profit surprises by scanning our curated list of 29 high quality undervalued stocks.
Credicorp Investment Narrative Recap
To own Credicorp, you need to be comfortable with a Peru centric financial group that is trying to turn digital scale and fee income into durable earnings, while keeping cost of risk and efficiency under control. The recent run of earnings beats supports that execution story in the short term, but does not remove the core exposure to the local economy and regulation.
The key near term swing factor is whether digital platforms like Yape and broader loan demand can keep lifting fee and interest income without pushing bad loans, which sit at 4.1%, materially higher. The biggest risk still sits in Peru specific shocks and any El Niño related stress that could hit about 9% of the loan book.
Recent commentary around El Niño exposure is particularly relevant here, given management has highlighted that roughly 9% of Credicorp’s portfolio is tied to potentially affected clients. That disclosure matters more in light of earnings surprises, because it shows where future provisioning or tighter underwriting could offset some of the upside from better profit delivery.
If weather related impacts materialise, there could be pressure on loan growth, cost of risk and net margins at the same time that digital and fee businesses are helping the group. The investment debate then becomes whether Credicorp’s digital reach, technology spend and efficiency ambitions can absorb that kind of credit hit while still supporting its longer term earnings path.
What Credicorp’s Consensus Numbers Are Really Pricing In
Credicorp’s narrative projects PEN 35.0b revenue and PEN 11.1b earnings by 2029. That profile leans on 16.3% yearly revenue growth and an earnings increase of about PEN 3.7b from PEN 7.4b today.
Analysts tying Credicorp’s digital story to hard numbers are effectively asking you to weigh those targets against Peru specific risk. On one side sit high teens annual top line growth assumptions and a move from PEN 7.4b in earnings today to PEN 11.1b by 2029, even as margins are pencilled in slightly lower at 31.6% compared with 33.1% now. On the other side are the same fault lines already visible in the earnings debate, including political shocks, tax outcomes and any El Niño hit to roughly 9% of the loan book that could lift credit costs just as revenue ambitions rise.
That PEN 11.1b profit target is not a single point either. More optimistic forecasts run as high as PEN 14.0b, which widens the range of possible outcomes and makes your own conviction on Credicorp’s digital and fee growth crucial. If bad debt stays manageable and Peru’s operating backdrop holds together, earnings expansion of roughly PEN 3.7b over the period would lean heavily on fee rich businesses, technology spending discipline and the ability to keep efficiency from drifting too far above guidance.
Valuation assumptions build on the same scaffold. To line up with the current consensus, you would need to be comfortable with revenues being around PEN 35.0b and earnings at PEN 11.1b in 2029, alongside a P/E of 14.0x that is slightly below the 14.1x multiple referenced today but above the 11.5x level cited for US banks. Those inputs sit behind a US$427.48 price target versus a current share price of US$380.38, with analyst views spread widely between US$219.0 and US$482.0. This underscores how much views differ on the balance between Peru risk and Credicorp’s digital scale up.
For readers, the key task is not to accept those PEN 35.0b and PEN 11.1b figures at face value. The more useful exercise is to ask how much earnings sensitivity you see to Peru’s policy cycle, to any El Niño related stress and to potential shifts in the P/E multiple if sentiment toward local financials cools. Credicorp’s recent earnings surprises show what strong execution can look like, but the consensus path out to 2029 still rests on moving parts that reward a closer look before treating the current price as either a bargain or a warning sign.
Uncover why Credicorp's fair value indicates a 12% potential upside to its current price that may not last much longer.
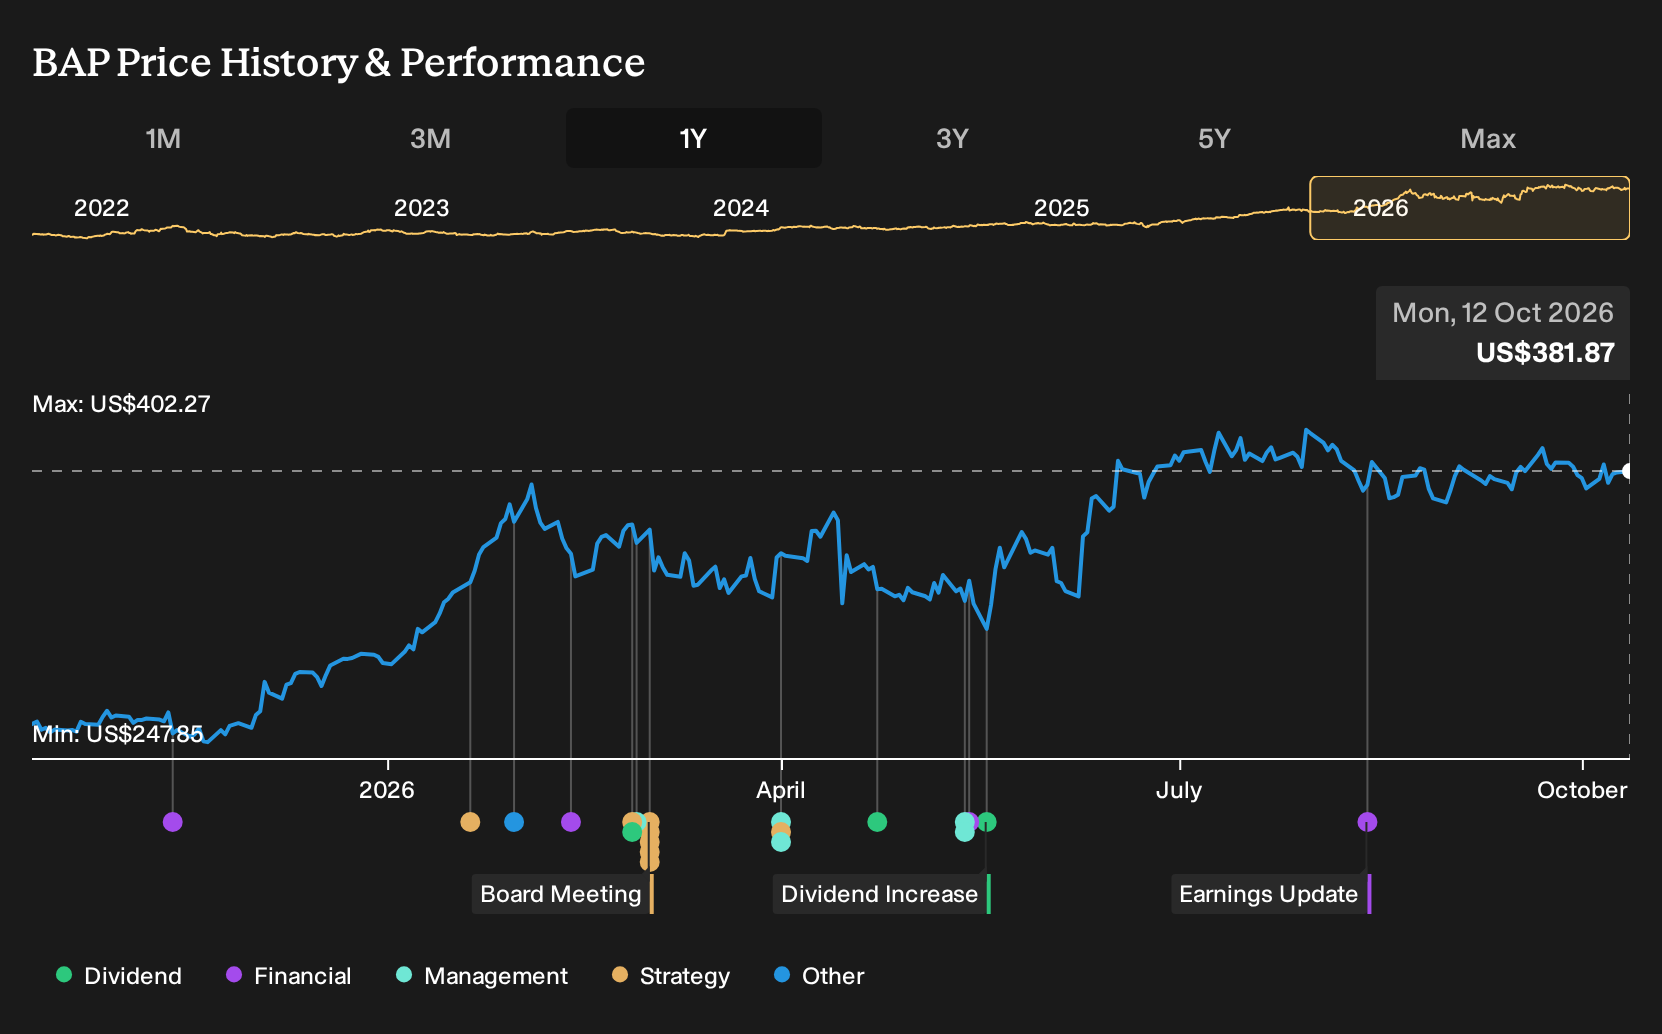
Exploring Other Perspectives
One alternate view leans hard into Credicorp’s digital upside. The most optimistic analysts were already pencilling in PEN 34.6b of revenue and PEN 13.6b of earnings by 2029, well above the PEN 35.0b and PEN 11.1b consensus mix. That rosier digital monetization story may shift again once the latest earnings surprise is fully digested.
Explore 2 other Credicorp fair value estimates, including one that suggests there may be as much as 25% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Go with your instincts.
- A great starting point for your Credicorp research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Credicorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Credicorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Credicorp?
If Credicorp’s story has sharpened your thinking, use that same framework across the wider market by screening for other companies that match your risk and return preferences.
- For investors who prize resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that filters out weaker financial profiles.
- If your focus is on resilient performers with lower risk characteristics, narrow your search with a 32 resilient stocks with low risk scores that screens for companies with more measured risk scores.
- When you want to hunt for potential future leaders before they are widely followed, scan a 20 high quality undiscovered gems that surfaces under-the-radar businesses with strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com