


What EZCORP Doubters Got Wrong
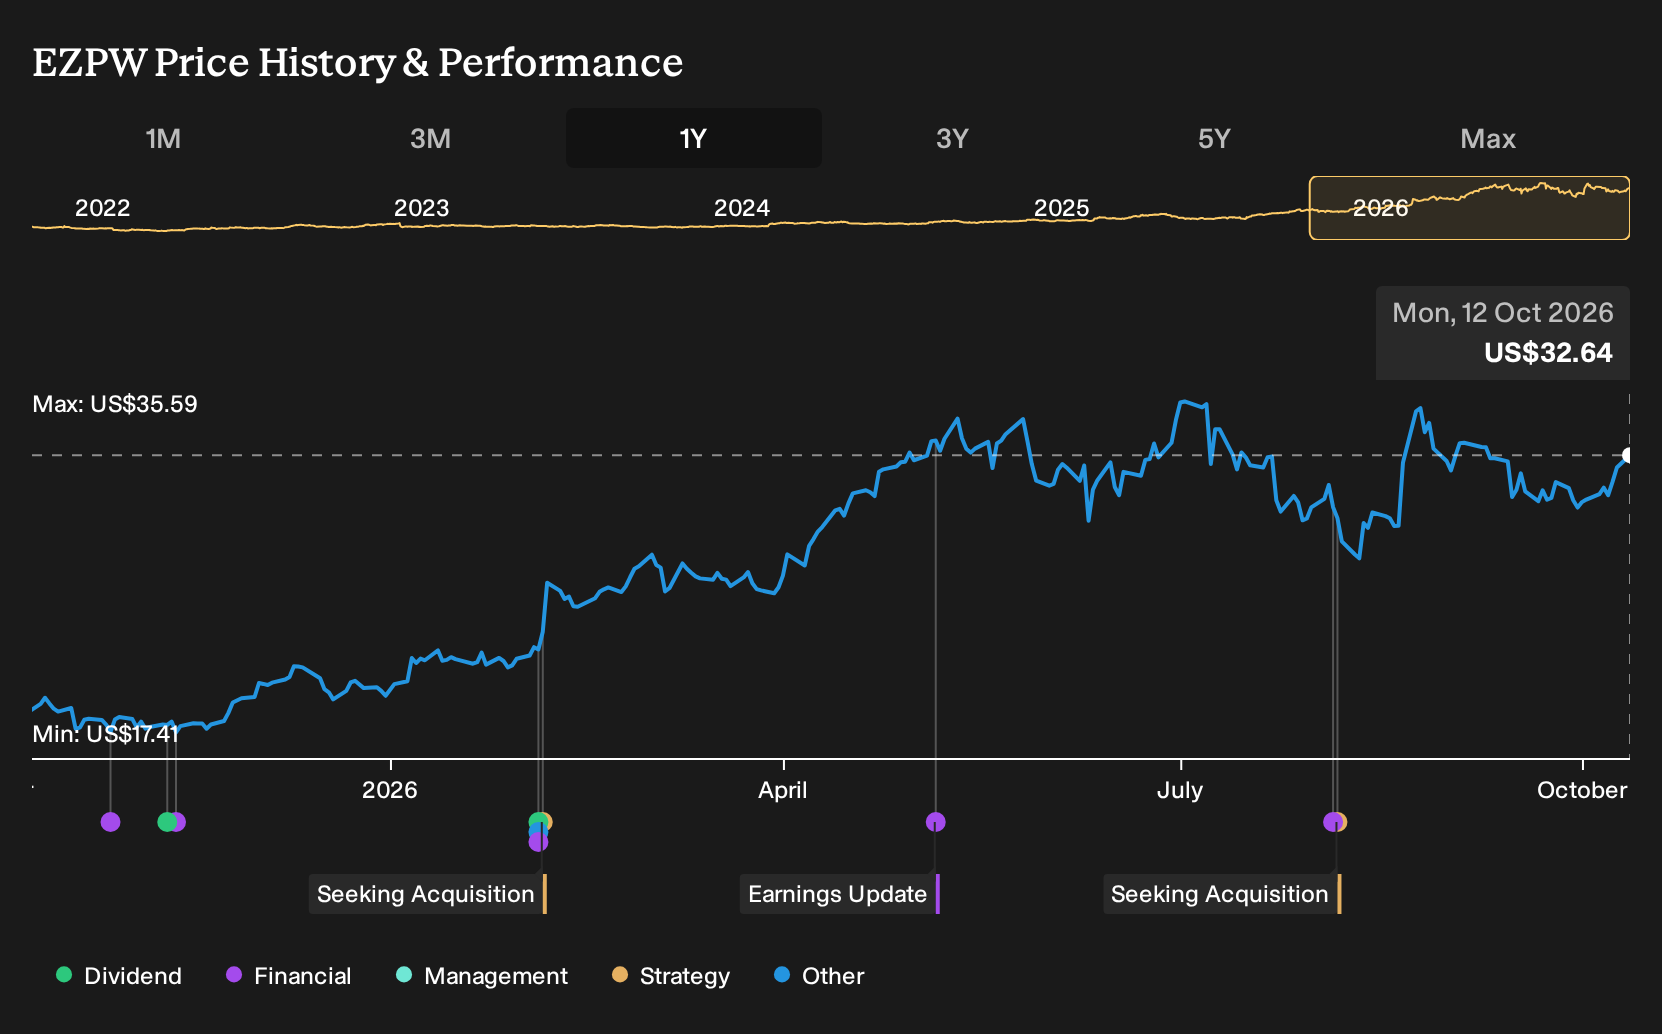
If you only skimmed EZCORP headlines over the past year, the story looked like steady expansion, buybacks, and record quarters, not a lottery ticket. Investors who held EZCORP over the past year are up 72.1%, including dividends. That surge landed after analysts were split in June 2025 over whether the shares were modestly undervalued or already full. If someone had been deciding back then, what exactly in the record could have justified taking that risk?
The easy part of this move is behind EZCORP. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Two EZCORP Stories Investors Were Weighing
EZCORP shares cost US$18.49 at the start of the period, and investors were really choosing between two very different stories about what might come next.
On the bullish side, one camp saw a Fair Value of US$25, a notional price based on their assumptions about the business, tied to aggressive expansion in underbanked Latin American markets and heavier use of omni channel tools like online layaway and Instant Quote.
The more cautious camp anchored on a Fair Value of US$17 and focused on the risk that heavier regulation and faster fintech adoption could shrink the underbanked pool EZCORP serves and tighten rules on pawn lending charges.
What The EZCORP Results Actually Tested
Expansion moves at EZCORP, including full control of Founders One and a larger Simple Management Group stake, backed the bullish story that scale in pawn and Latin America mattered. Revenue rose from US$310.981m in Q3 2025 to US$418.748m in Q3 2026 and net income increased, while insider sales and valuation worries pulled in the cautious view. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on scale and pricing power, keep checking revenue, net income and margin together, and weigh these against any fresh warning signs on valuation or insider selling at other companies.
What EZCORP’s Run Still Leaves You Paying For
EZCORP now trades at US$32.64 after a 72.1% gain over the past year, and the selected Narrative places its Fair Value above that level. The argument hangs on core pawn lending in the U.S. and Latin America doing more of the heavy lifting than gold.
On this view, a buyer today effectively assumes that store level pawn profitability, helped by data tools and expansion, can keep offsetting scrap margin normalization and higher operating costs.
"Continued focus on core pawn profitability, with most recent EBITDA and gross profit growth coming from pawn operations rather than scrap gold, positions future earnings and net margins to depend more on recurring loan demand and merchandise sales than on gold price movements."
One Narrative disagrees with today's price. → See where this Narrative says EZCORP should trade
Looking One Step Beyond EZCORP
EZCORP lives in very physical money moments, from pawn counters to merchandise shelves. Your next question might be where the fully digital version sits.
Plenty of those same customers still want loans, cards, and investing tools they can manage from a phone instead of a storefront.
Another financial platform tries to be that single app, combining everyday banking, borrowing, and investing into one login with one shared data backbone.
It also rents out that software stack to other brands that want modern accounts and payments without rebuilding core banking systems themselves.
If that approach keeps gaining ground, the real story could be how often your future money life runs through someone else’s code instead of a pawn ticket.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 51% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com