


Did AI Research Tools Just Shift Qiagen's (QGEN) Investment Narrative?
- Qiagen recently introduced new AI driven tools for biological and genomic research and gained U.S. FDA clearance for a gram negative bloodstream infection panel that, together with an existing gram positive and fungal panel, provides one hour results across 33 pathogen targets and 28 antimicrobial resistance markers.
- These launches deepen Qiagen's bioinformatics and infectious disease testing portfolios, which could influence demand for higher value consumables, software subscriptions and automated diagnostic workflows across both research and clinical customers.
- We will now look at how Qiagen's new AI research companion might reshape the broader investment narrative around its diagnostics and bioinformatics.
Qiagen Investment Narrative Recap
To own Qiagen, you need to believe the business can shift its mix toward higher value molecular diagnostics, automation and bioinformatics while working through softer research funding and pressure on some legacy testing lines. The key near term swing factor remains how quickly new platforms and assay menus translate into recurring consumables and software demand.
The biggest operational risk is that tight academic and NIH budgets slow instrument placements and delay upgrades, while lower QuantiFERON immigration testing keeps weighing on high value volumes. The latest AI and infectious disease launches help the broader story but do not, on their own, remove those funding and utilization constraints in the short term.
The AI expansion in QIAGEN Digital Insights, including IPA Investigator and the Discovery Platform, looks most directly linked to the current news. These tools aim to keep Qiagen relevant as customers handle more complex genomic data, and they align with the existing catalyst around higher margin bioinformatics and digital PCR gaining more weight in the mix.
For you, the question is execution. If researchers adopt IPA Investigator and the broader Discovery Platform at scale, that can support software subscriptions and stickier workflows, partly offsetting any drag from slower capital budgets. If uptake is patchy or funding for computational biology weakens, the AI build out could take longer to meaningfully affect earnings and cash generation.
What The Consensus Implies For Qiagen's AI Story
Analysts are effectively asking investors to plug Qiagen's AI and diagnostics initiatives into a relatively tight set of numbers rather than a blue sky story. Their models incorporate 6.0% annual revenue growth over the next three years and a move in profit margins from 19.5% today to 22.4% by 2029. On current estimates, earnings today are US$409.3 million and are projected to reach US$561.2 million by 2029, an increase of about US$151.9 million. The same consensus assumes Qiagen reaches revenue of US$2.5 billion in 2029 and that the shares trade on a P/E of 22.4x, slightly below the 22.9x multiple cited today and well under the 43.5x level for the wider GB life sciences group.
Qiagen's AI-driven tools and new infection panels sit inside that framework rather than on top of it. The bloodstream infection menu and bioinformatics software are being treated as part of the 6.0% revenue expansion rather than as a separate growth curve that would require a much higher P/E to justify. If the AI research companion and automated workflows support higher utilization on installed instruments, that kind of operational improvement fits with the margin shift from 19.5% to 22.4% that analysts have already penciled in.
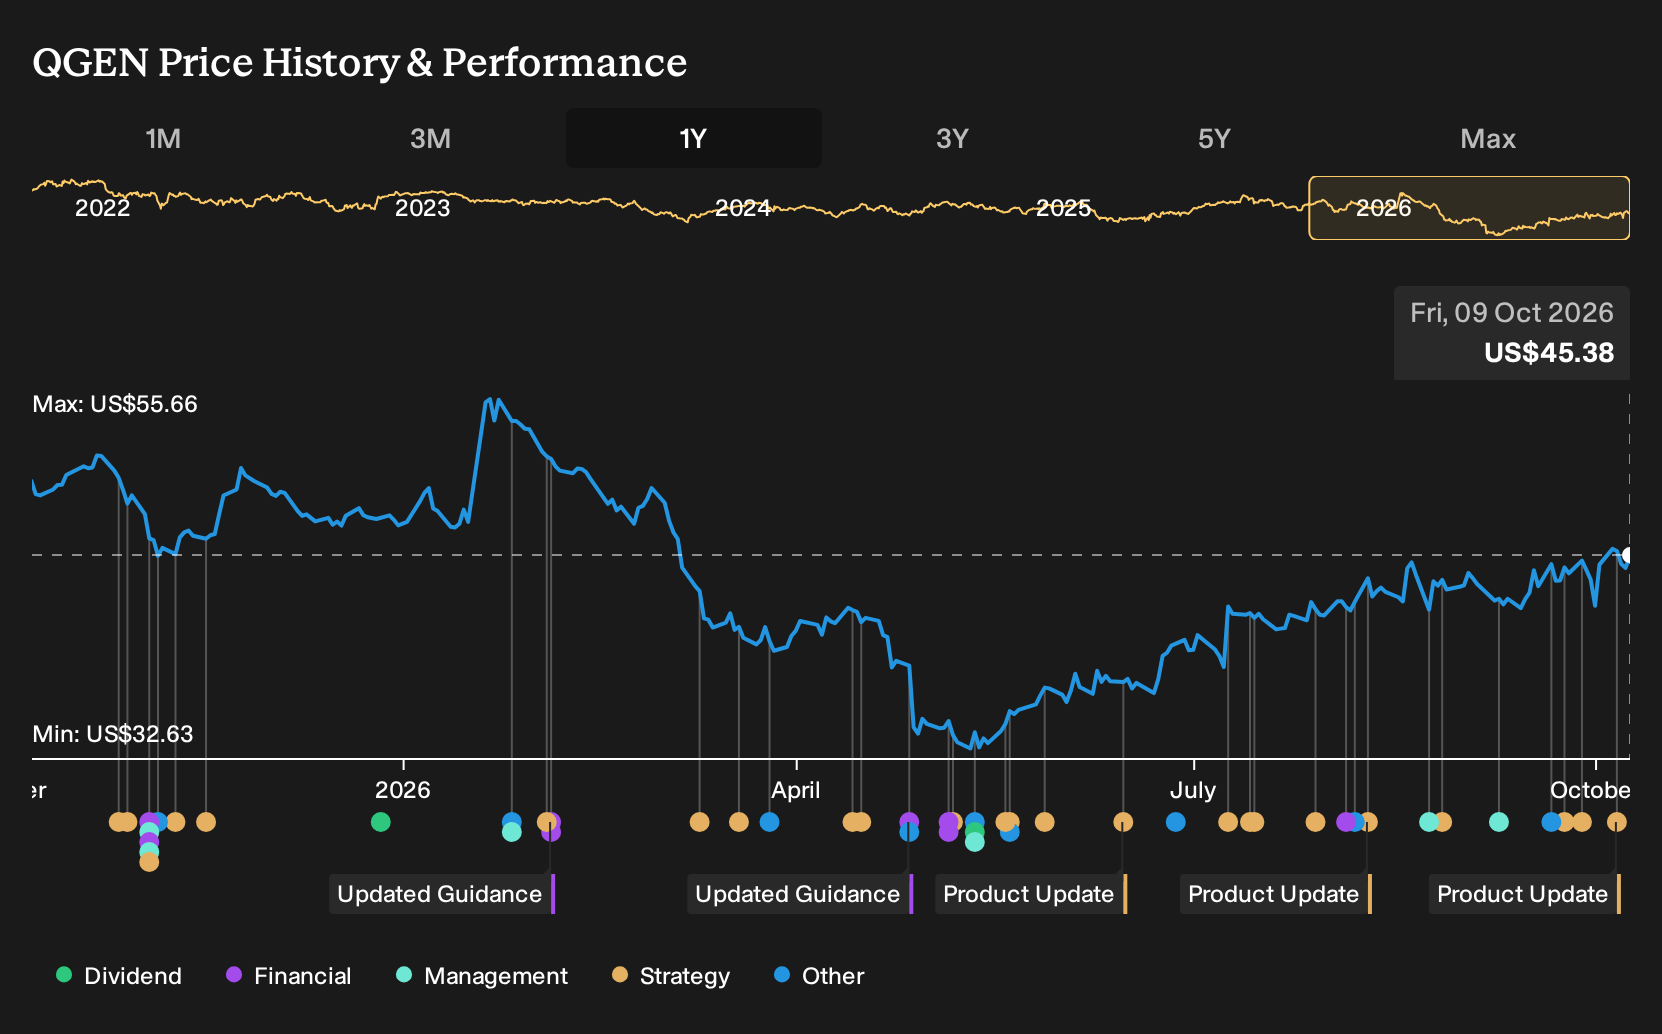
On the capital side, the forecasts assume only modest dilution, with share count growing 0.24% per year, and they use a discount rate of 8.1% to translate the 2029 earnings case back into today's valuation. This provides the backdrop for the consensus price target of US$47.80, which is 5.1% above a recent share price of US$45.38. Viewed against that relatively narrow gap, the AI narrative around QIAGEN Digital Insights and rapid sepsis testing reads more like a story about sustaining this earnings trajectory and margin mix than about resetting expectations.
Qiagen's narrative projects US$2.5 billion of revenue and US$561.2 million of earnings by 2029, based on 6.0% yearly revenue growth and an earnings increase of about US$151.9 million from US$409.3 million today.
Uncover why Qiagen's fair value indicates a 5% potential upside to its current price, which could narrow quickly if Qiagen's execution outpaces expectations.
Exploring Other Perspectives
One alternate view focuses on Qiagen’s QuantiFERON reset rather than the AI launch. The most cautious analysts were only assuming about 4.6% annual revenue growth to roughly US$2.4b by 2029 and earnings of US$581.1 million, with a lower 18.1x P/E. Those forecasts came before this AI news, so opinions may change as you review both narratives.
Explore 4 other Qiagen fair value estimates, including one that suggests as much as 12% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Qiagen?
Qiagen may be the focus today, but your watchlist does not need to stop there. The Simply Wall St Screener can help you line up other companies that fit specific goals, from income resilience to balance sheet strength and underappreciated potential.
- If capital preservation is your priority, consider starting with a group of 31 resilient stocks with low risk scores that keep volatility and risk scores in check.
- If income reliability matters more to you, focus on opportunities offering strong cash returns through a curated set of 8 dividend fortresses that emphasize both yield and durability.
- If you are hunting for future leaders before they are widely followed, spend time with a hand picked pool of 20 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com