


What Rightmove Holders Got Wrong Before The Slide
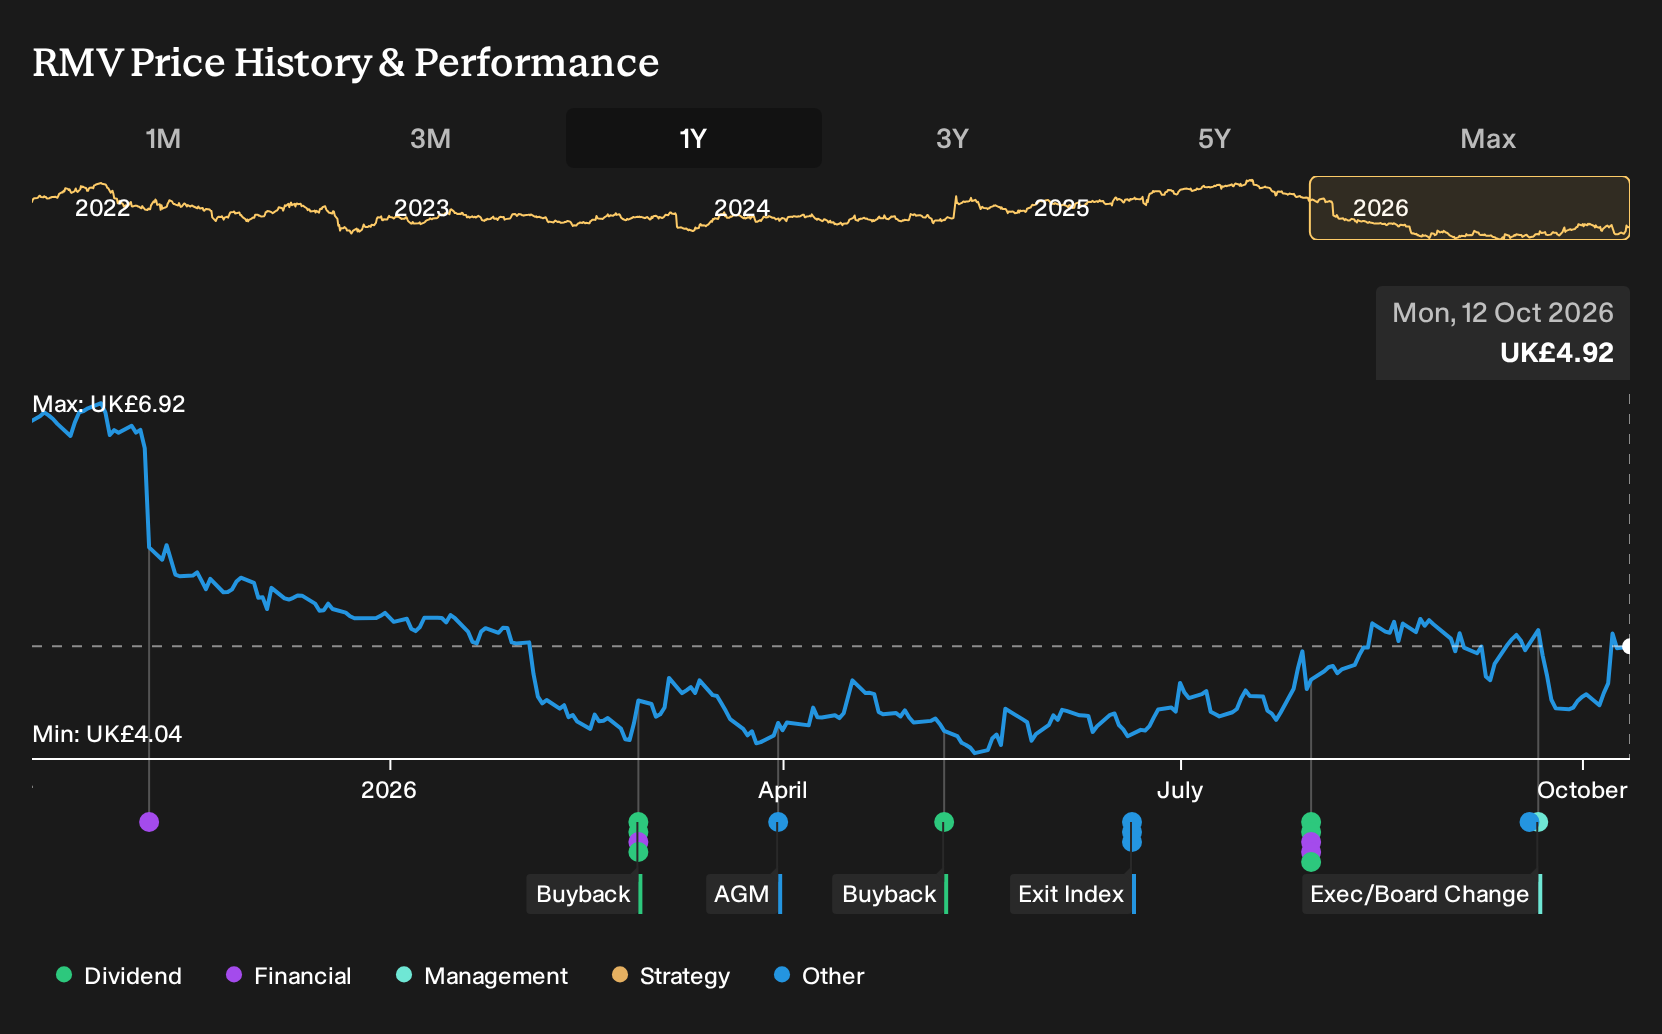
Rightmove looked like a straightforward growth story on paper, with analysts in 2025 sketching out higher earnings and margins while the latest half year update showed both revenue and profit above the prior period even as net margin slipped. Investors who held Rightmove over the past year are down 26.1%, including dividends. If you had been weighing a purchase in October 2025, which signals really mattered before that slide showed up in your portfolio?
If the move has made Rightmove harder to judge, start where the gap is still open and scan 7 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Rightmove
The shares cost £6.76 at the start of the period, and anyone looking at Rightmove then was really choosing between two different stories about where the portal could go next.
The bullish narrative saw property search becoming increasingly digital. Its fair value was £7.78, a notional price based on assumptions that AI tools, higher Average Revenue Per Advertiser and growth in mortgages, rentals and commercial listings would all build diversified, high margin revenue.
The bearish view anchored on a fair value of £4.85, again a model price, built on worries about tighter regulation, UK market saturation and the risk that new proptech platforms and data rules would chip away at Rightmove's pricing power.
What The Results Changed For The Rightmove Thesis
The most concrete update came from Rightmove's H1 2026 figures. Revenue reached £225.848m and net income was £111.213m, both above H1 2025, yet net margin slipped from 51.9% to 49.2%. That combination backed parts of the bullish case around revenue and profit, while the margin pressure kept the cautious story alive. The evidence cut both ways.
The live assumption here was not just “can this grow” but also “can it stay this profitable while it grows.” When you assess another platform business, track net margin beside revenue, then test any high-margin promise against at least a couple of reporting periods.
What You Would Be Paying For In Rightmove Today
Rightmove now trades at £4.92, with this Narrative’s Fair Value set above that level, based on its own assumptions rather than any settled truth about the shares.
The central argument leans on AI tools, a large data set and capital returns. A buyer today would need to believe those features can translate ARPA gains into lasting profit growth.
"Rightmove's fully cloud-enabled, AI capable tech stack with over 5 petabytes of unified data and 31 or more AI projects in flight creates room for entirely new data products and workflow tools that could support additional revenue lines and higher operating margins as more of development and operations become AI assisted."
One Narrative disagrees with today's price. → See where this Narrative says Rightmove should trade
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 35% below our estimate - targets underpenetrated infrastructure and private equity niches to expand managed assets.
- Company 2 - 26% below our estimate - uses a unified tech stack and AI tools to lower servicing costs.
- Company 3 - 22% below our estimate - scales automated production and distributor channels to broaden supplement ranges efficiently.
Three companies from the same screener. Open every one of the 9 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com