


How Investors May Respond To Skanska (OM:SKA B) US Contract Wins
- Skanska disclosed a run of US deals and one Czech investment, adding multi year contracts across rail, education, healthcare, defense infrastructure and residential development worth several billion SEK to its third quarter 2026 order bookings.
- The U.S. Forest Service grant for a tall mass timber insurance guide gives Skanska a direct role in shaping risk standards for a key green building method, which could influence how future sustainable projects are structured and insured.
- The focus now turns to how Skanska's investment narrative is affected by these US contract wins and the mass timber grant.
Scan how Skanska’s fresh U.S. public sector wins compare with other construction and infrastructure groups by checking our hand picked 43 power grid technology and infrastructure stocks.
Skanska Investment Narrative Recap
To own Skanska today, you need to believe the construction and development portfolio can turn a record backlog into steadier earnings despite choppy property markets. The key near term swing factor remains how quickly Nordic residential and U.S. commercial divestment conditions improve, because sluggish transactions can keep cash generation and reported profit more uneven.
The fresh U.S. contracts and the Czech residential investment expand committed work rather than changing that central debate. They support order visibility and mix, yet do not materially shift the biggest risk, which is prolonged weakness in property markets. Cost inflation, project execution and restructuring spending still sit close behind on the risk list.
The Naval Station Newport pier project in Rhode Island, worth about US$271 million, is the announcement that says most about Skanska’s operating setup right now. It threads together U.S. federal infrastructure demand, complex technical work and a timeline that runs to March 2030. This locks in long duration civil exposure in a defense related environment.
For catalysts, that pier contract feeds into the existing backlog story rather than creating a new one. The long schedule can support revenue visibility if Skanska manages costs. It also raises exposure to labor availability, material pricing and regulatory shifts over several years, which matters for anyone focused on margin resilience and cash timing.
Skanska's narrative projects SEK 211.8 billion revenue and SEK 9.0 billion earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about SEK 2.4 billion from current earnings of SEK 6.6 billion.
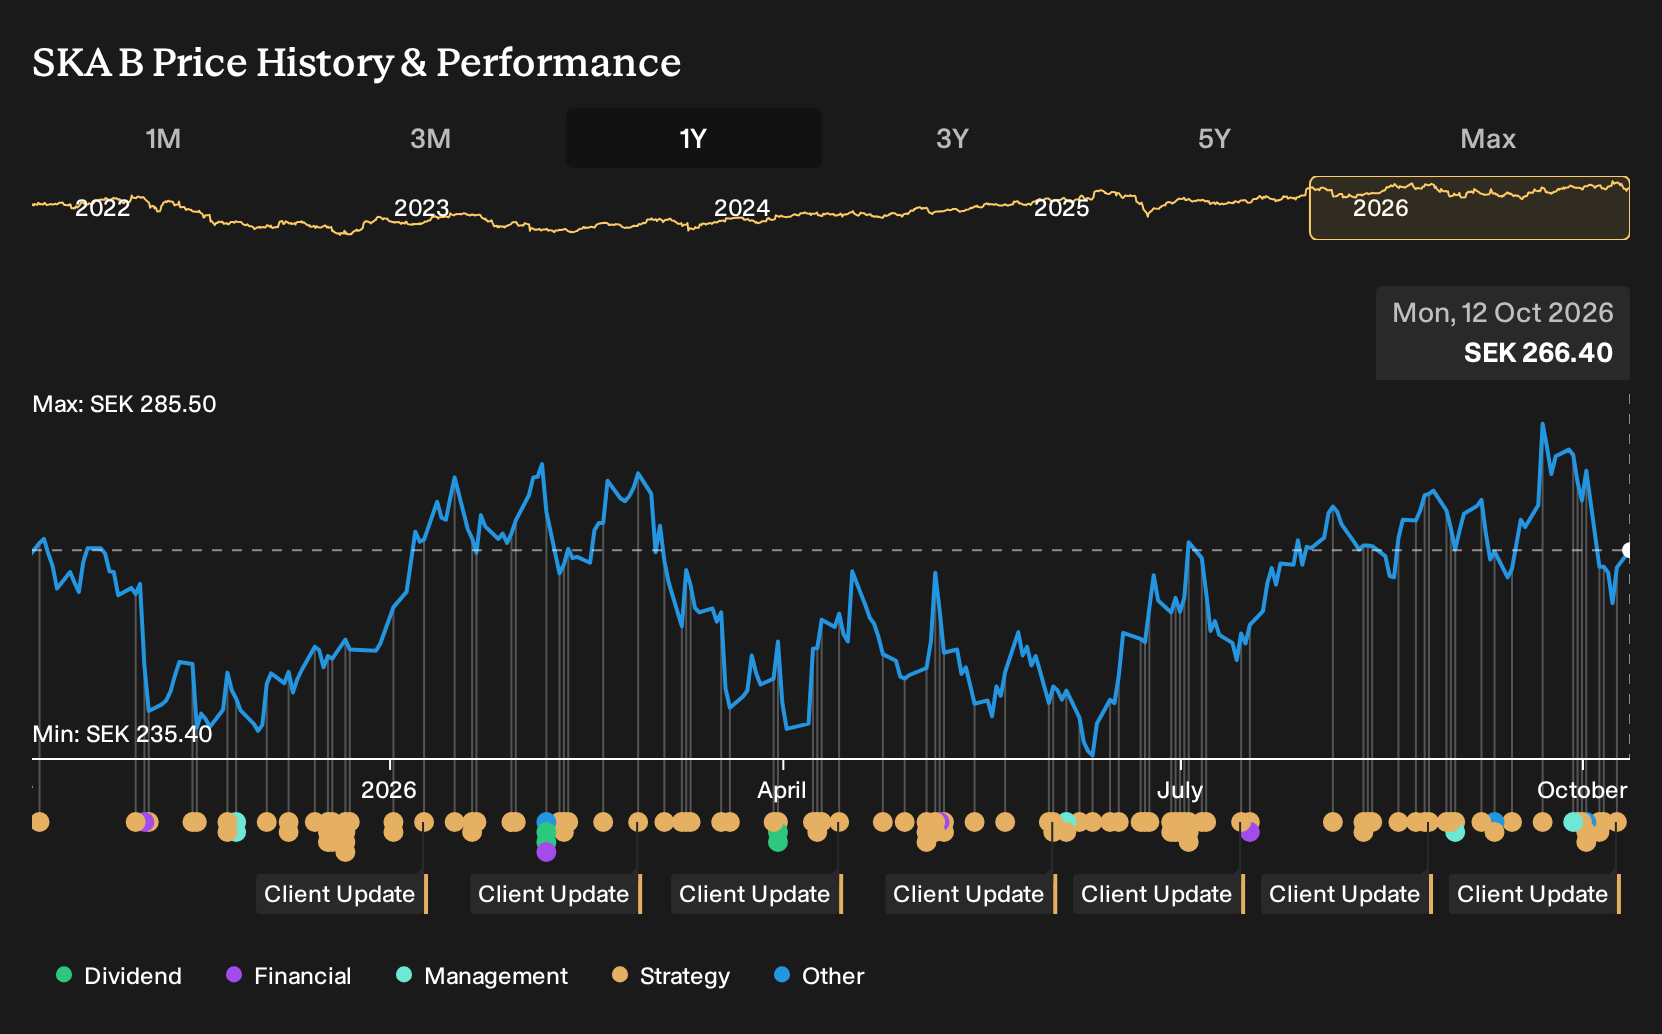
Uncover why Skanska's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor for Skanska is not backlog at all but the risk that commercial property divestments stay soft. Those analysts were only pencilling in SEK 204.5 billion revenue and SEK 8.9 billion earnings by 2029. That is a much cooler story than consensus and could shift as these new U.S. deals bed in.
Explore 4 other Skanska fair value estimates, including one that suggests as much as 23% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Skanska research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Skanska. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skanska's overall financial health at a glance.
Looking for more investment ideas beyond Skanska?
Skanska might be central to your thesis today, but building a resilient portfolio usually means lining it up alongside other opportunities with very different drivers.
- For investors hunting for mispriced quality, scan a curated pool of 181 high quality undervalued stocks that combine fundamentals with what may be undemanding expectations.
- If a smoother ride matters more than excitement, focus on companies in the 226 resilient stocks with low risk scores that score well on financial robustness and business stability.
- To uncover potential future leaders before they are widely followed, check the 618 high quality undiscovered gems and broaden your watchlist with under the radar candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com