


What Rollins (ROL)'s AI Search Disruption Means For Shareholders
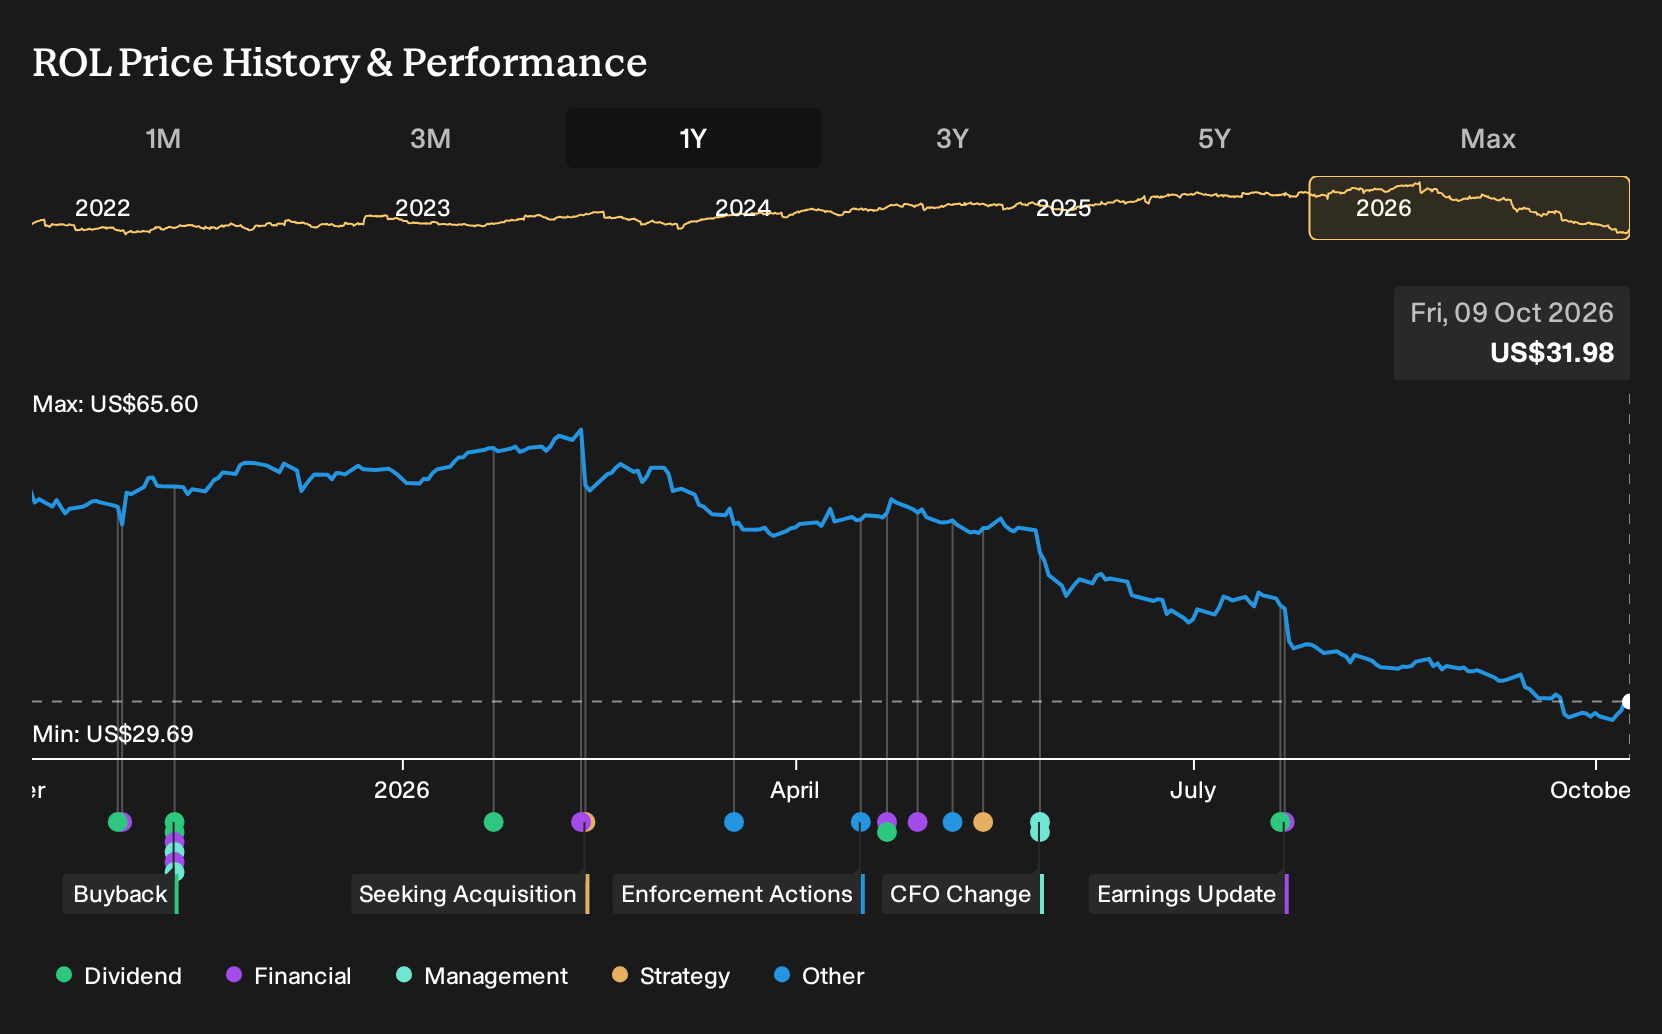
- Rollins reported softer consumer search activity and disruption in digital lead recovery after AI driven changes to search, while higher staffing and service expenses pressured operating margins despite revenue growth.
- The reliance on recurring pest control services for revenue stability now intersects with tougher, less profitable new account acquisition, sharpening the focus on customer retention quality rather than just volume.
- This article examines how Rollins's investment narrative is shaped by AI disrupted residential leads and the resulting pressure on margins.
Compare how Rollins handles recurring revenue and margin pressure with other hand picked businesses by scanning our 31 resilient stocks with low risk scores that balance durability with disciplined cost control.
Rollins Investment Narrative Recap
To own Rollins, you need to believe its pest control services stay sticky and that management can keep recurring contracts healthy while repairing the weakened digital funnel. The near term swing factor is whether Orkin search driven leads stabilise so residential volumes and route density do not erode service efficiency.
The biggest current risk sits in margins. Staffing, fleet and service costs are already pressuring profitability while profit growth expectations have cooled, which is reflected in a lower forward P/E multiple. If digital acquisition stays soft and new accounts become less profitable, cost control and retention discipline matter even more.
Recent commentary around rebuilding the Orkin digital funnel after AI related changes to consumer search is the clearest operational announcement that ties to this setup. Management is testing new approaches across multiple AI platforms to restore residential lead flow and improve conversion, which directly connects to growth, technician productivity and route economics.
That push sits alongside integration of Romex Pest Control and other tuck in deals, with stated ambitions for 2% to 3% annual acquisition driven revenue contribution. For you, the practical question is whether Rollins can blend acquired growth, channel mix shifts such as HomeTeam and Fox, and cost work on fleet and procurement into steadier margins.
Rollins' current analyst narrative points to revenues of US$5.0b and earnings of US$709.9m by 2029, which rests on 8.5% yearly revenue growth and an earnings increase of about US$178m from US$531.7m today.
Uncover why Rollins' fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One big swing factor the more cautious analysts focus on is regulatory and ESG related costs for Rollins. You can see it in their older forecasts, which pointed to revenues of about US$4.9b and earnings near US$704.4m by 2029. That cohort reads the same digital and margin issues as leaving far less room for error, so opinions clearly diverge. Use that spread to pressure test your own view, especially now that fresh news could push both narratives to evolve.
Explore 6 other Rollins fair value estimates, including one that suggests as much as 49% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rollins research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rollins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rollins' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rollins?
If the Rollins story has sharpened your thinking on quality, risk and pricing power, use that same lens to scan a broader opportunity set with the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, start with a curated set of 29 high quality undervalued stocks that pair strong fundamentals with more grounded pricing.
- If income is your focus, see which companies show the staying power to keep paying out by reviewing our 8 dividend fortresses built around higher yielding payers.
- For those who prefer balance sheet strength as a safety net, sort through the list of solid balance sheet and fundamentals (25 results) and see which businesses match your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com