


UK AI Rules Put Vodafone Stock And Cloud Providers In Focus
AI regulation is moving from concept to rulebook in the UK, and that shift is pulling cloud and data centre providers into the spotlight. Tighter oversight on “frontier AI” turns reliable infrastructure, security and compliance into potential battlegrounds for capital. This article unpacks that story and reveals three UK Regulated Cloud and Data Centre stocks exposed to these developments, so you can judge where risk and opportunity might sit.
The stocks below are just a starting sample, and the full screen surfaced 8 more UK Regulated Cloud and Data Centre providers with equally compelling narratives that are not covered here. To identify and analyze the highest conviction ideas in this space, head straight into the UK Regulated Cloud and Data Centre Providers screener.
Vodafone Group (LSE:VOD)
Overview: Vodafone Group is a large telecom operator providing mobile, fixed, cloud, IoT and digital services across Europe, Turkey and Africa.
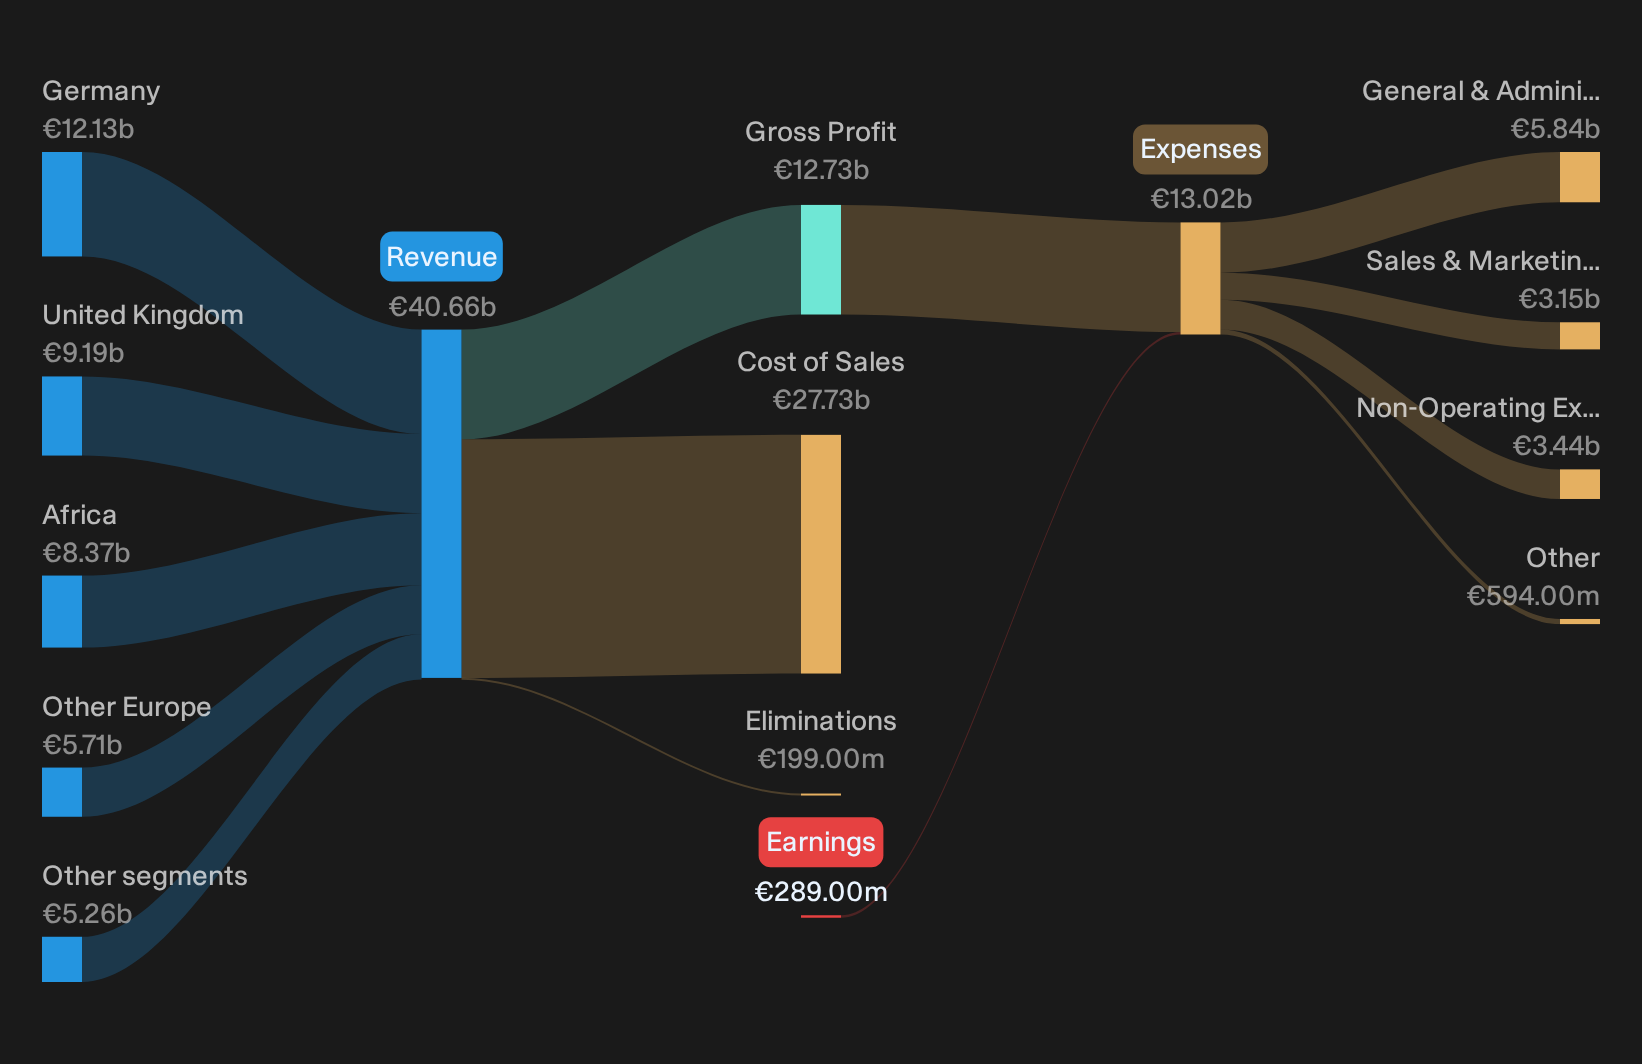
Operations: Vodafone generates most of its revenue from Germany (€12.1b), the United Kingdom (€9.2b) and Africa (€8.4b), with smaller contributions from Turkey and other European markets.
Market Cap: £27.2b
Vodafone Group matters in this AI regulation and cloud story because its telecom backbone, hosting services and data-centre footprint sit where regulated connectivity, secure workloads and UK sovereignty concerns start to converge.
"The strategic partnerships with industry players like Google and Accenture, along with investment in digital services, are catalysts for revenue growth and potentially higher margins through increased service offerings and higher-margin digital products."
What happens to margins if one unresolved pressure on funding heavier network and cloud investment moves in the wrong direction?
If that pressure on Vodafone Group margins is what you care about, read the full narrative for Vodafone Group to see how regulation, networks and cloud economics could be decoupling.
Made Tech Group (AIM:MTEC)
Overview: Made Tech Group delivers digital, data, AI and cloud services that help UK public bodies modernize and secure regulated technology platforms.
Operations: Made Tech Group reports £58.88 million in revenue from computer graphics related services, supporting its wider UK public-sector technology work.
Market Cap: £72.4 million
Made Tech Group provides focused exposure to UK government digital transformation. Earnings growth, margin improvement and Met Office secure-services work highlight demand for compliant cloud and data platforms that support stricter AI rules. However, a shift in how public bodies fund long-running programmes could still change how comfortably those contracts cover future delivery costs.
Those contract economics are the real hinge, so it is worth scanning the analysis report for Made Tech Group to see how Made Tech Group’s pipeline and pricing power stack up.

Pinewood Technologies Group (LSE:PINE)
Overview: Pinewood Technologies Group provides cloud-based automotive retail software and AI tools to dealer groups worldwide, delivered as subscription services.
Operations: Pinewood Technologies Group generates £38.9 million from its Pinewood segment and £5.3 million from Seez, with a small segment adjustment.
Market Cap: £516.2 million
For this UK Regulated Cloud and Data Centre Providers screen, Pinewood Technologies Group matters because its dealer software relies on UK hosted, SaaS infrastructure that has to stay reliable, secure and compliant as AI rules tighten around how data rich tools operate.
"The long term shift toward data rich, AI supported dealership operations gives Pinewood a clear product fit. However, the integration of Seez into the core platform is complex and could slow the pace at which new AI tools convert into meaningful additional revenue and improved net margins."
Everything now hinges on whether a single, unseen pressure in turning heavy AI and software investment into durable margins is resolved in a favourable way.
If you want to see whether that pressure becomes a real accelerator for Pinewood Technologies Group, read the full narrative for Pinewood Technologies Group to see what might be masking the next leg of momentum.

Seeking Fresh Alternatives Before They Fly
Opportunities move fast. Some stay under the radar for now, others build quiet momentum before a breakout. Scan fresh ideas before the crowd and consider your options.
- Explore dependable income streams by running the 1 dividend fortresses and focus on companies where sizable payouts and balance sheet strength still align while it matters.
- Monitor developments in AI using the 39 profitable AI stocks that aren't just burning cash and focus on businesses already generating cash instead of relying primarily on external funding.
- Review potential infrastructure shifts with the 43 power grid technology and infrastructure stocks and evaluate companies exposed to upgrades before valuations fully incorporate the story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com