


Is Shopify (SHOP) Fully Valued Following Strong Growth Guidance And Raised Revenue Estimates?
Shopify (SHOP) is back in focus after management guided to robust revenue growth and analysts lifted their sales forecasts, with fresh AI driven partnerships in e commerce helping reset expectations around the stock.
That renewed story is showing up clearly in the chart, with Shopify’s share price gaining 3.82% over the last day, a 32.66% 1 month share price return and a 35.94% 3 month share price return, while the 3 year total shareholder return of 220.66% keeps the longer term narrative firmly in play as AI partnerships, migration demand and recent fund flows reshape how investors are thinking about both its potential for growth and the risks around its valuation.
Scan beyond Shopify and line up other potential AI driven e commerce beneficiaries using our curated list of 38 AI small caps.
Shopify now looks like a powerful business backed by rising AI partnerships and migration demand, yet the stock sits close to analyst targets after a sharp run. How much of that quality is already in the price?
Most Popular Narrative: 18.8% Undervalued
According to one of the most followed narratives, Shopify's fair value of $210.47 sits well above the last close at $170.85. This frames the recent rally as only part of the story rather than the whole move.
I believe Shopify has become one of the core pieces of infrastructure behind global entrepreneurship. And with most of its revenue now tied to merchant activity, Shopify increasingly benefits directly as the businesses built on top of it grow.
See why 4 investors see Shopify as 19% undervalued.
Result: Fair Value of $210.47 (UNDERVALUED)
Still, Shopify’s premium valuation and reliance on broader merchant activity leave the story exposed if ecommerce spending cools or if investor appetite for high P/E software fades.
Find out about the key risks to this Shopify narrative.
Another View: Shopify Through The P/E Lens
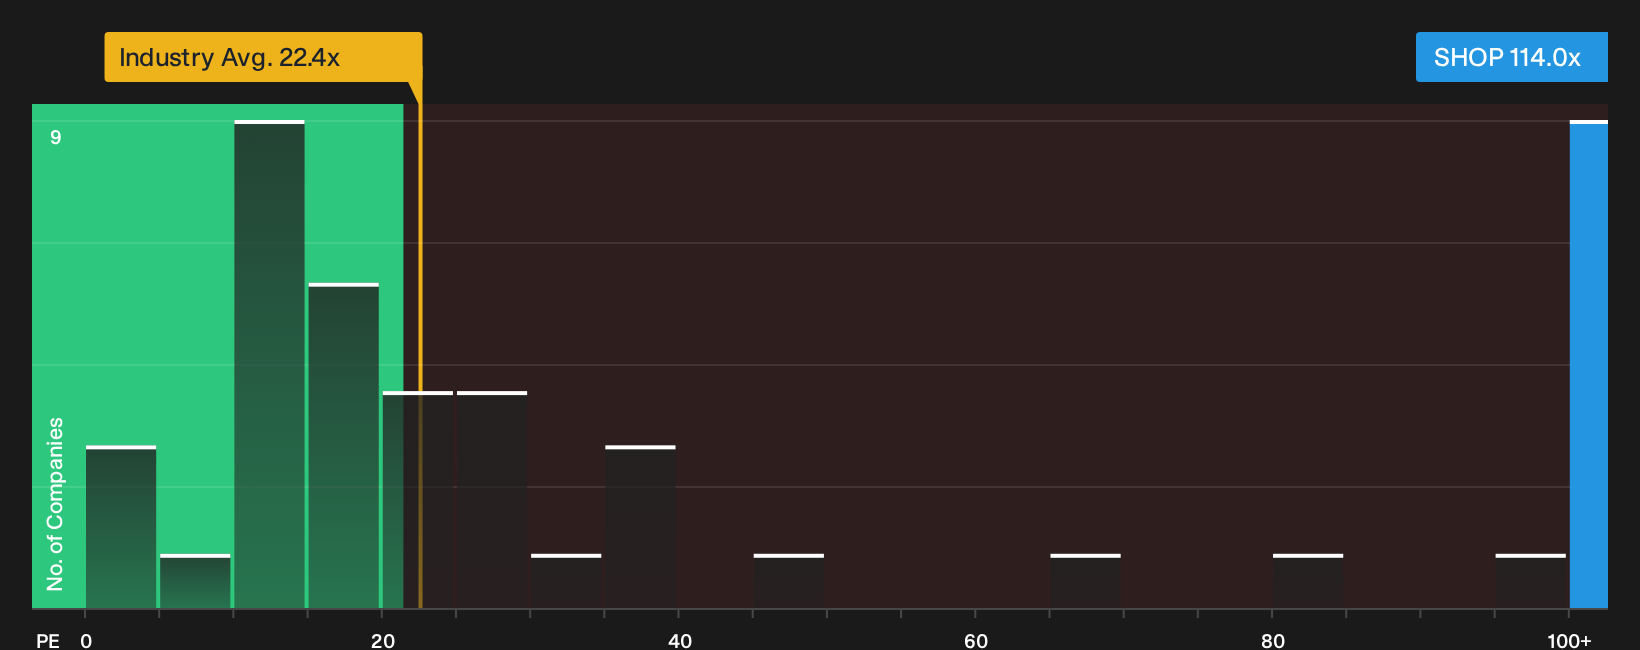
There is a very different picture when you look at Shopify through its P/E. The stock trades at 114x earnings, while the US IT sector sits around 22.4x and peers average 68.9x. The fair ratio of 49.8x suggests a gap that raises real questions about valuation risk.
That kind of premium means you are paying far more for each dollar of profit than both the wider industry and closer peers. This can work if the company continues to meet the expectations that support this valuation, but it can also hurt quickly if sentiment cools or growth expectations ease. How comfortable are you paying that much extra per dollar of earnings for Shopify?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and valuation nerves feels familiar, trust your instincts, act promptly, and pressure test the story against the underlying numbers yourself using 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Shopify?
Do not leave your next move hanging on one ticker. Spread your research, pressure test fresh angles, and line up alternatives before the market moves without you.
- Target potential mispricing early by scanning a curated set of 29 high quality undervalued stocks that combine quality fundamentals with marked down share prices.
- Build a sturdier core for your portfolio by focusing on companies with stronger finances using our list of solid balance sheet and fundamentals (25 results).
- Look for possible future standouts before the crowd by reviewing a focused pool of 20 high quality undiscovered gems that already show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com