


Ono Pharmaceutical (TSE:4528) Secures Biohaven Asia Rights, Is The Stock Still A Bargain?
Ono Pharmaceutical (TSE:4528) moved into focus after Biohaven announced a licensing deal that grants Ono exclusive rights to develop and commercialize Biohaven’s MoDE pan IgG degrader drugs across key Asian markets.
Against this licensing backdrop, Ono Pharmaceutical’s share price has eased, with a 30-day share price return of 2.63% and a 90-day share price return of 5.89%. The year-to-date share price return sits at 3.22%, while the 1-year total shareholder return of 29.26% indicates that longer term momentum has been stronger than recent trading suggests.
Scan how Ono Pharmaceutical’s new autoimmune licensing deal compares with other potential breakout opportunities across our curated list of 74 high quality undiscovered gems in global healthcare and beyond.
Ono Pharmaceutical now has a fresh autoimmune pipeline angle and a share price that has cooled after strong 1-year gains. The real tension is simple: does the current valuation still give you enough compensation for the risk?
Preferred P/E of 13.9x: Is it justified?
On valuation, Ono Pharmaceutical trades on a P/E of 13.9x, with the last close at ¥2,259 and a DCF estimate pointing to a higher future cash flow value. The gap between the trading multiple and the internal fair multiple hints at room for the market view to shift.
The P/E ratio compares the share price to earnings per share and is widely used for profitable drug makers. For a business like Ono Pharmaceutical, with established oncology and specialty product franchises, the P/E helps you judge what investors are paying for each unit of current profit.
Recent fundamentals give more context. Earnings grew 77.6% over the past year and profit margins improved from 8.6% to 15.1%, while the company is assessed as having high quality earnings. That backdrop contrasts with forecasts that point to annual earnings declining by 3.1% and revenue declining by 1.2% per year over the next three years, which can limit how far a valuation re-rate might go without new drivers.
Against local peers, the picture is mixed. The current P/E of 13.9x is described as expensive relative to the Japan pharmaceuticals industry average of 13.9x. However, it is viewed as good value versus the estimated fair P/E of 17.6x and the peer average of 16.3x. The fair ratio implies a level the market could move toward if the quality of earnings and profitability are sustained despite the forward decline forecasts.
Explore the SWS fair ratio for Ono Pharmaceutical.
Result: Price-to-Earnings of 13.9x (UNDERVALUED)
Still, the recent decline in annual revenue and net income growth, together with a weaker 3-year shareholder return, could challenge the bullish case for Ono Pharmaceutical.
Find out about the key risks to this Ono Pharmaceutical narrative.
Another view on Ono Pharmaceutical’s value
The P/E story points one way, yet the SWS DCF model points even further. With Ono Pharmaceutical at ¥2,259 and the DCF estimate at ¥3,427.32, the model frames the stock as undervalued. The gap raises a blunt question: Is the discount compensating you for forecast earnings decline?
Look into how the SWS DCF model arrives at its fair value.
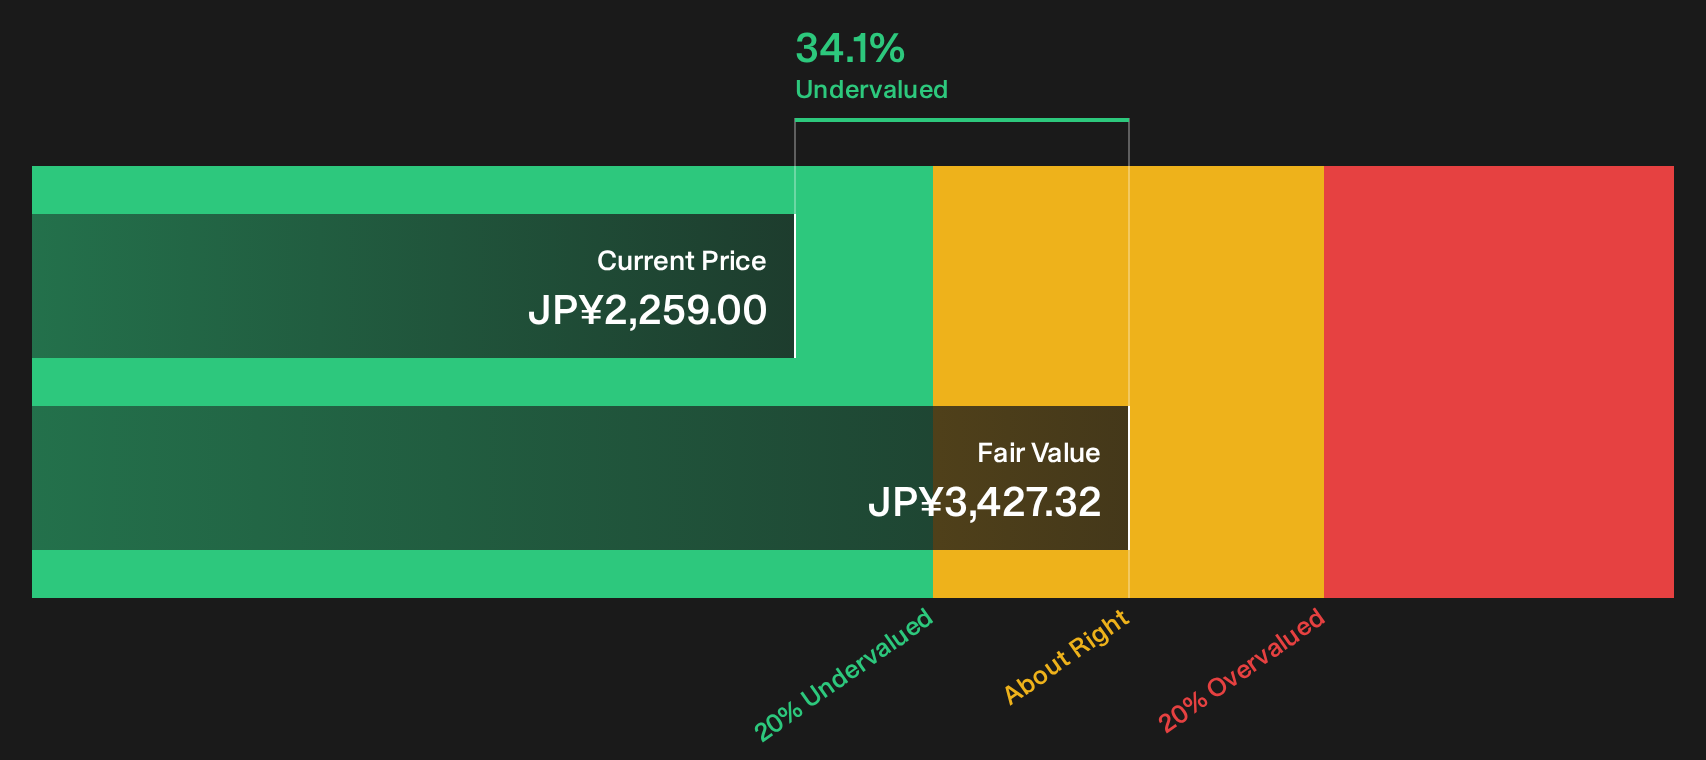
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ono Pharmaceutical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Ono Pharmaceutical leave you on the fence, that is exactly when doing your own homework matters most. Move quickly through the latest data, weigh both the concerns and the upside, and anchor your decision around the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ono Pharmaceutical?
If Ono Pharmaceutical has your attention, broaden your opportunity set with other high conviction ideas sourced from objective data and consistent screening rules.
- Target stronger value upside by scanning companies that pass rigorous quality and valuation filters with our 12 high quality undervalued stocks.
- Lock in steadier portfolio income by focusing on cash generating businesses screened through the 28 dividend fortresses.
- Prioritise resilience under pressure by zeroing in on companies with cleaner finances using the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com