


Emerald Resources (ASX:EMR), What Is Behind The Latest Attention?
Emerald Resources (ASX:EMR) has put fresh numbers on the table, pairing full year Okvau Gold Mine production of 20,280oz with new FY 2027 guidance of 100,000oz to 115,000oz and AISC of US$980/oz to US$1,080/oz.
Investors have treated the latest Okvau update as one more step in a bigger story, with Emerald Resources’ recent 26.12% 90 day share price return and 29.75% one year total shareholder return pointing to momentum that has built over several years rather than faded.
Spot potential peers to Emerald Resources by scanning a handpicked 36 elite gold producer stocks that share similar production themes and operational focus.After that strong share price run, along with fresh Okvau guidance on volumes and costs, does Emerald Resources still offer enough upside potential to compensate for the project and country risks investors are taking on?
Preferred P/E of 17.2x for Emerald Resources: Is it justified?
On current numbers, Emerald Resources trades on a P/E of 17.2x, which prices the stock above the Australian Metals and Mining industry average but below its peer group and below its own estimated fair P/E of 19.3x.
The P/E ratio compares the share price to earnings per share. For a gold producer like Emerald Resources with A$612.5m of revenue and A$259.6m of net income, this measure helps you see how much investors are willing to pay for each dollar of profit.
Management has delivered earnings growth of 196.3% over the past year, with profit expansion of 43.1% per year over the past five years and net profit margins now at 42.4%. In that context, a 17.2x P/E suggests the market is paying up for recent performance but not assigning the highest premium that peers on 24.2x command. It also sits below the 19.3x fair P/E level that the SWS model indicates the market could move towards over time.
Compared to the broader Australian Metals and Mining industry on 11.6x, Emerald Resources trades at a materially richer multiple. This points to investors assigning higher quality or growth expectations than the sector average while still leaving a valuation gap relative to the 19.3x fair ratio reference.
Explore the SWS fair ratio for Emerald Resources.
Result: Price-to-Earnings of 17.2x (UNDERVALUED)
Still, concentration in Cambodia and reliance on a single core asset mean any setback at Okvau or shift in country conditions could quickly challenge the Emerald Resources valuation story.
Find out about the key risks to this Emerald Resources narrative.
Another view on Emerald Resources valuation
The P/E discussion paints Emerald Resources as modestly cheap, yet the SWS DCF model gives a much stronger signal. At A$6.76, the stock is trading 66.3% below an estimated future cash flow value of A$20.04, which frames it as heavily undervalued if those cash assumptions hold.
That is a very different message to paying 17.2x earnings. It raises a simple question for you as an investor: Are current cash flow forecasts and Okvau execution reliable enough to close such a wide gap, or is the model being too generous on long term outcomes for Emerald Resources?
Look into how the SWS DCF model arrives at its fair value.
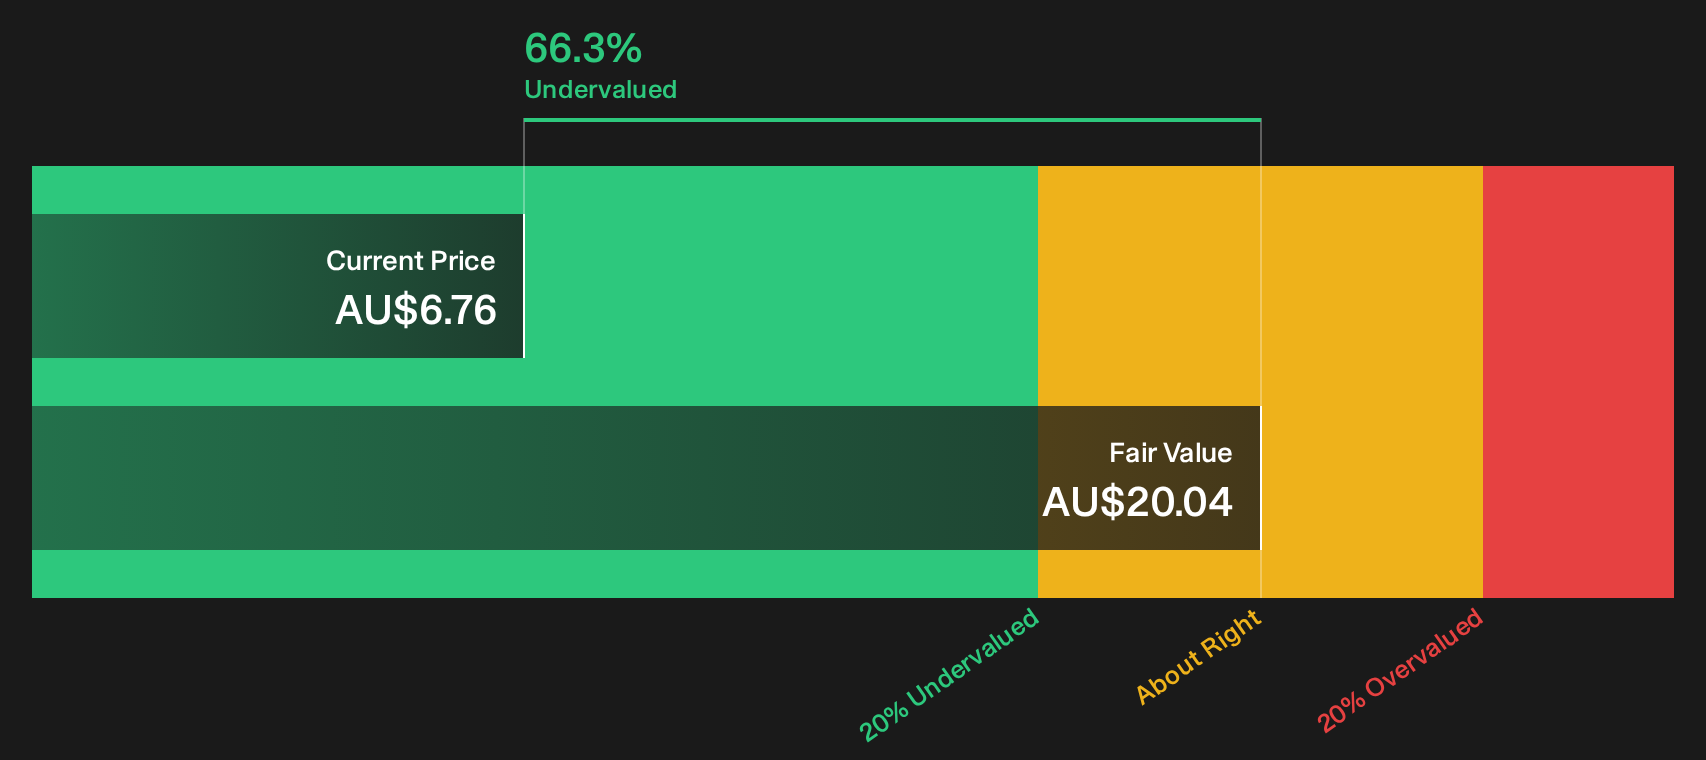
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Emerald Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on Emerald Resources leave you undecided, that is the point. Use the data, test your own thesis, and pressure-check those positives through the 3 key rewards
Looking for more Emerald Resources style ideas?
If Emerald Resources has sharpened your focus on quality and risk, do not stop here. Broaden your watchlist with ideas that match your own investing rules.
- Chase value with conviction by reviewing the 4 high quality undervalued stocks that line up strong balance sheets with pricing that still looks restrained.
- Prioritise resilience by scanning the 7 resilient stocks with low risk scores that score well on stability so sharp drawdowns are less likely to catch you off guard.
- Hunt for future standouts by filtering through the 15 high quality undiscovered gems before attention and capital crowd into the same familiar tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com