


3 Undervalued Small Caps With Insider Buying Across Global Markets
Over the last 7 days, the United States market has remained flat, yet it has seen a notable 15% increase over the past year with expectations of an 18% annual growth in earnings in the coming years. In this context, identifying stocks that are potentially undervalued and have insider buying activity can provide investors with opportunities to capitalize on favorable market conditions.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Financial Institutions | 9.3x | 3.1x | 27.33% | ★★★★★☆ |
| Surgery Partners | NA | 0.5x | 25.99% | ★★★★★☆ |
| Enovis | NA | 0.4x | 44.88% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.1x | 34.08% | ★★★★☆☆ |
| Five Star Bancorp | 14.5x | 6.2x | 47.27% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.7x | 2.4x | 28.12% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 45.94% | ★★★★☆☆ |
| Shore Bancshares | 11.2x | 3.2x | 37.22% | ★★★★☆☆ |
| German American Bancorp | 12.7x | 4.8x | 27.81% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.6x | 2.6x | 7.48% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Anika Therapeutics (ANIK)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Anika Therapeutics is a company that specializes in developing and manufacturing medical products, with a market capitalization of $0.66 billion.
Operations: Anika Therapeutics' revenue primarily stems from its medical products segment, which generated $120.65 million in the latest period. The company's gross profit margin was 62.16%, with significant costs attributed to operating expenses and cost of goods sold (COGS).
PE: -84.0x
Anika Therapeutics, a smaller player in the U.S. market, has shown promising signs of growth with sales reaching US$32.61 million in Q2 2026, up from US$28.22 million the previous year. Insider confidence is evident as they completed a buyback of 15% shares for US$30.39 million by June 2026. Despite relying solely on external borrowing for funding, Anika's earnings are projected to grow annually by nearly 60%, suggesting potential value for investors seeking growth opportunities in niche markets.
- Get an in-depth perspective on Anika Therapeutics' performance by reading our valuation report here.
Examine Anika Therapeutics' past performance report to understand how it has performed in the past.

Granite Ridge Resources (GRNT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Granite Ridge Resources is involved in the development, exploration, and production of oil and natural gas, with a market capitalization of approximately $1.35 billion.
Operations: The company generates revenue primarily from oil and natural gas development, exploration, and production, with recent quarterly revenues reaching $472.49 million. The gross profit margin has shown a downward trend over the last several periods, standing at 75.61% in the most recent quarter. Operating expenses have been significant, contributing to net income fluctuations and resulting in a negative net income of -$27.34 million for the latest period analyzed.
PE: -23.0x
Granite Ridge Resources, a smaller U.S. company, has shown potential for growth with forecasted earnings expected to increase by 80% annually. However, their financial position could be stronger as interest payments aren't well covered by earnings and funding relies on external borrowing. Recent board expansion may enhance strategic oversight, while consistent dividends of $0.11 per share reflect stability despite asset impairments of $9 million in Q2 2026. With daily production rising slightly to 32,044 Boe and net income increasing to US$30 million from US$25 million year-over-year in Q2 2026, the company demonstrates resilience amidst challenges.
Orion Group Holdings (ORN)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Orion Group Holdings is a construction company specializing in marine and concrete services with a market capitalization of $0.17 billion.
Operations: The company generates revenue primarily from its Marine and Concrete segments, with the Marine segment contributing $523.34 million and the Concrete segment $373.16 million. Over recent periods, the gross profit margin has shown some variation, reaching 13.02% in Q3 2025 before settling at 11.78% in Q2 2026.
PE: 102.8x
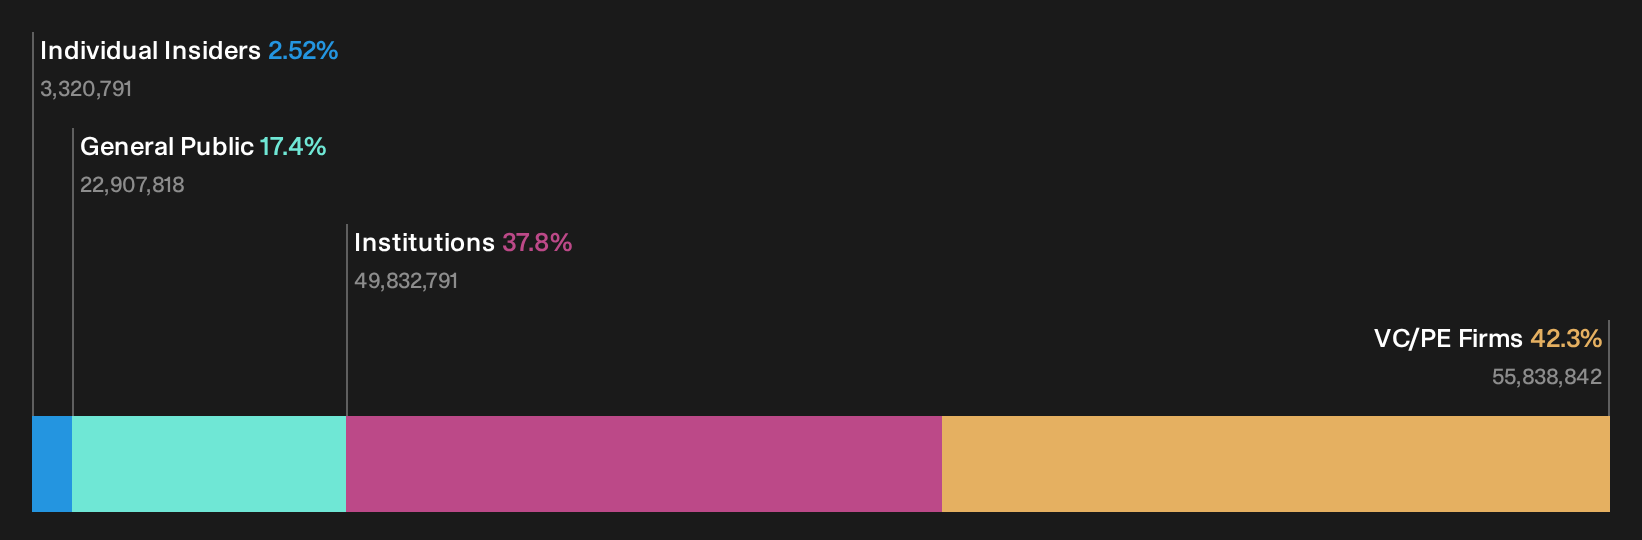
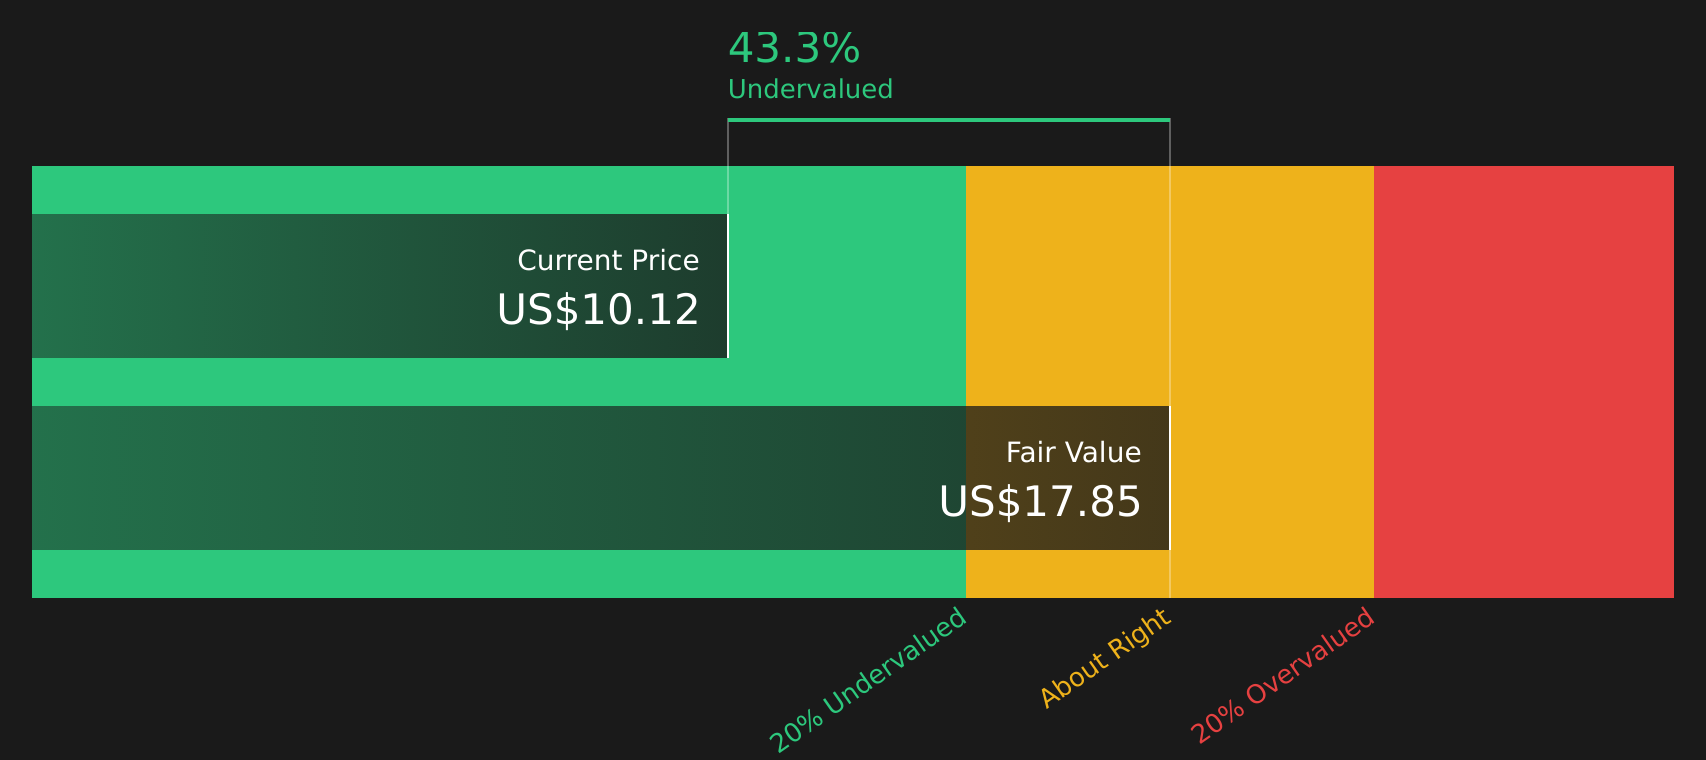
Orion Group Holdings, a smaller company in the U.S. market, shows potential despite recent challenges. Their net profit margin dipped from 1.2% to 0.4%, and interest payments remain a concern due to reliance on external borrowing. However, earnings are forecasted to grow nearly 56% annually, suggesting future upside. Insider confidence is evident as an independent director acquired 20,000 shares for US$192,430 in September 2026. Revenue guidance of US$900-950 million indicates anticipated growth for the year ending December 2026.
- Take a closer look at Orion Group Holdings' potential here in our valuation report.
Understand Orion Group Holdings' track record by examining our Past report.
Summing It All Up
- Unlock more gems! Our Undervalued US Small Caps With Insider Buying screener has unearthed 60 more companies for you to explore.Click here to unveil our expertly curated list of 63 Undervalued US Small Caps With Insider Buying.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com