


Is Natera (NTRA) Expensive As FDA Breakthrough Status Puts Its MCED Test In Focus?
FDA decision puts Natera’s MCED blood test in the spotlight
Natera (NTRA) just picked up U.S. FDA Breakthrough Device status for its multi cancer early detection blood test, a regulatory fast track that pushed the stock up 1.7%.
That 1.7% jump sits on top of strong recent momentum for Natera, with a 30-day share price return of 21.82% and a 90-day move of 46.96%. The 1-year total shareholder return of 130.07% and a very large 3-year total shareholder return suggest a longer-term rerating as the oncology pipeline, including Signatera trials and international approvals, shapes how investors view both growth potential and risk.
Scan beyond Natera and see how other diagnostics specialists are reacting to early detection breakthroughs by reviewing the curated 33 healthcare AI stocks in this space.
Natera now trades around $400 a share, above the average analyst target yet still at a sizable discount to some intrinsic value models. Is the recent FDA pop stretching the price or only closing the gap?
Most Popular Narrative: 13% Overvalued
Natera closed at $400.71, while the most followed narrative pegs fair value at $355.93, which leans toward a premium view that relies heavily on future execution.
Increasing adoption and acceptance of advanced molecular diagnostics is driving sustained volume and revenue growth across Natera's diversified portfolio, with significant headroom remaining for further penetration, particularly in oncology (Signatera) and organ health (Prospera). This will likely boost top-line revenue.
See why 19 investors see Natera as 13% overvalued.
Result: Fair Value of $355.93 (OVERVALUED)
Still, execution risk around reimbursement policy shifts, along with ongoing high R&D and SG&A spending, could quickly challenge the current Natera premium narrative.
Find out about the key risks to this Natera narrative.
Another View: Natera through a cash flow lens
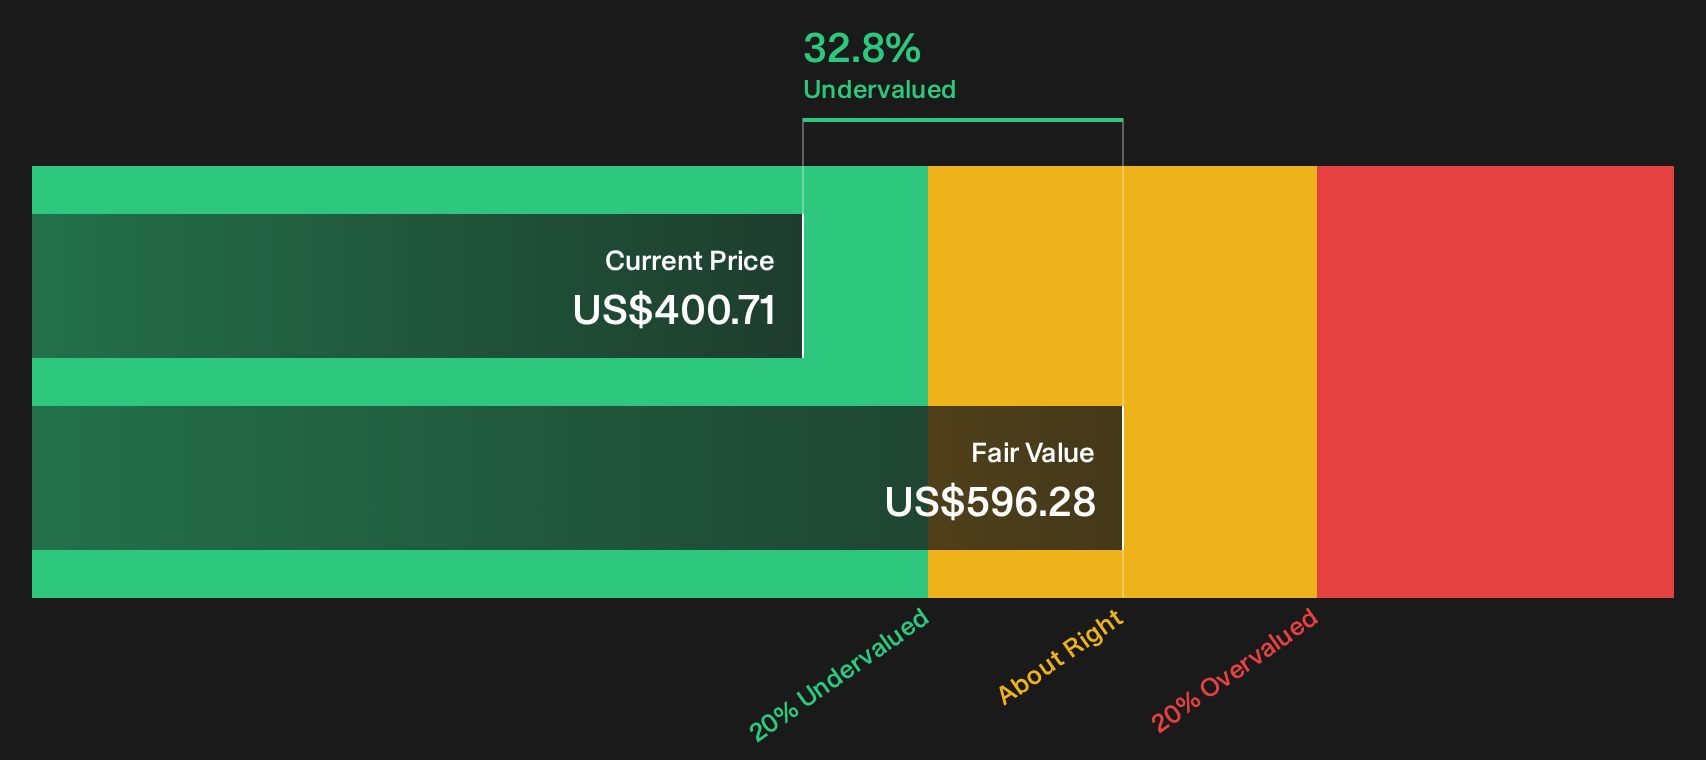
The fair value narrative around Natera looks very different when using the SWS DCF model. On this approach, the stock at $400.71 is assessed as trading at a 32.8% discount to an estimated future cash flow value of $596.28. Does that gap signal upside, or does it reflect very optimistic assumptions?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Natera is strong, yet the story is still being written. Consider reviewing the data while it is fresh and weigh the potential outcomes yourself using the 3 key rewards.
Looking for more Natera investment ideas?
If Natera has your attention, do not stop with a single ticker. Use the broader data to pressure test your thinking, compare opportunities and sharpen your watchlist.
- Target stronger quality at a discount by scanning the 29 high quality undervalued stocks that combine solid fundamentals with appealing prices.
- Prioritise resilience by reviewing the 31 resilient stocks with low risk scores that score well on stability and balance sheet strength.
- Get ahead of the crowd by checking the 20 high quality undiscovered gems before others start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com