


Global Growth Companies With High Insider Ownership For October 2026
In October 2026, global markets have been navigating a landscape marked by volatility in AI-related stocks and fluctuating energy prices driven by Middle East tensions. Amid these uncertainties, major U.S. indices like the S&P 500 and Dow Jones have shown resilience with modest gains, while European and Asian markets reflect mixed performances influenced by geopolitical developments and economic data. In such an environment, growth companies with high insider ownership can be particularly appealing as they often signal strong confidence from those closest to the business, potentially offering stability amidst market fluctuations.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We'll examine a selection from our screener results.
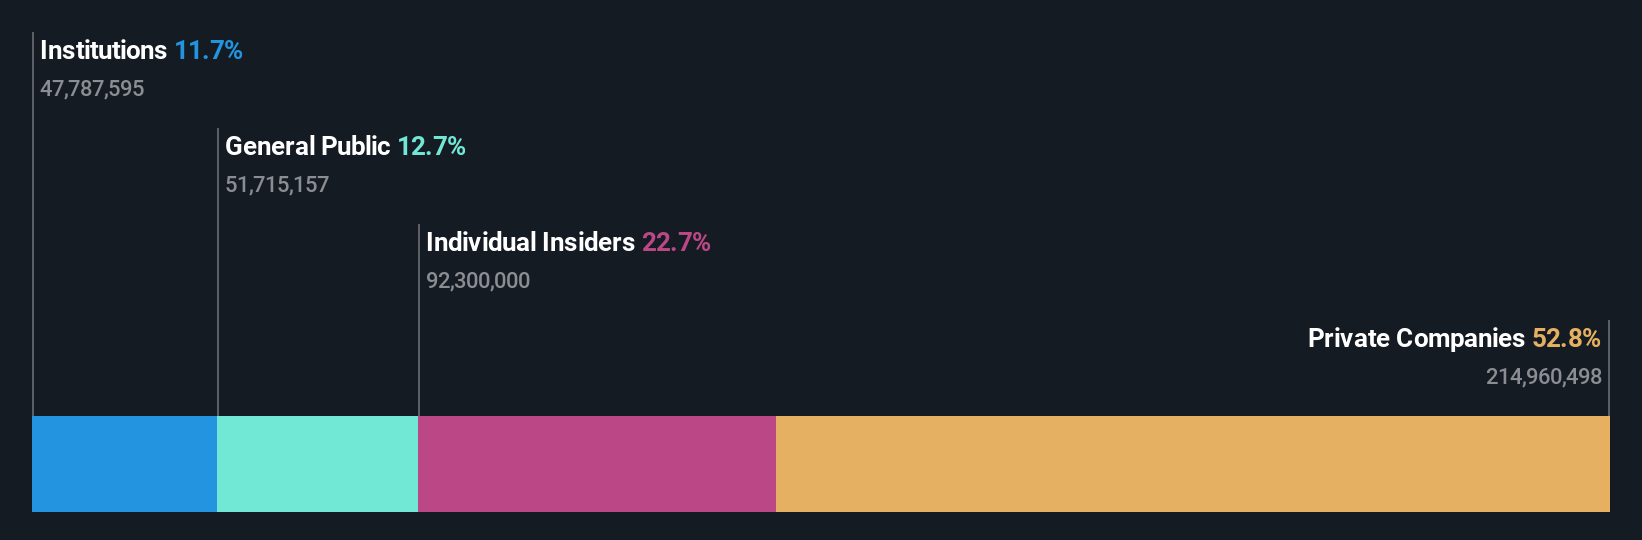
Servyou Software Group (SHSE:603171)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Servyou Software Group Co., Ltd. and its subsidiaries offer financial and tax information services in China, with a market cap of CN¥16.17 billion.
Operations: The company generates revenue primarily through its financial and tax information services in China.
Insider Ownership: 27.9%
Servyou Software Group's revenue is projected to grow at 20.2% annually, outpacing the Chinese market's 16.8%. Earnings are expected to rise significantly by 45.47% per year, surpassing the market average of 27%. Despite a low forecasted return on equity and an unstable dividend track record, recent earnings showed strong growth with sales reaching CNY 1.01 billion for H1 2026 and net income increasing to CNY 94 million from CNY 71.01 million last year.
- Delve into the full analysis future growth report here for a deeper understanding of Servyou Software Group.
- Our valuation report unveils the possibility Servyou Software Group's shares may be trading at a premium.
Shandong Dawn PolymerLtd (SZSE:002838)
Simply Wall St Growth Rating: ★★★★☆☆
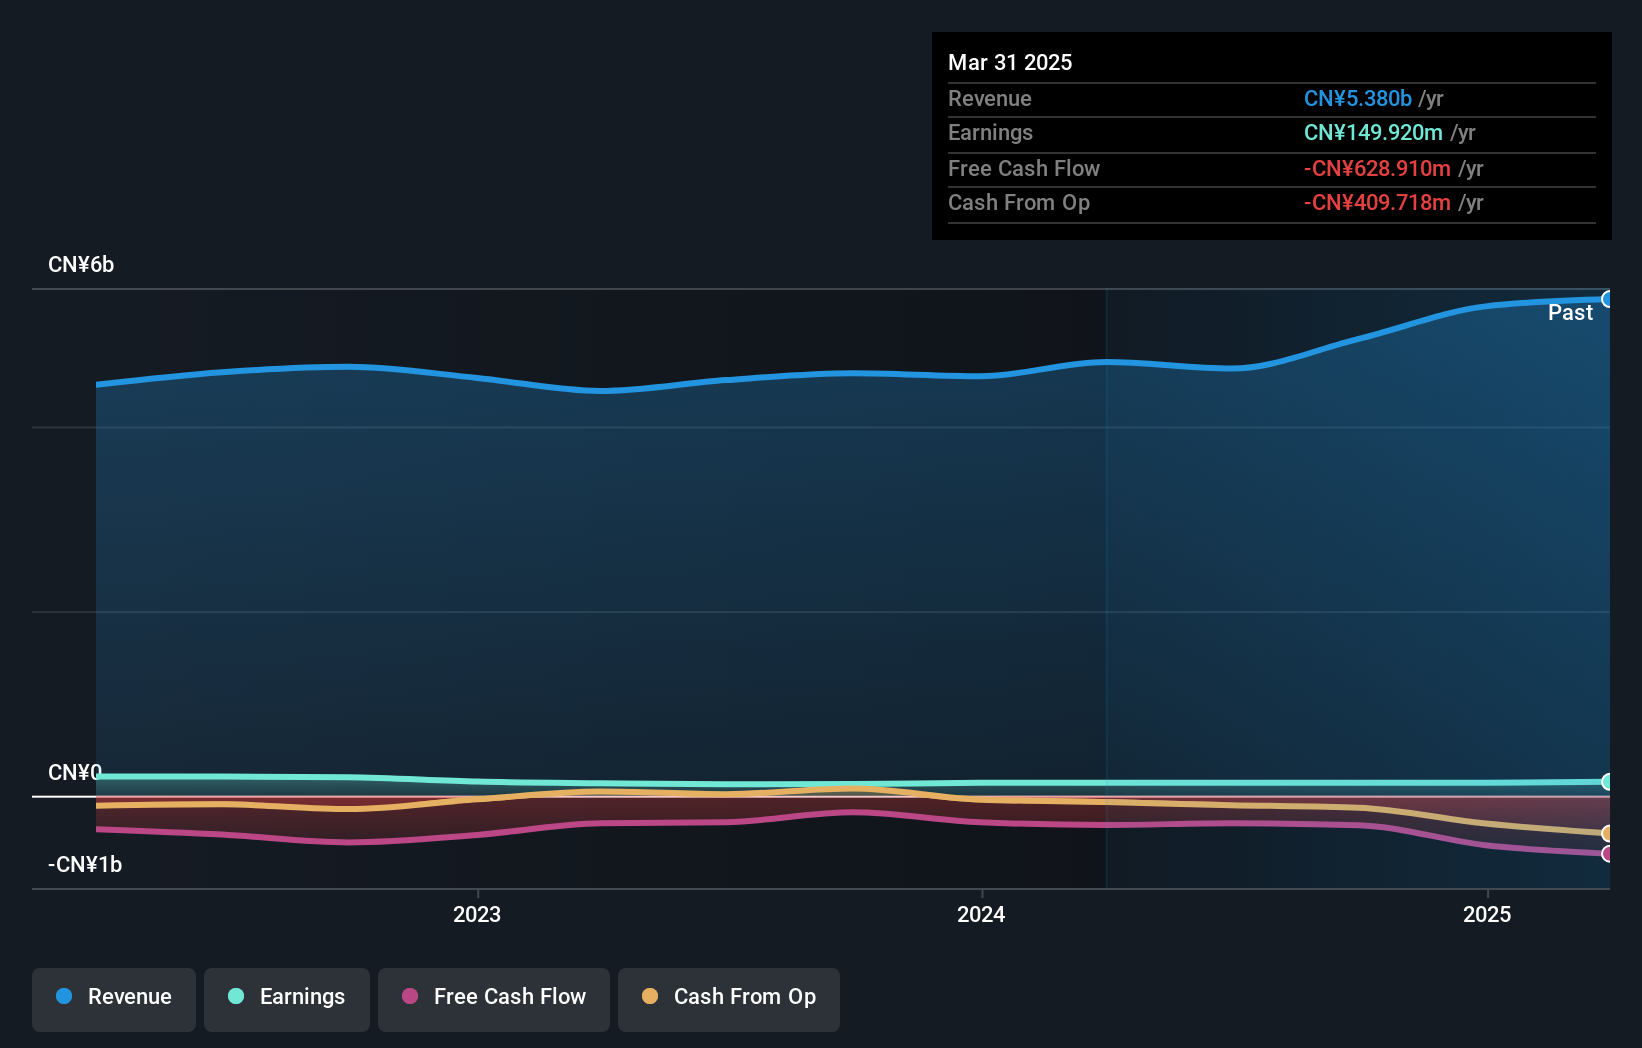
Overview: Shandong Dawn Polymer Co., Ltd. engages in the development, production, sale, and servicing of thermoplastic elastomers, modified plastics, master batches, and other products both in China and internationally with a market capitalization of CN¥12.42 billion.
Operations: The company's revenue segments include thermoplastic elastomers, modified plastics, and master batches, which are developed, produced, sold, and serviced both domestically and internationally.
Insider Ownership: 16.3%
Shandong Dawn Polymer Ltd. demonstrates strong growth potential with earnings expected to increase significantly by 31.8% annually, surpassing the Chinese market's 27%. Revenue is forecasted to grow at 19.5% per year, slightly below the 20% mark but faster than the market average. Recent shareholder approval of employee stock ownership plans indicates robust insider engagement. Despite a volatile share price and low dividend coverage by free cash flow, recent earnings showed substantial improvement with net income reaching CNY 236.95 million for H1 2026.
- Dive into the specifics of Shandong Dawn PolymerLtd here with our thorough growth forecast report.
- Our expertly prepared valuation report Shandong Dawn PolymerLtd implies its share price may be too high.
Easy Click Worldwide Network Technology (SZSE:301171)
Simply Wall St Growth Rating: ★★★★★☆
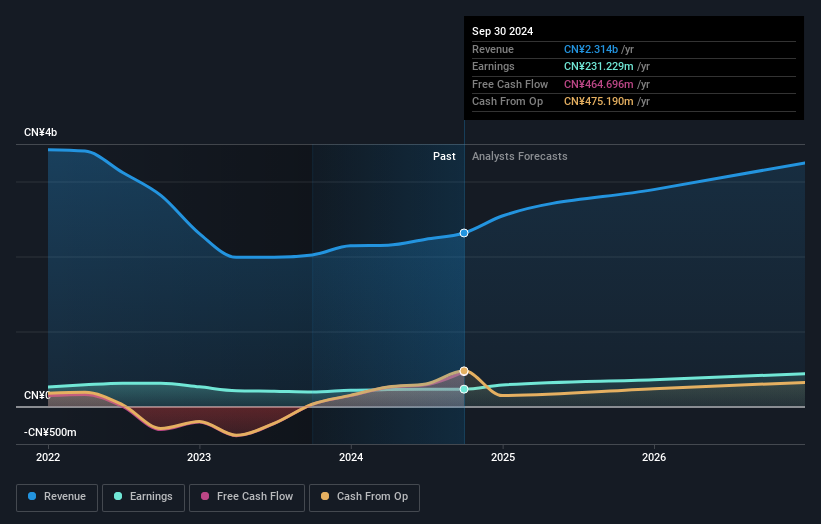
Overview: Easy Click Worldwide Network Technology Co., Ltd. (SZSE:301171) operates in the technology sector, focusing on network solutions, with a market cap of CN¥20.95 billion.
Operations: Unfortunately, the revenue segments for Easy Click Worldwide Network Technology Co., Ltd. are not provided in the text you shared. Therefore, I am unable to summarize them into a sentence.
Insider Ownership: 28.6%
Easy Click Worldwide Network Technology is poised for significant growth, with earnings forecasted to rise 47.06% annually, outpacing the Chinese market's 26.9%. Revenue is also expected to grow at a robust 24.5% per year. Despite recent earnings showing lower net income of CNY 78.45 million compared to last year's CNY 143.52 million, the company maintains strong growth prospects with high insider ownership and no substantial insider trading activity reported recently.
- Click here and access our complete growth analysis report to understand the dynamics of Easy Click Worldwide Network Technology.
- The valuation report we've compiled suggests that Easy Click Worldwide Network Technology's current price could be inflated.
Seize The Opportunity
- Embark on your investment journey to our 710 Fast Growing Global Companies With High Insider Ownership selection here.
- Interested In Other Possibilities? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com