


The Hartford Financial Services’ Quarterly Earnings Preview: What You Need to Know
The Hartford Financial Services Group, Inc. (HIG), headquartered in Hartford, Connecticut, is an American insurance and financial services company with a market capitalization of approximately $35 billion. The company provides property and casualty insurance, group benefits, and mutual funds to individuals and businesses, helping customers manage risks and protect their assets.
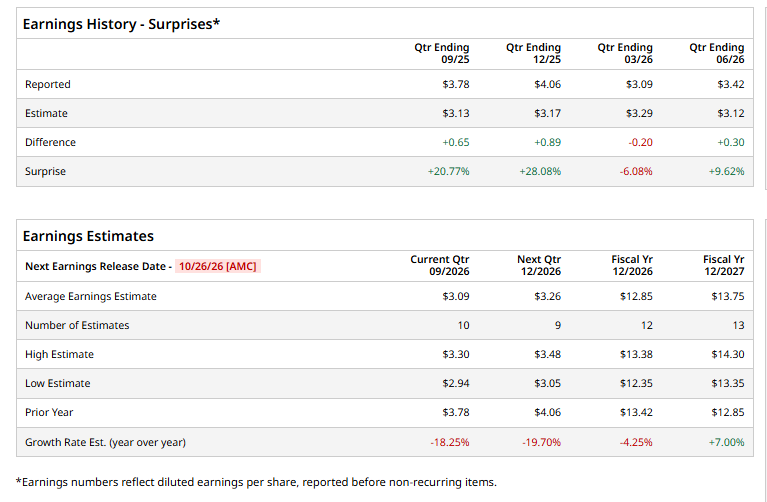
HIG is set to report its Q3 2026 earnings after the market closes on Monday, October 26. Ahead of the release, analysts expect diluted EPS of $3.09, down 18.3% from $3.78 in the year-ago quarter. However, HIG has exceeded Wall Street’s EPS estimates in three of the past four quarters, while missing in another quarter.
For fiscal 2026, analysts expect HIG to report EPS of $12.85, down 4.3% from $13.42 in fiscal 2025. Its EPS is projected to rebound, growing 7% year over year to $13.75 in fiscal 2027.
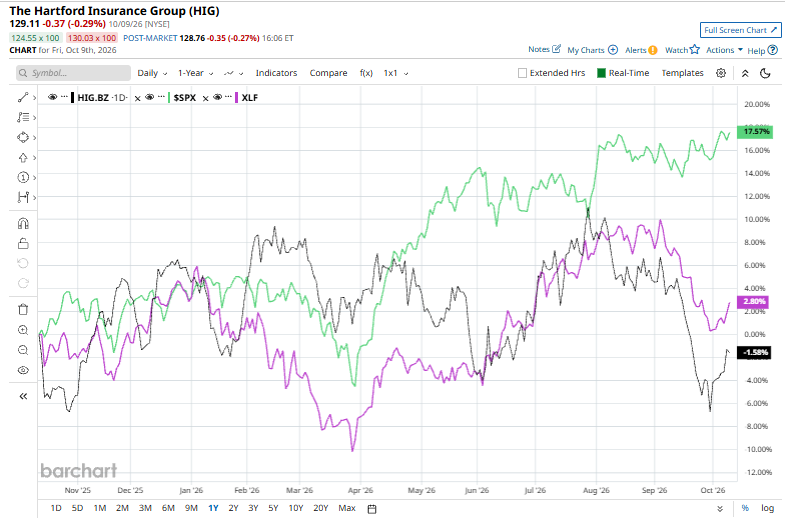
HIG stock has declined marginally over the past 52 weeks, substantially underperforming both the S&P 500 Index ($SPX), which gained 16%, and the State Street Financial Select Sector SPDR ETF (XLF), which gained 2.6% over the same period.
The Hartford Financial Services has underperformed the broader market over the past year, partly reflecting concerns about its growth prospects. The company’s net premiums earned grew at an annualized rate of 5.2% over the past two years, trailing smaller competitors. Meanwhile, projected sales growth of 2.6% over the next 12 months points to a further slowdown. HIG’s book value per share also grew at an annualized rate of 6.7% over the past five years, a relatively modest pace for the insurance sector.
Analysts remain somewhat bullish on HIG, with a consensus “Moderate Buy” rating. Of the 26 analysts covering the stock, nine recommend a “Strong Buy,” one recommends a “Moderate Buy,” and 16 recommend a “Hold.” Meanwhile, the average price target of $148.04 implies potential upside of 14.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.